In this commentary, Professor Ibrahim Ozturk examines the political economy of artificial intelligence (AI), highlighting its productive potential alongside distributional inequalities, financial vulnerabilities, and environmental costs. Distinguishing infrastructure investment from AI’s diffusion across the economy, he explores how productivity gains affect employment, wages, prices, inflation, and market concentration. The analysis considers how data governance, computing infrastructure, and financing arrangements shape the distribution of benefits and risks. Professor Ozturk also examines how labor displacement and economic insecurity may create opportunities for authoritarian populist mobilization, while AI-enabled surveillance raises concerns about democratic accountability. He advocates policies that distribute technological gains more equitably, strengthen institutional oversight, and protect household security. The central benchmark is a decent, dependable standard of living throughout employment transitions and retirement.
Artificial intelligence (AI) is rapidly reshaping the global economy, offering unprecedented opportunities for productivity growth, innovation, and economic transformation while raising profound questions about inequality, financial stability, environmental sustainability, and democratic governance. As investment in AI infrastructure accelerates, the diffusion of its applications across the real economy presents complex challenges concerning employment, wages, prices, inflation, and the distribution of economic gains. While AI can expand productive capacity and reduce costs, its benefits may become concentrated among powerful firms and capital owners, potentially transferring financial and environmental burdens to households.
These developments also raise concerns about market concentration, labor displacement, economic insecurity, and the political conditions that may facilitate authoritarian populist mobilization. Against this backdrop, this article examines the interconnected macroeconomic, distributional, financial, environmental, and institutional dimensions of AI, emphasizing the importance of effective governance, equitable access to technological benefits, and policies that protect economic security. The central challenge is ensuring that technological progress translates into shared prosperity, allowing households to maintain a decent and dependable standard of living throughout employment transitions and into retirement.
An AI system may help a worker complete a task in half the time. Who gains the other half? A firm may use the savings to lower prices, improve its product, reduce working hours, or cut its payroll. Its technology supplier may capture part of the gain through subscription fees, while shareholders benefit from higher margins. The same improvement in technical capability can therefore produce very different outcomes for workers, consumers, and investors. Those outcomes matter politically because they determine who can withstand disruption and who must depend on the discretion of employers, platforms, or public officials.
The distribution of these gains depends on two processes that unfold at different speeds. The investment cycle commits capital to data centers, chips, power, and networks before their revenues are known. The diffusion cycle depends on whether firms and public institutions can reorganize production around useful applications. Their interaction determines when costs are incurred, when productivity gains appear, and whether firms, households, or public institutions capture them.
Historical Lessons from Technological Transitions
The historical record of major technological transformations provides critical empirical and theoretical insights into the current AI trajectory. Joseph Schumpeter’s paradigm of “creative destruction” details how radical innovations continuously revolutionize the economic structure from within, destroying old industries and creating new ones. However, as Karl Polanyi famously demonstrated in his analysis of the Industrial Revolution, the expansion of the self-regulating market inflicts severe social dislocation during the transition. The pivotal political-economic question centers on the temporal duration of this transition: How long does the period of destruction last before new livelihoods emerge, and who possesses the financial resilience to endure it?
Britain’s Industrial Revolution offers a sobering historical precedent known as “Engels’ Pause.” As Allen documents, for nearly half a century after the initial adoption of industrial technologies, output per worker expanded significantly while real wages remained stagnant. Corporate profits claimed an escalating share of national income, accumulating to early industrial capitalists while working-class households suffered prolonged wage depression and deteriorating living conditions. Even if real wages eventually rise in the long run, the intergenerational timing of gains is central: workers displaced in one decade cannot feed their families on the theoretical equilibrium of a subsequent generation. Similarly, the rollout of electricity as a general-purpose technology (GPT) demonstrates that macro-level productivity acceleration requires extensive, multi-decade investments in complementary machinery, organizational workflows, and human capital. As Perez emphasizes, financial capital frequently accelerates the installation phase of new technological paradigms, driving speculative asset valuations long before real-economy productivity gains materialize.
The central historical challenge for AI is whether public institutions, labor markets, and non-tech sectors can cultivate human-centric applications as quickly as financial markets build out computational capacity. As Acemogluargues, technological trajectories are not preordained; innovation can be explicitly directed toward augmenting human capabilities rather than merely automating labor to cut immediate payroll costs.
Productivity, Prices and the Cost of Living
The task framework developed by Acemoglu and Restrepo distinguishes between automation that displaces labor and innovation that creates new tasks for people. An occupation often contains both kinds of opportunity. A nurse may spend less time on documentation and more time with patients. A firm could instead use the saved hours to raise staffing ratios. Which outcome follows depends on management decisions, demand for services, and workers’ and service users’ ability to influence deployment. The ILO’s occupational exposure estimates accordingly help identify where tasks may change. Actual displacement depends on adoption, cost, regulation, and work organization.
Evidence of complementarity deserves attention. In a study of customer support, AI assistance raised productivity by about 15 percent on average, with larger benefits for less experienced and lower-skilled agents. Access to advice previously available mainly through experience can help workers learn and perform more complex tasks. At the same time, a firm can use the same technology to change staffing levels or monitor individual performance. A productivity increase observed in one workplace tells us what the tool achieved in that setting. The division of the gain among wages, profits, and consumers is a separate empirical question. Estimates of aggregate productivity are sensitive to the share of tasks affected, the savings actually realized, and the cost of implementation.
The aggregate effect depends on the economic weight of the tasks affected, the savings realized after implementation costs and the scale of adoption. At the firm level, faster completion of a task raises output only when the task constrains production or the resources released can be put to productive use. A hospital that reduces administrative work may be able to see more patients if staff time is the binding constraint. If beds or specialist capacity are scarce, the gain may instead appear in shorter paperwork queues or better service quality. Investment in software, training, and organizational redesign also absorbs resources during the transition.
Control over specialized chips, cloud capacity, models, and distribution channels can influence where profits accrue. Large firms can capture substantial gains when other firms depend on their infrastructure or face high switching costs. Historical evidence on superstar firms links shifts in market share toward firms with lower labor shares to the aggregate decline in labor’s share. In AI markets, the relevant competition questions concern access to inputs and the terms on which firms can switch suppliers or reach customers. Control over training data and intellectual property adds another barrier: contested access to copyrighted works and uncertain licensing terms can favor incumbents with legal and computing scale. High market valuations indicate expectations about future earnings. Evidence of durable rents requires examining realized returns, entry barriers, and the scope for competition.
A decline in unit costs can lower prices when customers have credible alternatives and firms compete for their business. The same gain can widen margins or be captured upstream by providers of models and cloud infrastructure. The effect on the cost of living depends on the prices of goods and services that households actually buy, their budget shares and their disposable incomes. Cheaper digital services may raise consumer welfare while housing, food or utility bills continue to strain household budgets. For that reason, the relevant outcome is real purchasing power after essential expenses.
The inflation effect depends on timing. During the buildout, investment can raise demand for construction, equipment and electricity before new capacity comes online. As adoption spreads, lower unit costs and greater productive capacity can ease price pressures. Stronger investment or household spending can offset part of that effect. A one-time fall in the price of a service lowers its contribution to measured inflation during the adjustment period. A sustained change in aggregate inflation depends on how supply, demand and monetary policy respond.
Data Centers, Environmental Costs and Financial Risk
Data centers make the physical demands of AI visible. New facilities require power connections, cooling, and land. Their local effects depend on the energy mix, water availability, and utility tariff design. A utility may commit to network upgrades before a facility begins operating. If the project is delayed or uses less capacity than contracted, the allocation of the resulting costs depends on the tariff and the developer’s commitments. Local authorities should distinguish temporary construction jobs from continuing employment and compare expected tax receipts with abatements and the cost of public infrastructure. The International Energy Agency’s (IEA) analysis underlines the importance of location and grid capacity when assessing data center electricity demand.
Political resistance reaches beyond immediate neighbors. In a May 2026 survey reported by Axios, 49 percent of registered voters supported a temporary moratorium on new data center construction. Among respondents opposed to data centers, 8 percent said they knew of a facility near their home. That figure measures reported awareness of proximity. In July, Navigator Research found that 65 percent of respondents in its survey of competitive congressional districts agreed with a statement accusing AI executives of using their wealth to influence politics for their own benefit. Taken together, these results are consistent with broader distrust of how the investment boom is governed. Local referendums and campaigns in the November midterms gave that distrust a political outlet.
The scale of financing makes the distribution of risk equally important. Van Nieuwerburgh estimates that a scenario in which the United States builds 188 GW of AI capacity by 2032 would require nearly $9 trillion in investment, equivalent to about 3.2 percent of annual GDP over 2025–2032. The estimate depends on the assumed capacity and costs. Project loans, leases, joint ventures, and private credit spread funding across several parties, and their terms determine where losses fall. An investor who has yet to commit can defer spending. A leveraged project under construction can face continued interest charges while a grid connection or permit delays revenue.
Accounting depreciation spreads an asset’s recorded cost over its useful life. Investment recovery depends on cash flow, while debt maturity determines when creditors must be paid or refinanced. These schedules can diverge. A building and its power connection may serve multiple generations of equipment. Accelerators can lose economic value more quickly as newer chips become available. The project must cover operating costs and equipment replacement as well as debt service. A project that relies on a small number of tenants is also exposed to their capacity to honor commitments. If borrowing costs rise as utilization disappoints, the financing problem can become acute well before the site loses productive value.
Janeway separates the productive legacy of speculative investment from the financial consequences of its collapse. Railways, electricity networks, and fiber networks could continue to serve users after their original investors suffered losses. AI infrastructure may have a similar afterlife, although that possibility varies across power connections, buildings, and rapidly aging chips. The applications that justify investment on a social basis can take longer to spread than the contracts that finance the investment allow. The risk to the wider economy depends on who has financed the buildout and how leveraged those institutions are. Jordà, Schularick, and Taylor (2015) and Janeway (2026) have shown that historical asset bubbles fueled by credit tended to be followed by deeper recessions. For AI, that finding motivates scrutiny of banks’ direct and indirect exposures, including through private credit. It leaves the scale of those exposures to be established empirically.
A useful test is to compare the operator’s expected return with the project’s wider benefits and costs. The latter include productivity in sectors using AI, net employment and tax benefits in host communities, the resources drawn from local power and water systems, and the opportunity cost of public subsidies. A profitable project can impose costs on households if tariffs transfer network expenses to them. An unprofitable project can leave useful infrastructure behind. The terms of approval and financing determine how much of either outcome is shared with the public.
Electricity and water also link environmental constraints to financing. A delayed grid connection can leave a completed facility unable to earn revenue while interest continues to accrue. If the utility has already expanded capacity and the project is canceled, tariffs and contracts determine whether the developer, the utility or other ratepayers bear the cost. Water availability must be assessed at the basin level, and emissions depend on the generation mix and the power actually added to serve the load.
Income Distribution, Wealth and Economic Security
Four distributional questions follow. The first concerns wages among workers. The second concerns labor’s share of income relative to capital. The third concerns the ownership of assets that generate capital income. The fourth concerns where gains accrue geographically. An AI tool can narrow skill differences among employees while shifting income towards capital owners. The wealth effects can persist if higher capital returns are reinvested and ownership remains concentrated.
International distribution raises another issue. Countries reliant on labor-intensive exports can face weaker demand for some tasks even as firms elsewhere capture automation gains. Access to affordable computing, skills, and local infrastructure can help those countries develop their own uses. Their capacity to tax internationally mobile income also influences whether productivity gains finance public services where workers bear transition costs. US–China semiconductor controls and efforts to build sovereign AI capacity raise the cost of access for third countries, making compute dependence a new channel of geopolitical and developmental inequality. Redistribution within the economies that host the largest technology firms can leave these cross-border effects largely untouched.
Labor income, wealth and security can move in different directions. Labor’s share can decline even as some real wages rise, while higher average wages can coexist with fewer routes into stable employment. Job loss, volatile hours and insecure retirement affect people’s ability to plan and withstand shocks. A distributional assessment should therefore track real disposable income after essential expenses, exposure to income losses and pension adequacy alongside wage dispersion, labor’s share and wealth concentration.
Economic Insecurity, Surveillance and Authoritarian Populism
Workers’ ability to refuse unfavorable terms depends partly on their access to other jobs, savings, and public support. A technological shock can weaken those alternatives before it reduces headline employment. Workers may accept worse conditions because replacement seems more plausible. Younger entrants can face fewer opportunities to gain experience if employers automate the tasks through which they previously learned. The distribution of these risks matters for political trust, particularly where the costs fall on communities that already have few alternatives.
Evidence from previous waves of automation identifies one pathway. Anelli, Colantone, and Stanig find that exposure to industrial robots increased support for the radical right in their study of 13 Western European countries. The study concerns a particular kind of automation and a particular political context. It offers a mechanism to test in the AI transition. Parties can frame economic insecurity as a loss of status or control and promise protection through exclusion or personal loyalty. The strength of that appeal depends on local institutions, political organization, and the narratives that parties and media advance. The backlash against data centers likewise can lead to ordinary democratic demands for transparency and cost sharing. Opposition becomes relevant to authoritarian populism when political actors mobilize it against pluralism or use selective protection to reward supporters.
A second pathway concerns the tools available to governments. Beraja et al. document how procurement of facial recognition technology in China helped strengthen political control and supported further development of the technology. Public demand for surveillance can therefore help create a market for capabilities that reinforce the incumbent’s power. This evidence concerns a specific regime and technology. It illustrates why oversight of procurement, access to personal data, and avenues of legal challenge matter as AI spreads into public administration.
The two pathways can interact when citizens with fewer economic alternatives also face more intrusive monitoring. If access to work or public benefits is mediated by opaque scoring systems, challenging a decision may become costly for people who rely on it. Where the government controls access to benefits or tolerates selective enforcement, it can use economic insecurity to reward loyalty. Opaque models can also amplify bias in credit, hiring and public-benefit decisions, while synthetic media can lower the cost of electoral deception and weaken trust in public evidence. Rights to explanation, appeal, independent review and provenance disclosures matter because they make both automated decisions and manipulated information contestable.
Policies for Sharing Gains and Protecting Independence
The structure of the AI economy creates strong pressures toward faster wealth concentration and a more unequal distribution of income. A central question for democratic political economy is whether these pressures can coexist with a decent and dependable standard of living for the broad majority. That standard has concrete implications: households should be able to meet ordinary expenses without persistent anxiety, withstand a spell of unemployment or a temporary loss of earnings without financial distress, and look ahead to retirement with reasonable confidence. The policy test is whether people can count on that level of security throughout their lives as technological change alters the jobs and income sources on which they depend.
This distinction matters for understanding the appeal of authoritarian populism. When people lose confidence that established institutions can offer a credible path to a secure life, promises of protection from leaders who claim to speak for those left behind can gain force. A dependable income floor, backed by enforceable social rights and adequate pensions, would help restore the material basis for confidence in democratic institutions. How widely that security is shared should be a central criterion for judging the distributional consequences of the AI transition.
The immediate task is to align investment decisions with the costs they create. Utilities and regulators can require large users to cover attributable network upgrades and establish credible payment commitments if demand falls short. Local authorities can publish expected fiscal costs and benefits, assess water use in the affected basin, and tie incentives to measurable commitments. Financial supervisors need visibility into the routes by which leveraged projects can transmit losses. Separately, AI agents linked to payments, national accounts or critical infrastructure introduce operational and cyber risks: unauthorized instructions, data leakage and correlated model failures can transmit shocks even without excessive leverage. These measures clarify who bears the risk before the public is asked to absorb it.
Tax policy can then address who receives the gains. The case for reviewing the treatment of capital income and economic rents becomes stronger if automation shifts the tax base away from wages while raising demand for social protection. The design should distinguish returns needed to finance investment from rents sustained by market power or privileged access to scarce resources. The IMF staff analysis favors strengthening capital income taxation over a general tax on generative AI use. Models that find a role for taxing automation show that the result depends on transition conditions and workers’ ability to move into new occupations. International coordination can help keep mobile profits within reach of taxation, while leaving room for governments to choose how to support local adjustment.
The use of revenue is as important as its collection. Portable benefits and income support can allow workers to change jobs without losing basic security. Education systems must also prepare entrants for AI-complementary judgment, digital literacy, and transferable skills; reskilling is more valuable when it connects to actual demand, and workers can afford to take it up. Collective bargaining can give employees a say in how productivity gains translate into pay, working time, or the quality of services. Broad-based capital ownership, including through independently governed public or worker funds, could extend access to investment returns. Such arrangements require transparent rules for governance and distribution.
Public institutions also influence which applications are developed. Open procurement and access to shared computing resources can expand the pool of firms and researchers able to develop applications. Governments can use procurement to specify observable goals such as reducing administrative burdens, improving service quality, or giving professionals more time with patients and students. Risk-tiered audits, human oversight, data provenance and enforceable rights to challenge automated decisions are especially important when the public cannot choose another provider. Copyright licensing and creator remuneration should be addressed without allowing rights aggregation to entrench dominant platforms. The test is whether these arrangements increase the capacity of people and institutions to make their own decisions as they adopt the technology.
In conclusion, the AI transition will be shaped by the gap between the pace of infrastructure investment and the rate at which useful applications spread. Investment can strain power systems and balance sheets before productivity gains are realized. As those gains arrive, competition, ownership, and bargaining institutions will determine how much reaches households through prices, wages, and public services. The democratic consequences depend partly on whether people can absorb disruption without becoming dependent on discretionary protection. A credible response must link investment risk to the distribution of returns, safeguard critical systems and epistemic integrity, and preserve households’ ability to plan their lives. Without institutions that govern ownership, data, and public accountability, productivity alone cannot guarantee shared prosperity or democratic resilience.
In this commentary, Nikoletta Syvak examines Europe’s energy trilemma—the competing imperatives of affordability, energy security, and environmental sustainability—and how tensions between diversification and rising energy costs fuel populist politics. As the European Union seeks to reduce its dependence on Russian fossil fuels and accelerate the green transition, populist actors exploit economic grievances by portraying Brussels’ energy policies as burdens imposed by distant elites on ordinary citizens. Drawing on developments in Slovakia, Hungary, the Czech Republic, and Germany, Syvak explores how affordability concerns challenge European solidarity and create opportunities for populist mobilization. She argues that addressing this dilemma requires targeted household compensation, greater transparency about diversification costs, and pragmatic energy policies that balance strategic independence with economic affordability and public trust.
By Nikoletta Syvak*
Energy insecurity has become an increasingly important driver of populist mobilization in Europe, exposing tensions between technocratic policymaking, socioeconomic grievances, and democratic legitimacy. As the EU balances energy diversification, affordability, and environmental sustainability, populist actors frame rising energy costs as evidence that Brussels prioritizes geopolitical ambitions over ordinary citizens’ needs. Yet these grievances reflect genuine economic pressures rather than merely populist narratives. The challenge is to address these concerns without undermining European solidarity or long-term energy security.
On October 29, 2026, speaking to the press in Luxembourg on the sidelines of the EU Energy Council, Energy Commissioner Dan Jørgensen warned that the upcoming winter “will be a difficult period for many European citizens.” He noted that the situation had reached the point where EU citizens would simply be unable to pay their heating bills. The problem, he emphasized, lies not in a physical shortage, but in prices: if they cannot pay the bills, “then it doesn’t matter how much gas is available.”
According to Jørgensen, the current crisis is more significant than the shock of 2022, because it now affects not only gas but also oil and petroleum products, which turned out to be a consequence not only of the war in Ukraine and the damaged energy infrastructure but also of the situation in the Middle East. In essence, the commissioner described the main contradiction of European energy policy: the EU seeks to reduce its strategic dependence on other countries; EU citizens want energy to be affordable. These two goals intersect, but they are not the same, and the gap between them has become one of the most fertile grounds for populist politics in Europe.
This commentary asserts that it is not the populists who create the contradiction between affordability and diversification, but they can politicize this crisis. Whether the EU will be able to implement its energy security program depends on whether it manages to bridge this gap before the populists continue to exploit it.
Brussels Confronts the Energy Security–Affordability Dilemma
The European Commission’s assessment of the energy crisis currently unfolding in the EU can be judged by the meeting held in October 19 in Bratislava, which was attended not only by Jørgensen, a member of the European Commission for Energy, but also by the energy ministers of the Visegrád Group countries (the Czech Republic, Hungary, Poland, and Slovakia). During the press conference, Jørgensen noted that the EU was dependent on Russia, but now the Union is getting rid of this dependence. However, the problem is that, as Jørgensen added, the EU now depends on the global market, so events in the Middle East affect the situation with the energy crisis in Europe. According to the Ember analytical center, due to the rise in prices caused by the war involving Iran, wholesale electricity futures in Central Europe have increased in price by more than 60% compared to the pre‑crisis level.
During the European Council meeting (October 15–16, 2026), ministers drew attention to their request: they asked to postpone the introduction of Emissions Trading System 2 (ETS2) until 2030, to allocate funds from the EU budget for the development of oil and gas infrastructure, and to provide greater flexibility in the phased withdrawal from Russian gas. Seven EU member states insisted on making amendments to ETS2, but the leaders only asked the European Commissionto analyze the consequences of these changes. On October 28, Jørgensen added that over the past two decades, a quarter of oil refineries in the EU have closed, which has led to a reduction in domestic production capacity by approximately 10%, and that the diesel fuel market will be under pressure until at least 2027.
The European Commission’s response is logical: support should be targeted and temporary, and it should not hinder the transition away from imported fossil fuels. While this position is reasonable, it also implicitly acknowledges a fundamental reality: ending energy agreements with Russia did not free Europe from the risks associated with fossil fuel imports; it merely shifted their source, leaving households to bear the costs of this transition.
Two Approaches to EU Energy Policy
The first logic is responsible for diversification: according to the European Commission’s report on the state of the Energy Union for 2025, Russia’s share of EU gas imports decreased from 45% in 2021 to 19% in 2024 and 12% by August 2025. Regulation (EU) 2026/261, adopted on January 26, 2026, turns this into law: supplies of Russian LNG should end by the end of 2026, and pipeline gas supplies by September 30, 2027, with a possible extension until November 1, 2027. The Law on Zero-Emission Industries and the Law on Essential Raw Materials apply the same logic to environmentally friendly technologies.
The second approach is affordability: Draghi’s report says that EU companies pay two to three times more for electricitythan US firms, and four to five times more for gas. Households are not deprived of attention: according to Eurostat, in the second half of 2025, the average price of electricity for households in the EU was 28.96 euros per 100 kWh, which is a stable indicator, but still significantly higher than the level that existed before 2022.
In policy research, this is called the energy trilemma: security, affordability, and sustainability cannot be achievedsimultaneously. Diversification is a long-term insurance policy, but insurance premiums are already being paid due to newinfrastructure, more expensive supply routes and carbon prices. These surcharges are borne by households and industry,and they are visible on every account.
Where Tensions Arise: Supply Chains in the Clean Technology Sector
The same need to find a compromise is once again evident in the very process of the energy transition. According to theInternational Energy Agency, China’s share in each stage of the production of solar panels: polysilicon, ingots, plates,cells and modules-exceeds 80%, production costs there are about 35% lower than in Europe, and Chinese economies ofscale have helped reduce the cost of solar energy by more than 80%.
However, these data are primarily a structural feature of the market, not a threat in themselves. China is an indispensablesupplier for Europe during the transition period, and cheap environmentally friendly technologies are one of the mostreliable ways to reduce electricity prices in the long term. However, the EU’s sustainable development program: benchmarks for domestic production in accordance with the Zero Net Profit Industry Act, trade protection tools, andsupply diversification – increases initial costs to reduce the risk of concentration.
Thus, the dilemma surrounding natural gas and solar power takes the same form. Environmental sustainability is expensive today; tomorrow’s most affordable energy supply carries the risk of concentration. Neither of these options is wrong, but each results in losers who can be mobilized.
Populist Narratives
According to the ideological definition of Mudde (2024), populism divides society into “pure people” and “corrupt elite”. With regard to energy, this turns a political compromise into a moral conflict: ordinary people pay the bills, while distant Brussels pursues geopolitics or ideology at their expense. As Huber et al. (2021) show, populists in power tend to persist in seeking concessions and abandonment of EU energy and climate policies, often in conjunction with governments with unpopular views. The European Commission is not a populist player in this case. This is a technocratic analogue, against which a populist story is told.
Robert Fico, the Prime Minister of Slovakia, is a prominent figure in the world of populism. His government maintainsthat cutting off Russian energy supplies would cause severe harm to households and businesses. Slovakia and Hungary were the only two countries to vote against Regulation 2026/261, and on April 24, 2026, Slovakia filed a lawsuit to have this regulation declared invalid in the Court of Justice of the European Union. Fico promised that in 2026, energy prices for 90% of households would remain unchanged. The pattern is clear: cheap energy is presented as a symbol of national independence, which is defended through vetoes and legal proceedings.
Andrej Babiš, the Prime Minister of the Czech Republic, has taken a different approach. The Czech Republic has already reduced its reliance on Russian gas imports to 7% by 2023. The Babiš government has been more critical of the EU’s energy policy than its predecessor, and the Czech Republic has joined efforts to delay the implementation of ETS2. In areas where diversification has already been achieved, the focus has shifted from supply routes to climate and pricing instruments.
The Alternative for Germany (AfD) party represents an opposition position. Initially, its proposal to abolish the carbon dioxide emissions fee and the Building Energy Act was rejected, but in July 2026 it was reformed by the law on building modernization. The AfD speaker called the government’s policy “ineffective and inhumane”. Without accountability for the government’s actions, everything is simple: every euro spent on carbon fees is a cost imposed by the elites.
Hungary added a note: the Viktor Orbán administration filed a lawsuit against the gas ban in February 2026, but lost power in April. Nevertheless, in October, Hungary still supported the Visegrad Group’s call for flexibility regarding the Russian phase-out and the effort to modify the ETS2. The demand for affordability is not solely driven by populism: populists are simply the most successful entrepreneurs in this area.
Consequences for the European Union
The first risk is division: legal disputes, the threat of a veto, and demands for national exemptions, Italy reportedly soughta waiver from ETS2, similar to the one granted to Spain and Portugal in 2023, undermine the concept of a unified energy strategy, one exemption at a time.
The second risk is coalition-building: when it comes to affordability, populist governments are no longer isolated, they can join forces with mainstream governments under the pressure of fiscal and electoral considerations.
The third risk is external: the EU, which is struggling to maintain its own diversification rules, weakens its credibility in dealing with Russia and its negotiating position with other suppliers, including LNG exporters and manufacturers of clean technologies.
The Commission’s proposal for targeted and temporary assistance is essential, but not sufficient. The success of diversification will depend on the willingness of all citizens to share the burden.
To counter the appeal of populists, three measures are necessary: First, give priority to compensation. The funds from the Social Climate Fund and ETS2 should be distributed to low- and middle-income households, as the European Commission is already discussing with the European Investment Bank.
Secondly, it is important to ensure transparency of security costs: importance to clearly identify the costs of security measures, as well as the additional costs associated with the 2022 crisis, in order to fully assess the benefits of diversification.
Finally, it is necessary to apply a more practical approach to energy policy: reducing the risks of excessive dependence of the country on any one source, while ensuring access to imports at competitive prices, including from China. After all, Europe’s energy security depends not only on pipelines, terminals, and supply chains, but also on the support of its citizens.
In sum, the European Union’s energy dilemma is not merely a technical question of supply diversification, affordability, or environmental sustainability; it is also a political challenge with profound implications for democratic legitimacy and European integration. Populist actors do not create the structural tensions underlying energy policy, but they can transform economic grievances into narratives of elite indifference and national sovereignty. If the costs of diversification and the green transition remain unevenly distributed, public dissatisfaction may deepen political polarization and weaken support for common European policies. Addressing these risks requires transparent policymaking, targeted social protection, and a pragmatic approach to energy security. The EU’s long-term success will depend not only on reducing strategic dependencies but also on maintaining citizens’ trust and ensuring that the transition is socially sustainable.
(*) Nikoletta Syvak is a Graduate Student, Department of Political Science and International Relations, East China Normal University (ECNU). Email: syvaknikoletta@gmail.com
In this commentary, Professor Ibrahim Ozturk examines whether recent electoral defeats of authoritarian populists in the United States, Hungary, Brazil, and Serbia signal an emerging democratic counterwave or merely temporary setbacks for populism. Arguing that Trumpism’s electoral defeat does not eliminate the structural conditions that produced it, Professor Ozturk explores how economic inequality, institutional capture, globalization, and technological concentration continue to undermine democratic legitimacy. Drawing on comparative political economy and Daron Acemoglu’s scholarship, he emphasizes the urgency of rebuilding political representation, shared prosperity, and democratic control over technological change. Moreover, he warns that electoral victories alone cannot secure democratic renewal: without credible economic alternatives, institutional reconstruction, and effective governance, authoritarian populism may return in more resilient forms.
By Ibrahim Ozturk
Can electoral defeats in the United States, Hungary, Brazil and Serbia become a genuine democratic counterwave—or will populism return unless its structural causes are addressed? Donald Trump’s resounding defeat in the November 2026 midterm elections, following electoral breakthroughs against authoritarian populists in Hungary, Brazil and Serbia, and partly in Israel, though with significant uncertainties, may mark the beginning of a democratic counterwave. Yet elections can remove or constrain leaders without eliminating the structural conditions that produced them. Unless democratic governments rebuild political representation, state capacity and shared prosperity, today’s victories may pave the way for tomorrow’s populist return.
The Democratic victory was much more than an ordinary shift in the congressional balance of power. By taking control of both the House of Representatives and the Senate—including victories in states and constituencies Trump had carried comfortably only two years earlier—Democrats delivered the most consequential institutional rebuke to Trump since his return to the White House.
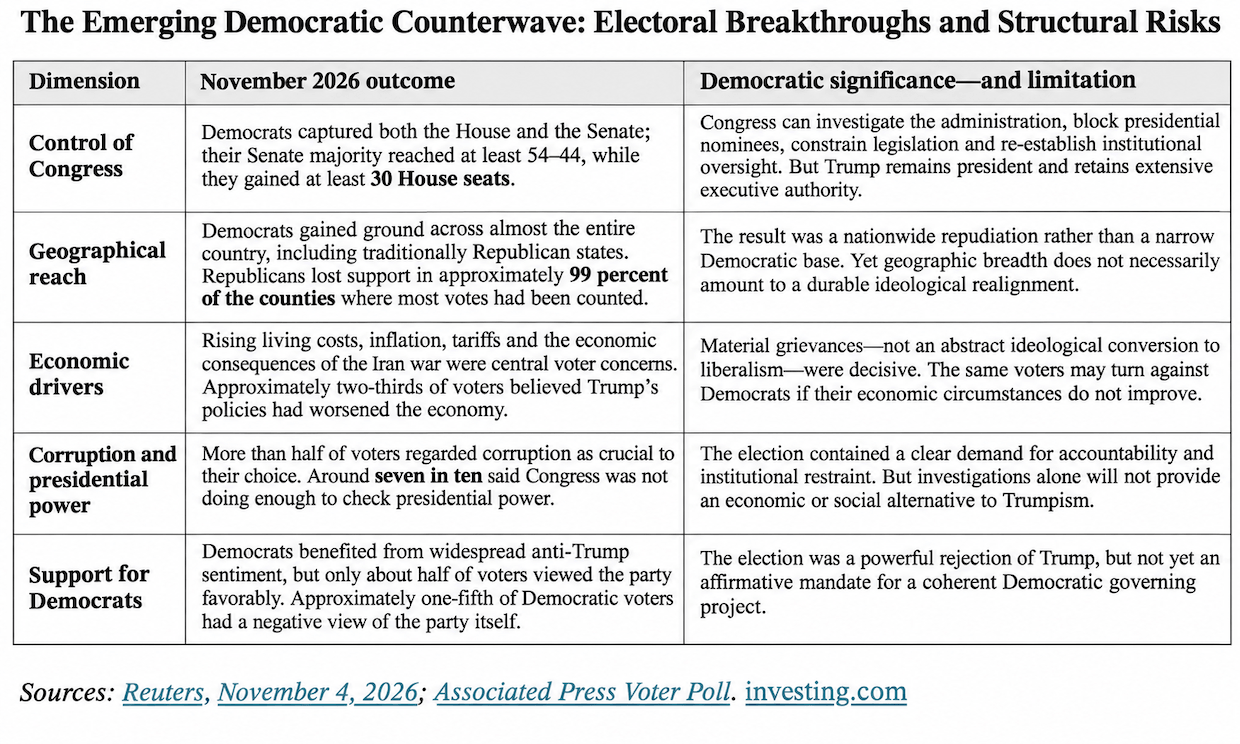
According to Reuters’ detailed account of the results, Democrats secured at least 54 Senate seats and gained at least 30 seats in the House. The electoral shift extended well beyond established Democratic territory, reaching deeply Republican states such as Texas, Kansas and South Carolina.
The table reveals the election’s two-sided character. On the one hand, the scale and geographical spread of the Democratic victory make it impossible to dismiss the result as a routine midterm correction. Trump-backed Republicans lost support almost everywhere, including in regions that had recently seemed beyond the Democrats’ reach. The outcome has restored Congress’s capacity to investigate abuses, resist presidential appointments and prevent the legislature from functioning as an extension of the executive branch.
This institutional dimension is especially important given the severity of America’s democratic deterioration. The V-Dem Democracy Report 2026 recorded a 24 percent decline in the United States’ Liberal Democracy Index during the first year of Trump’s second term, with the country falling from twentieth to fifty-first place globally. V-Dem identified legislative constraints as the most severely damaged component of American democracy and described the speed of executive aggrandizement as unprecedented in modern American history.
Against this background, restoring an independently controlled Congress is not merely a partisan change. It reactivates one of the principal constitutional mechanisms capable of constraining executive power. It may block further democratic erosion and create institutional space for recovery. But this is still a lifeline, not a democratic restoration—and certainly not the end of Trumpism. Trump remains in the White House. The institutional damage inflicted on the civil service, judiciary, regulatory agencies, universities, media and wider public sphere has not been reversed. Nor have the economic and cultural grievances that returned him to power in 2024 disappeared. Congressional control may constrain Trump’s room to maneuver, but it cannot by itself rebuild public trust, reverse inequality, or restore the social foundations of liberal democracy.
The second half of the table is therefore as important as the first. The Democrats’ victory was broad, but support for the Democratic Party remains relatively shallow. The Associated Press Voter Poll found that many voters who supported Democratic congressional candidates remained dissatisfied with the party itself. Roughly one-fifth of Democratic voters held an unfavorable view of the party they had just voted for. Many were not endorsing a clear Democratic program; they were looking for an instrument to restrain Trump and punish the incumbent government.
The crucial fact, therefore, is that many of the citizens who punished Trump in 2026 were the same economically and culturally frustrated voters who had punished Joe Biden and the Democrats in 2024. Their movement between the parties reflects neither ideological conversion nor a stable embrace of liberal democracy. It reflects a volatile electorate that repeatedly votes against governments perceived to have failed on prices, employment, security, public services, and political integrity.
The election’s economic geography reinforces this interpretation. Voters who reported serious hardship from inflation and everyday costs moved decisively toward Democratic candidates—even in Republican strongholds. They blamed Trump’s tariffs, the Iran war and the failure to fulfill his promise to reduce prices. Corruption also mattered, particularly the perception that the presidency was being used to advance Trump’s personal, family and corporate interests. The outcome was consequently an accountability vote with two connected elements: a demand to restrain presidential power and a demand for economic delivery. Concentrating only on the first would be a serious mistake.
Congressional investigations into corruption, conflicts of interest and executive abuses are indispensable. But if Democrats define their victory primarily as an authorization to investigate Trump, they may constrain one president without weakening Trumpism. Investigations can expose abuses; they cannot make housing affordable, create career-building employment, rebuild declining regions or give working people greater influence over technological and economic change.The midterms should therefore be interpreted neither as a final defeat for American populism nor merely as a temporary anti-incumbent swing. They represent a narrow but historic window in which democratic forces can move from anti-Trump resistance to democratic reconstruction.
Whether this opening becomes a lasting realignment will depend on what Democrats do with their new institutional power. If they combine constitutional accountability with a credible programme addressing affordability, inequality, good jobs, regional decline and technological disruption, the election may become the starting point of a more durable democratic counterwave. If they return to technocratic incrementalism or assume that Trump’s personal unpopularity has solved the problem, the same electorate may swing back in 2028.
The central lesson is therefore not that American populism has been defeated. It is that Trump has become electorally vulnerable because he failed to deliver on the grievances that originally brought him back to power. Those grievances remain politically available. The question is now whether democratic government can finally address them before another authoritarian populist does.
Daron Acemoglu is right to warn that the most difficult work begins after the electoral victory. As he argues in What Happened to Liberal Democracy?, liberal democracy prospered when it was associated with shared prosperity, political voice, social mobility and the broad distribution of opportunity. It entered crisis when liberalism detached from these social foundations and became increasingly associated with technocracy, globalization, and the priorities of highly educated metropolitan elites.
If Democrats cannot respond to extreme inequality, the affordability crisis and the disappearance of secure, career-building employment—especially for workers without university degrees—the political pendulum may swing back in 2028. Neither an exclusive reliance on taxes and transfers, nor centrist attachment to the pre-Trump status quo, nor the fashionable expectation that AI-driven “abundance” will automatically resolve distributive conflict offers an adequate response.
This is precisely why the American midterm result deserves greater attention than a conventional anti-incumbent election. It creates an institutional barrier against Trump’s authoritarian ambitions, but it also places Democrats under an obligation to demonstrate that pluralist democracy can govern and deliver. If they use their congressional majority mainly to investigate Trump while failing to articulate a credible economic and social program, they may constrain him temporarily while inadvertently preparing the next Trump—or a younger, more capable successor.
In my ECPS commentary “Trump and the New Capitalism: Old Wine in New Bottle,” I argued that Trumpism 2.0 represents more than nationalist rhetoric or protectionist trade policy. It combines economic nationalism, corporate oligarchy, technological concentration and elements of digital feudalism. State power is not withdrawn from the economy; it is reorganized to serve politically connected corporations, dominant technology platforms and favored economic interests. The 2026 vote has interrupted this project, but it has not dismantled the political economy that sustains it.
The American result forms part of a wider sequence of authoritarian-populist reversals. In Hungary, the Tisza Party ended Viktor Orbán’s sixteen-year rule and secured a constitutional supermajority. According to the detailed 2026 Hungarian election analysis published by the Institut für Europäische Politik, Tisza won 53.29 percent of party-list votes and 138 of the National Assembly’s 199 seats.
In Serbia, the student-backed opposition movement that emerged from protests following the Novi Sad railway-station disaster defeated Aleksandar Vučić’s ruling alliance. Reuters reported that the movement received 52.7 percent of the vote and secured 139 of the 250 parliamentary seats.
In Brazil, Luiz Inácio Lula da Silva defeated Flávio Bolsonaro, although the narrow margin confirmed that Bolsonarismo remains deeply embedded in Brazilian political and social life. As Professor James N. Green warned in an ECPS interview conducted after the election, the Brazilian far right has lost a battle, not the wider political struggle. It retains conservative congressional support, religious networks, digital mobilization capacity and a substantial electorate.
Israel provides a more qualified case. Benjamin Netanyahu’s nationalist-religious bloc won only 53 of the Knesset’s 120 seats, but the process of forming a government remains unresolved. Netanyahu’s parliamentary position has been severely weakened, but it would be premature to describe this as a completed transfer of power.
Taken together, these developments justify speaking cautiously of a democratic counterwave. They show that elections, civic mobilization, coordinated opposition and institutional resistance can still constrain leaders who appeared politically invincible. But they do not demonstrate that authoritarian populism has been ideologically defeated.
In “Populist Attacks on Institutions as a Reaction to Hyper-globalization,” I argued that populist attacks on independent institutions cannot be understood separately from the economic and social dislocations produced by unmanaged globalization. Financial crises, regional decline, inequality, declining social mobility, and the perception that national governments have lost control over economic outcomes generate both demand for populism and the political opportunities populist entrepreneurs exploit.
This argument is consistent with Dani Rodrik’s research on the relationship between globalization and right-wing populism, and with Sergei Guriev and Elias Papaioannou’s extensive study of the political economy of populism. Economic shocks do not translate mechanically into populist politics. They operate through perceptions of status, cultural displacement, political exclusion, and the failure of representative institutions. In “Capitalist Disruptions and the Democratic Retreat: A US–EU–China Comparison,” I developed this argument further by describing a process of authoritarian convergence. Liberal democracies and explicitly authoritarian systems remain different, but widening inequality, technological surveillance, corporate concentration, regulatory capture, and weakened public institutions are narrowing parts of the practical distance between them.The result is a political paradox. Governments remain formally democratic, but citizens increasingly experience economic decisions as matters over which they exercise little meaningful influence. Elections continue, but changing the government does not necessarily alter the underlying distribution of economic power.
The political damage was compounded by the way globalization was governed. Trade integration generated large aggregate gains, but governments too often treated the workers, firms and regions bearing the adjustment costs as if they would automatically move into new and better employment. Autor, Dorn and Hanson’s research on the China shock found that import-exposed local labor markets experienced persistent falls in employment, wages and labor-force participation, while their later work linked greater trade exposure to political polarization. The OECD Employment Outlook 2026 reaches a similar conclusion across advanced economies: the benefits of openness were real, but the losses were geographically concentrated and often endured for years. The resulting backlash was therefore not simply an irrational rejection of trade. It was also a reaction to governments that liberalized markets without constructing adequate mechanisms for regional renewal, worker adjustment, social insurance and political voice.
China’s current growth model has intensified this distributive problem. China is neither the sole cause of Western deindustrialization nor merely an economic threat; its growth has enlarged world trade and accelerated the diffusion of affordable green technologies. Yet weak domestic consumption, state-directed credit, large industrial subsidies, and manufacturing overinvestment now create asymmetric competitive pressure that open market economies cannot ignore. The IMF’s 2025 Article IV consultation warns that export-led adjustment and unwarranted industrial-policy support are producing excess supply and adverse spillovers for trading partners, while the European Commission has documented extensive state-induced distortions and unfair subsidization in strategic sectors. The democratic answer cannot be indiscriminate protectionism, which would raise prices and deepen fragmentation. But passivity would accelerate industrial erosion and feed populist claims that elected governments have surrendered control. A credible response requires rules-based trade defense, reciprocity in market access, coordinated industrial and competition policy, place-based investment and pressure for China to rebalance towards domestic consumption rather than exporting its internal imbalances.
Yet such pressure will be ineffective if exercised through a fragmented, transactional multipolar order in which major powers rely on unilateral tariffs and competing economic blocs. Bringing China closer to fair play requires rebuilding an open, inclusive and enforceable multilateral order, supported by reformed WTO rules on industrial subsidies, state-owned enterprises, excess capacity and reciprocal market access. Trump’s electoral defeat should therefore be understood not only as a setback for authoritarian populism, but also as a strategic opportunity to move beyond unilateral protectionism and toward renewed multilateral order and cooperation. If democratic governments use this opening to construct a fairer international system that reconciles openness with social protection, industrial resilience and democratic accountability, they may simultaneously address China’s distortive practices and the domestic grievances on which Trumpism and related populist movements thrive.
Under these conditions, authoritarian populism becomes a distorted form of democratic protest. Citizens support leaders who promise to recover sovereignty and political control, even when those leaders subsequently use that mandate to dismantle the institutions that make democratic correction possible.
Why Some Populists Lose—and Others Survive Failure
The emerging counterwave supports a first proposition: where electoral competition remains meaningful, authoritarian populists who govern badly may eventually be punished. Populists promise that concentrating authority will enable them to break institutional deadlock and deliver rapid results. Once in office, however, many generate corruption, patronage, inflation, declining services, administrative incompetence, and international isolation. When the discrepancy between rhetoric and performance becomes sufficiently visible, even formerly loyal voters may abandon them.
But this mechanism operates only where opposition forces can organize, voters can obtain independent information, and electoral authorities, courts, and security institutions have not been completely subordinated.My comparative study “Confronting Populist Authoritarians: The Dynamics of Lula’s Success in Brazil and Erdogan’s Survival in Turkey” demonstrated why similar economic and political failures can produce different outcomes. Lula’s broad democratic coalition defeated Bolsonaro, though it could not eliminate Bolsonarismo. In Turkey, Erdogan’s institutional capture, control over resources and capacity to fragment the opposition insulated him from the consequences of economic failure.
This leads to a second and more troubling proposition: where a populist leader has captured the state, failure may produce intensified authoritarianism rather than electoral defeat. In “A Lesson from Turkey: Economic Crises as Steppingstones, but Not Exit Routes for Authoritarian Populists,” I argued that economic crises may help populists enter power without subsequently providing an exit route from populist rule. Once leaders have captured the judiciary, media, bureaucracy, security apparatus, and mechanisms for distributing state resources, poor economic performance ceases to be sufficient to remove them.
Leaders who fear prosecution, loss of wealth or exposure of wrongdoing acquire powerful personal incentives to prevent alternation in power. The more offenses committed in consolidating the regime, the more dangerous surrendering office becomes. The regime’s failures therefore deepen its dependence on repression.Turkey illustrates this danger. Freedom House’s 2026 assessment documents the consolidation of power through constitutional engineering, institutional capture and the imprisonment of opponents, journalists and civil-society representatives.
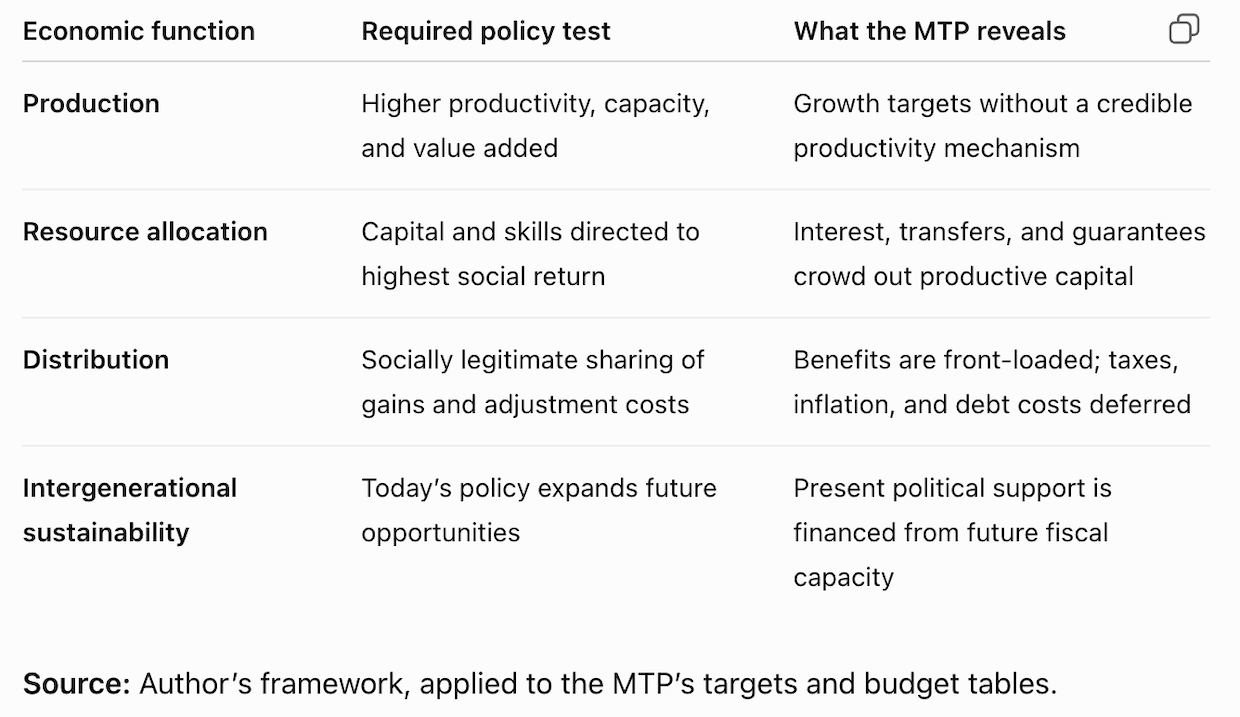
My more recent analysis, “Stealing from the Future,” shows how such a regime may use fiscal transfers, public procurement, credit and inflation to purchase present political support by transferring the costs to future taxpayers. Economic policy becomes a technology of political survival rather than an instrument of long-term development. Consequently, no mechanical sequence in which the defeats of Trump, Orbán, Bolsonaro or Vučić necessarily predict the fall of Erdogan or Narendra Modi. Democratic openings can spread confidence, but national outcomes depend on the depth of institutional capture, the credibility of opposition forces and whether electoral punishment remains possible.
The Acemoglu Challenge: Redirecting Technological Change
The struggle over artificial intelligence will be critical to whether the American midterm victory develops into a durable democratic realignment. An ECPS long read, “The Economist versus Acemoglu: Who Will Govern the Next World Order?”, argues that the controversy surrounding Acemoglu is not simply a dispute over AI productivity. It concerns who directs technological change, who captures its gains, and whether democracy can discipline concentrations of corporate power that markets have themselves created. Acemoglu, David Autor and Simon Johnson’s proposal for “Building Pro-Worker AI” distinguishes technologies that complement workers and create new human tasks from technologies principally designed to replace labor. Acemoglu’s related intervention in Nature warns against organizing the entire technological agenda around artificial general intelligence and the automation of human capabilities.
If AI intensifies workplace surveillance, displaces labor and concentrates income among a few technology companies, it will aggravate precisely the inequalities and insecurities that nourish authoritarian populism. A democratic strategy must instead use public procurement, research funding, competition policy, worker participation and taxation to redirect innovation toward augmenting human capabilities and creating socially valuable employment.This is where the political meaning of Trump’s midterm defeat will ultimately be determined.
Congressional investigations and institutional checks are necessary, but they cannot substitute for a new governing philosophy centered on productive employment, affordable housing and healthcare, regional regeneration, technological democracy and the reconstruction of worker power.
After Victory Comes Democratic Delivery
Democratic successors must restore legality without producing institutional paralysis. They must dismantle state capture without replacing it with partisan revenge. They must defend pluralism while demonstrating that pluralist democracy can govern, coordinate and deliver. The current electoral reversals are therefore openings rather than conclusions. The V-Dem Democracy Report 2026 finds that nearly three-quarters of the world’s population lives under autocratic rule and that democracy, for the average global citizen, has returned approximately to its 1978 level. Only eighteen countries are currently democratizing, while nearly a quarter of the world’s states are undergoing autocratization.
The American midterm victory is therefore historic, but its meaning remains unsettled. It may mark the beginning of democratic reconstruction. Equally, it may be another swing of the electoral pendulum, driven by an electorate that remains economically insecure, politically unrepresented, and willing to experiment repeatedly with anti-establishment alternatives.
If democratic governments cannot address these structural grievances, authoritarian populism will return—perhaps under younger, more disciplined and more competent leaders who have learned from the failures of Trump, Orbán and Bolsonaro. Winning an election can remove or constrain an authoritarian government. Only democratic delivery can weaken the economic, institutional and cultural conditions that continually reproduce authoritarian populism.
In this commentary, Professor Ibrahim Ozturk examines Turkey’s 2026 investment-fund crisis as a manifestation of the political economy of populist authoritarian rule under President Recep Tayyip Erdogan. He argues that the scandal reflects not merely financial misconduct but the cumulative consequences of personalized power, weakened regulatory independence, and politically mediated economic privileges. Drawing on institutional indicators, monetary-policy developments, and the networks connecting political elites, financial regulators, and market actors, Professor Ozturk demonstrates how populist appeals to sovereignty legitimize selective economic protection while ordinary investors bear disproportionate losses. He contends that lasting recovery requires more than financial stabilization or individual prosecutions: it demands institutional reconstruction, independent oversight, transparency, and effective constitutional constraints on presidential authority.
Turkey’s 2026 investment-fund crisis is a structurally generated, unavoidable outcome of the autocratic regime Erdogan has constructed. The presidential system introduced in 2018 consolidated personalized authority, weakened institutional checks, and subordinated professional judgment to political dependence. Discretionary monetary policy and compromised financial oversight share an allocation logic: access and protection are selective, while losses fall on households and public balance sheets. Populist claims of sovereignty legitimize this arrangement; restrictions on journalism, opposition, and independent scrutiny obstruct its correction. The crisis therefore belongs to a cumulative history of weakened accountability and opportunities for rent extraction. Lasting recovery requires changing the institutions that reproduce these outcomes, which is unlikely under Erdogan’s preferred architecture for regime overhaul.
Populism, Selective State Capacity, and Regime Reproduction
Turkey’s September 2026 fund crisis should be understood as a manifestation of Erdogan’s political-economic order. Its significance extends beyond market participants’ misconduct to the deliberate weakening of institutions that can constrain them. Building on my earlier ECPS work, this commentary argues that recurrent financial crises are endogenous to a regime that concentrates appointment powers, distributes protection selectively and restricts independent challenge. The exact timing of a collapse is contingent; the repeated production of risk and unequal loss is a foreseeable consequence of these institutional choices.
Mudde’s account defines populism through a moral opposition between a virtuous people and a corrupt elite. In office, those who claim to embody the popular will can delegitimize courts, regulators, and professional dissent as obstacles to the national mandate. Under Erdogan, this justificatory language accompanies a governing structure in which loyalty increasingly substitutes for independent judgment. Populism supplies the legitimacy claim; authoritarian institutional reorganization supplies the means of overriding constraints.
Dornbusch and Edwards identify a macroeconomic cycle in which expansionary promises discount inflation and external financing constraints, eventually imposing adjustment costs on intended beneficiaries. Turkey adds a distributional dimension: politically mediated credit, asset ownership and access to protection favour already advantaged groups. Rodrik’s distinction between political and economic populism helps separate legitimate challenges to entrenched privilege from the removal of safeguards against executive predation.
The causal mechanism operates through appointments, incentives and information. Political dependence weakens oversight; privileged access enables selective gains; public intervention can displace losses onto less-protected groups. Restricting scrutiny then lowers the likelihood of correction and permits repetition. Cross-country evidence links populist leadership to institutional erosion and lower long-run income; the Turkish case identifies the channels through which that broader association becomes a governing practice.
This situation reflects a selective state capacity rather than a uniformly weak state: substantial power to mobilize credit, reorganize institutions, and discipline critics coexists with weakened independent capacity to restrain connected interests. My 2022 ECPS analysis traced Turkey’s economic deterioration to the reversal of reforms and the subordination of expertise. The fund scandal extends that diagnosis from macroeconomic management to financial-market governance.
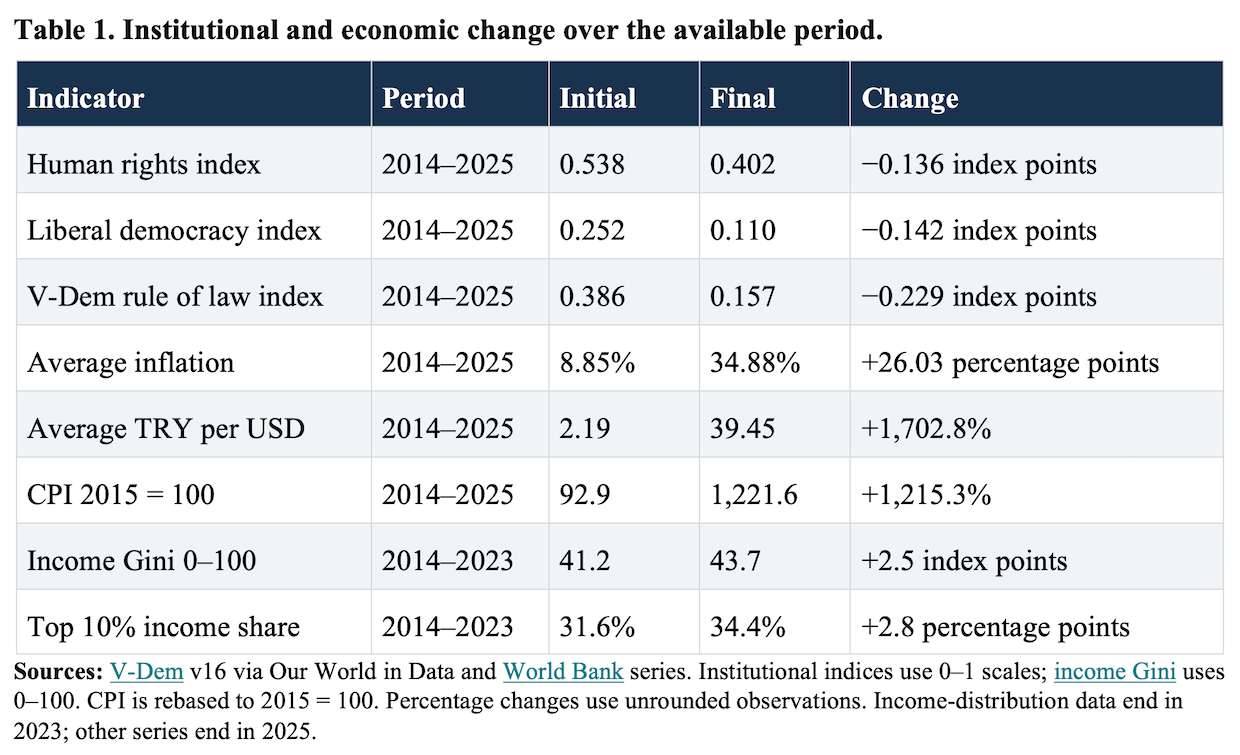
For instance, the broader institutional trajectory, central to the current crisis conundrum, predates the ongoing monetary experiments and the financial sector more broadly. Between 2014 and 2025, V-Dem’s central estimates fell from 0.538 to 0.402 for human rights, from 0.252 to 0.110 for liberal democracy, and from 0.386 to 0.157 for the rule of law. The sharpest declines occurred in 2016–2017; when the highly controversial coup attempt took place, later improvements did not restore earlier levels. Table 1 juxtaposes this deterioration with currency depreciation, accumulated inflation and increased income concentration. The indices describe institutional conditions rather than individual culpability.
From Institutional Reform to the Erosion of Accountability
The 2000–2001 crisis provides an institutional baseline for comparison. Fiscal fragility, public-bank losses and weak banking discipline exposed vulnerabilities that political confrontation triggered. Banking restructuring, stronger supervision and a floating exchange rate subsequently supported recovery under an IMF, World Bank and EU membership-reform framework. The AKP, the current government party, initially benefited from this inherited trajectory. Its later dismantling matters precisely because institutional credibility and international engagement had demonstrated their economic value.
The December 2013 deep successive corruption scandals and investigations, which brought allegations of extensive bribery, illicit gold trading and abuse of public office involving high-profile ministers in Erdogan’s inner circle into public view, also raised broader questions about ruling-party parliamentarians and businessmen allegedly awarded tailor-made public contracts in exchange for financial and political favors sought by Erdogan himself. The subsequent response marked a critical rupture in accountability: despite the gravity of the allegations, Parliament declined to refer four former ministers for trial, closing the route to judicial examination that referral would have opened. The US conviction of Mehmet Hakan Atilla, who served as deputy general manager of the state-owned Halkbank, and the guilty plea of Reza Zarrab, who was a gold trader central to the December 2013 allegations, subsequently established sanctions-evasion offenses in a separate jurisdiction. Although legally distinct, these cases illuminate a connected political-economic mechanism: shielding politically connected actors from independent scrutiny weakens deterrence and entrenches expectations of protection. Impunity becomes cumulative when accountability failures incentivize subsequent abuses.
The 2018 confrontation with Donald Trump’s administration exposed the limits of performed sovereignty to be used as a decisive element in domestic populist politics. In August 2018, US sanctions over the detention of Andrew Brunson, an American pastor held in Turkey on terrorism-related charges that Washington rejected as unfounded, escalated the diplomatic confrontation. Trump’s subsequent 50 percent tariff on Turkish steel, which doubled the existing 25 percent duty and sharply increased the barriers facing Turkish exporters in the US market, added trade pressure to the dispute. These measures aggravated an economy already vulnerable to dependence on external financing and currency mismatches, as the IMF’s assessment documented. The confrontation thus exposed the material limits of sovereignty rhetoric in an economy dependent on international capital and export markets. As a result, depreciation increased import costs and foreign-currency debt burdens.
The CBRT responded by raising its policy rate from 17.75 to 24 percent. The problem was the durability of stabilization when presidential authority could subsequently displace its institutional basis. Reserve depletion followed a separate policy choice. Reuters reported approximately US$128 billion in dollar sales by state banks over the preceding two years in May 2021; the IMF identified inadequate buffers and negative net reserves after swaps. Obviously, dollar sales against lira do not prove the entire sum was stolen, but they highlight limited public capacity and insufficient transparency about transactions and beneficiaries. Defending a politically preferred exchange-rate path consumed resources while postponing acknowledgment of underlying constraints.
Discretionary Easing, Selective protection, and Costly Stabilization
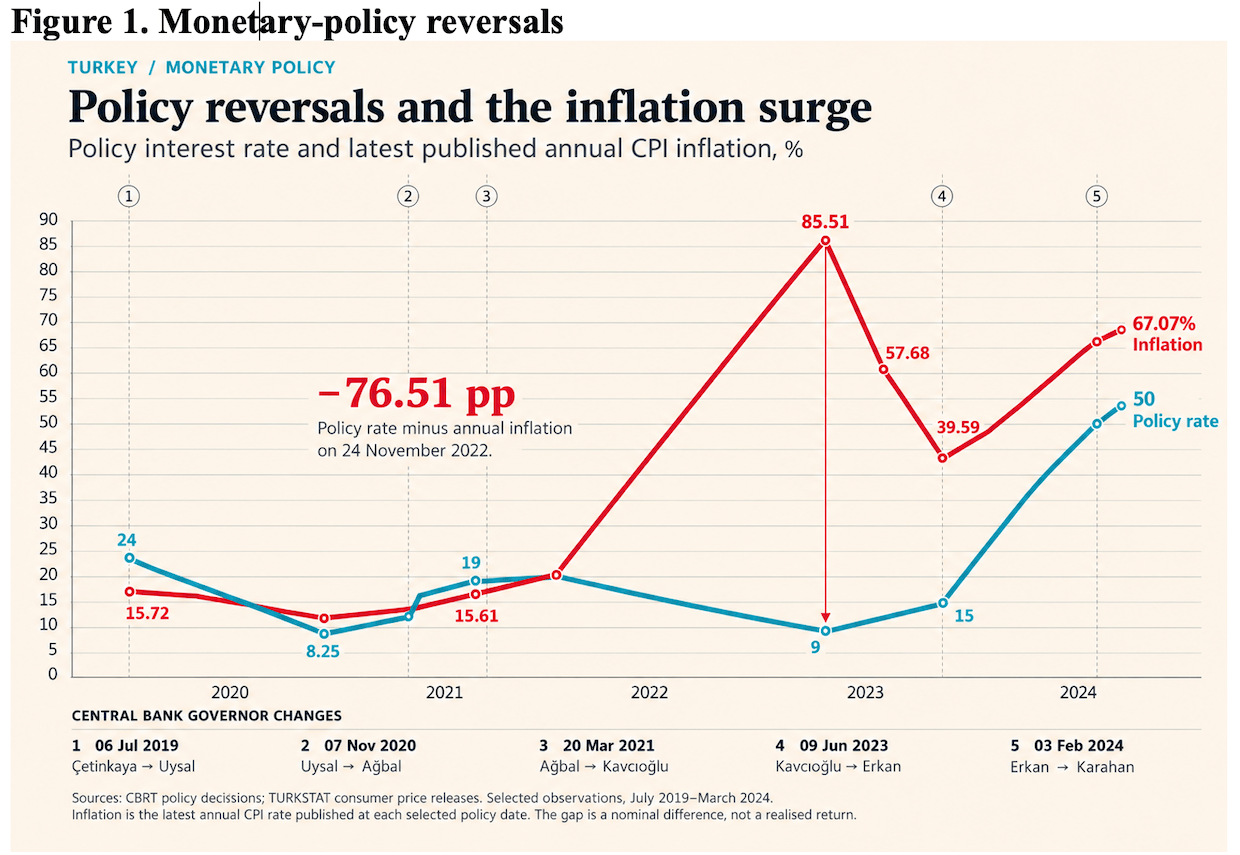
Political intervention weakened institutional capacity by subordinating professional judgment to presidential preferences. Figure 1 connects successive monetary-policy reversals to the executive’s appointment and removal powers. Following Murat Cetinkaya’s dismissal in July 2019, the policy rate fell from 24 to 8.25 percent under Murat Uysal. Naci Agbal later reversed course, raising it to 19 percent in March 2021, but was dismissed two days after his final increase. His removal showed how vulnerable professional tenure is when monetary decisions conflict with presidential preferences.
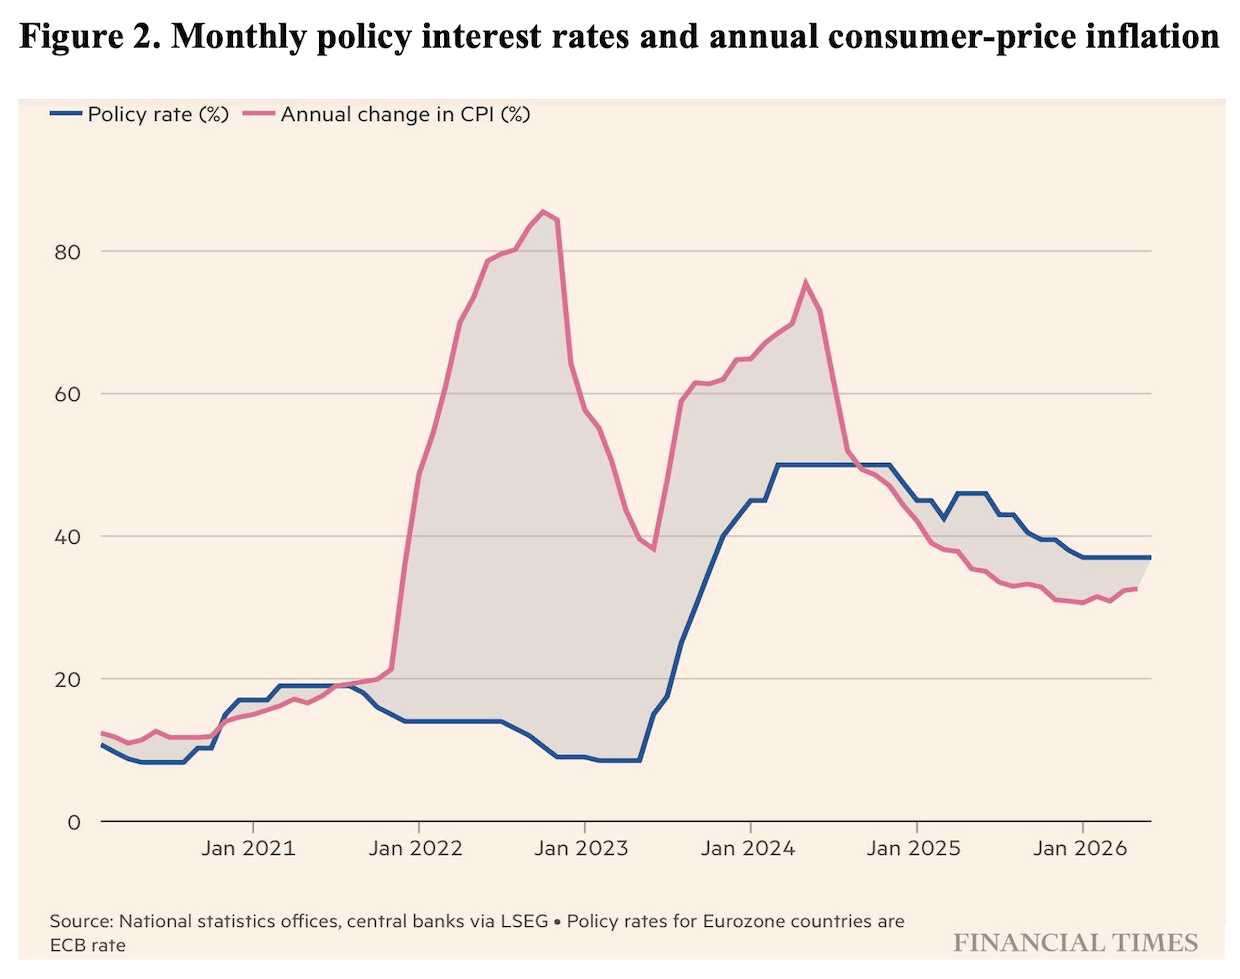
Under Sahap Kavcioglu, politically imposed easing reduced the policy rate from 19 percent in September 2021 to 8.5 percent by February 2023. At the November 2022 decision, the rate stood 76.51 percentage points below the latest published annual inflation rate. This nominal gap, rather than a realized return, captures the divergence between monetary policy and prevailing inflation. Cheap lira financing encouraged foreign-currency and asset purchases, contributing to depreciation while offering asset-owning borrowers protections unavailable to wage earners and unhedged savers.
Erdogan legitimized easing by shifting appeals from rhetoric about “sovereignty” and “external enemies” to religious authority. Invoking nas—a binding Islamic injunction—against usury (riba), he framed lower interest rates not only as a religious obligation, but also asserted that interest causes inflation, not vice versa. This shift between nationalist and religious justifications illustrates populism’s adaptability: both appeals shield discretionary authority from scrutiny while society absorbs the costs.
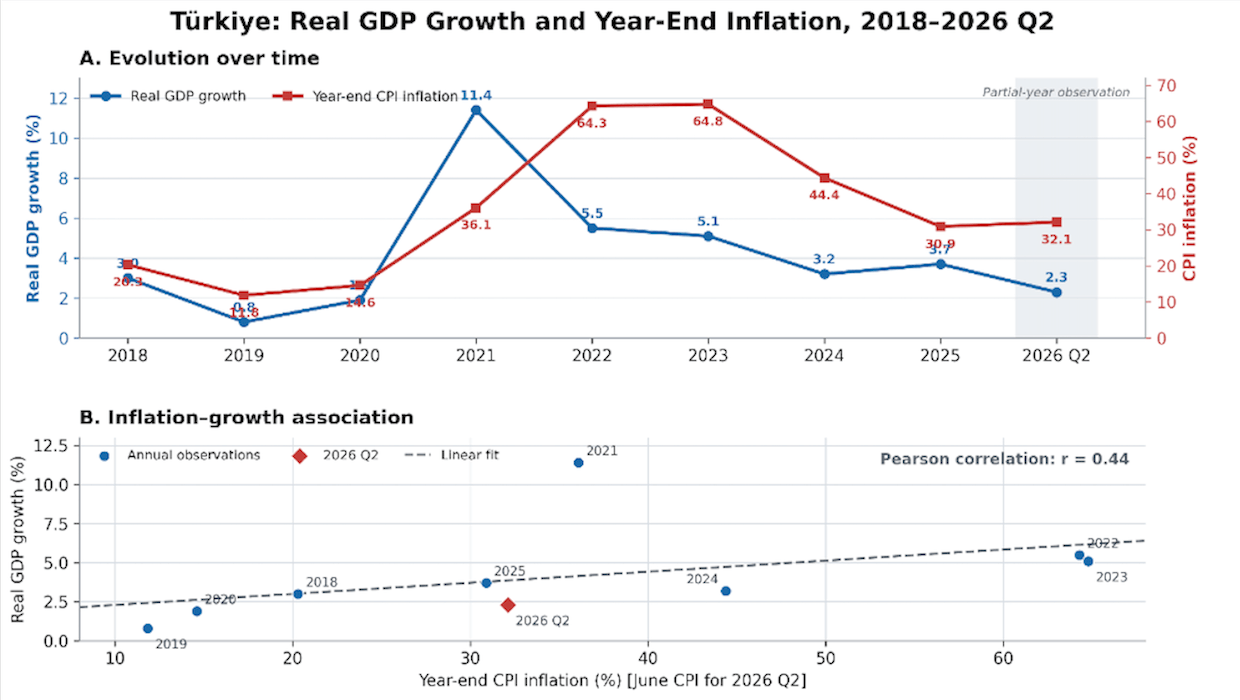
After the 2023 elections, tightening under Hafize Gaye Erkan and Fatih Karahan raised the rate to 50 percent by March 2024; by year-end, it exceeded annual CPI inflation. Figure 2 shows the successive burdens of inflationary erosion and costly stabilization. Inflation initially accelerated despite tightening as depreciation, tax and administered-price increases, wage adjustments and expectations interacted with delayed monetary transmission. This coexistence does not establish that higher rates caused the preceding crisis. More fundamentally, technocratic correction restored a conventional instrument without constraining the executive powers that had enabled its subordination.
Exchange-rate-protected deposits (known as Kur Korumalı Mevduat-KKM) introduced in December 2021 shifted some depreciation risk onto the Treasury and Central Bank balance sheets. Participating savers received publicly underwritten protection unavailable to households without qualifying deposits. Successive policy shifts thus created different opportunities for protection through cheap credit, asset appreciation, KKM guarantees and later high nominal deposit returns. Credit-constrained households and firms instead faced purchasing-power losses, expensive working capital and weaker demand. Establishing that the same connected actors benefited throughout requires linked transaction records; the structural mechanism is the repeated redistribution of gains and losses through discretionary policy.
Distributional indicators reveal unequal capacities to absorb these shocks. The World Bank income Gini rose from 41.2 in 2014 to 43.7 in 2023, while UBS reports a separate wealth Gini of 0.73 for 2025, placing Turkey tenth among covered markets. The OECD Employment Outlook 2026 reports approximately 79 percent growth in CPI-deflated business-sector hourly wages between early 2021 and early 2026, alongside a falling minimum-to-median wage ratio and declining real minimum wages by April 2026. Average wage recovery therefore coexisted with uneven gains; it neither measures median household income nor resolves concerns about the official inflation deflator.
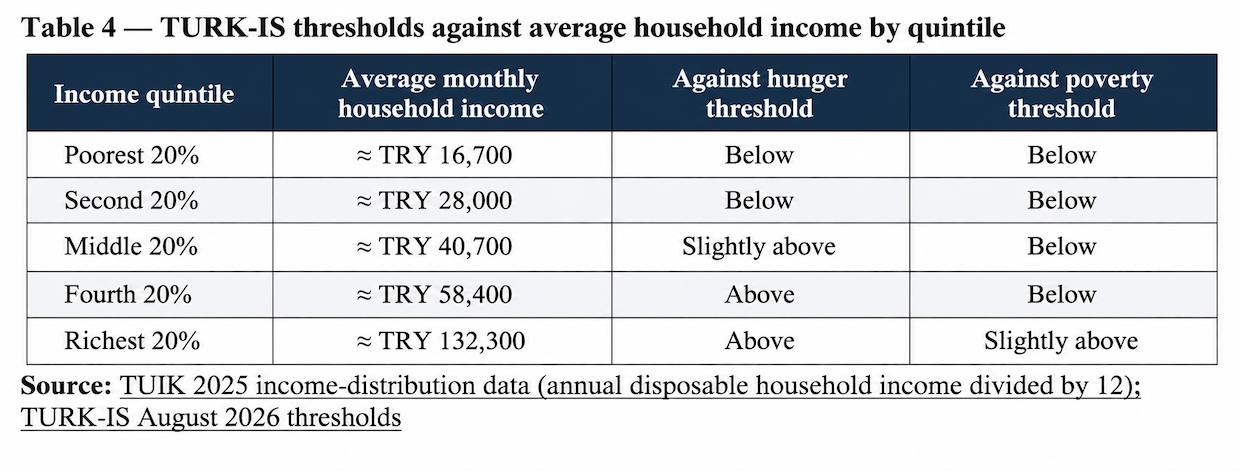
TURK-IS’s November 2025 estimates make this insecurity concrete: the net minimum wage covered only 74.1 percent of a four-person household’s food budget and 57 percent of a single worker’s estimated living costs. These adequacy benchmarks, rather than official poverty rates, demonstrate low-paid workers’ exposure to essential expenses. Limited public provision compounds that exposure. Turkey ranks near the bottom of the OECD’s social-spending comparison, while health expenditure amounted to 4.7 percent of GDP against an OECD average of 9.3 percent. These overlapping measures highlight the opportunity costs of financial guarantees when public services remain comparatively underfunded.
Although the IMF acknowledged that post-2023 tightening reduced crisis risks, changing the monetary instrument leaves politically mediated allocation intact. Recovery must therefore be assessed through investment, distribution and public capacity alongside disinflation.
Persistent price increases also undermine planning. Compounding official inflation rates shows that prices increased approximately 432 percent between end-2020 and end-2024; subsequent disinflation did not reverse that accumulation. Over the longer period, annual-average inflation rose from 8.85 percent in 2014 to 34.88 percent in 2025, while the exchange rate moved from TRY2.19 to TRY39.45 per dollar. The annual-average CPI implies that a fixed nominal lira amount retained only approximately 7.6 percent of its 2014 purchasing power.
Supply and demand continue to operate, but unstable money obscures relative prices and sustainable margins. Firms may postpone productive investment while households seek exceptional nominal returns to recover earlier losses. The resulting demand for financial protection becomes an opportunity for extraction where independent oversight, reliable information, and enforceable investor rights are weak.
The Fund Fraud: Distorted Price Discovery, the Demand for Financial Protection
The fund crisis follows from the interaction of these conditions. Monetary instability creates demand for protection; concentrated portfolios amplify valuation risk; politically dependent oversight weakens correction. The scandal is therefore part of the regime’s cumulative political economy, not an isolated accident outside it. Institutional responsibility rests on the deliberate construction and maintenance of this incentive structure; individual criminal responsibility still depends on evidence of particular acts.
The crisis emerged after explicit warnings, not in the absence of information. On 4 November 2025, Finance Minister Mehmet Simsek publicly acknowledged manipulation through certain investment funds and promised stronger regulation. MSCI’s June 2026 review subsequently flagged possible coordinated trading and artificially inflated free-float estimates. S&P Dow Jones Indices warned in July about transparency and market-classification risks, while FTSE Russell also raised concerns over transparency and market accessibility. This accumulation of domestic acknowledgment and external warnings shifts the accountability question from whether authorities knew to why their response failed to contain the risks. Early evidence points to political protection or interference obstructing effective intervention, requiring an independent examination of supervisory correspondence and decision records.
After mounting external pressure that, unless decisive corrective measures are taken, Turkey could be isolated from emerging market status, the Capital Markets Board (SPK) placed in September 131 funds associated with seven portfolio-management companies into liquidation, with 455,758 unique investors subsequently identified. Reuters reported affected assets exceeding US$18 billion and a weekly equity-index decline of more than 8 percent. These figures show the scale of exposure and disruption, not the amount stolen or final investor losses.
Other indicators show how stress spread beyond the affected funds. A press compilation of Central Securities Depository data recorded a fall in listed-equity capitalization from TRY22.91 trillion at end-August to TRY19.08 trillion in late September, approximately 16.7 percent. Reporting based on TEFAS data identified net fund outflows exceeding TRY210 billion after August 28. Meanwhile, net purchases through Ziraat Yatirim reportedly reached TRY22.3 billion on September 21, while gross central-bank reserves fell by US$13.8 billion between August 28 and September 18. Valuation changes, withdrawals, brokerage transactions and reserve movements measure different phenomena. They cannot be added into a single damage estimate or attributed entirely to the crisis. Purchases through a publicly owned intermediary also do not establish public expenditure without identifying the underlying accounts.
Valuation Feedback, Liquidity Risk, and Delayed Intervention
In the emerging Ponzi-like scheme, the financial mechanism combines valuation feedback with liquidity risk. Concentrated purchases of thinly traded low-free-float shares can raise quoted prices and reported fund values. Strong apparent performance attracts subscriptions that finance further purchases; higher collateral valuations may also support additional borrowing. Where related parties control funds and portfolio companies, investors’ interests may conflict with the wider group’s financing objectives.
This cycle can widen the gap between quoted prices and realizable portfolio value. Redemption pressure exposes the discrepancy, while sales of liquid holdings transmit stress to other securities. The Financial Stability Board recognizes liquidity mismatch as a general vulnerability of open-ended funds. Turkey’s distinctive problem is whether its institutions could identify and constrain the accumulation of these risks independently of commercial and political pressures.
However, the principal–agent problem in Turkey extends beyond fund management, underlining a broader systemic characteristic. Investors entrust managers with assets; citizens entrust regulators with protection. When the political executive controls supervisory appointments, agents may be incentivized to satisfy influential networks rather than their public mandate. Preferential access and weak sanctions then lower the expected cost of risk-taking and extraction. The formal existence of a regulator is insufficient when its effective independence has been subordinated.
The SPK’s September 18 statement acknowledged abnormal fund-driven movements in low-free-float shares during the final quarter of 2025. The Financial Stability Committee considered the issue on December 2; a working group followed on December 3; the qualified-investor threshold increased on December 18. Comprehensive guide changes came on August 28, 2026. The interval makes supervisory responsibility unavoidable: administrative activity cannot establish that known exposures were adequately constrained or that continuing investors were protected.
The Principal–Agent Problem: Information Asymmetry, Conflicts of Interest and Institutional Protection
The fund crisis exposes a chain of delegated authority: investors entrust assets to managers, citizens entrust protection to regulators, and the executive appoints supervisors. Managers know more than investors; officials control records unavailable to citizens. Under Erdogan’s personalized appointment system, these information asymmetries intersect with political dependence. As a result, the resulting vulnerability is endogenous to the governing architecture: institutions expected to constrain accumulation can instead protect its beneficiaries.
Figure 3 connects ownership, management and inspection within a shared appointment network. Erdogan’s Turkey Wealth Fund chairmanship, Erisah Arican’s overlapping leadership, Mahmut Kayacik’s TVF–Takasbank responsibilities and Yunus Arinci’s move from the State Supervisory Council to Takasbank weaken institutional separation. Salih Tanrikulu’s former Borsa Istanbul role adds retrospective self-review risk. The principal–agent problem becomes acute when citizens’ monitors answer to the political network whose decisions require investigation.
Figure 4 examines delegated stewardship through Kilimci’s Tera roles, Çakmak’s management of insurance and pension assets, and Şener’s separate Interbank Card Center procurement (BKM) proceedings. The latest developments sharpen Çakmak’s conflict-of-interest dimension: after resigning on 15 October, he was remanded in custody on 24 October. Reported allegations include receiving US$1 million in cash for directing institutional resources into Tera funds; further reporting describes personal share transactions tied to institutional placements. His reported repayment of investment-related proceeds neither establishes the amount misappropriated nor resolves responsibility.
Iskender Balci, son of former banking regulator Mustafa Balci and son-in-law of Deputy Finance Minister Osman Celik, held company oversight roles at Ozata Denizcilik and DOF Robotik before his detention. Celik submitted his retirement request on October 19. Administrative departure leaves the central question unresolved: whether licensing, appointments and supervision were insulated from family interests through disclosure and recusal.
The Sayan family illustrates institutional mobility across politics, regulation and diplomacy. Ramazan Sayan, described in contemporary reporting as Erdogan’s longstanding associate, is the father of four siblings. Fatma Betul Sayan Kaya progressed through advisory work, Parliament, cabinet and party leadership. Omer Fatih Sayan moved through Prime Ministry advisory posts, BTK leadership, a deputy ministership and Turk Telekom board leadership before joining EPDK. Ayse Hilal Sayan Koytak advanced through ministerial and diplomatic appointments, including ambassadorships in Kuwait, Bahrain and Finland; Nazmiye Sumeyye Sayan served on Istanbul’s metropolitan council. Together, these trajectories warrant scrutiny of merit, access and appointment criteria.
The financial question is more specific. Reuters reported allegations concerning approximately TRY2.17 billion in combined share-sale proceeds received by Sayan Kaya and her husband before the turmoil. Whether Takasbank-supported liquidity facilitated their exits requires transaction-level evidence. Sale proceeds cannot be treated as profits, and institutional liquidity support alone does not establish preferential treatment.
Mustafa Yazici, son of senior AKP official and former minister Hayati Yazici, introduces distressed-debt collection into this network. The imposition and subsequent lifting of asset restrictions require transparent explanation. His company, Adil Varlik Yönetim, purchases non-performing receivables. Corporate records document a TRY450 million conversion of shareholder receivables into capital, but not their ultimate funding source. A TRY500 million financing bill arranged by Tera Yatirim subsequently generated an MKK non-payment notice. The intersection of connected financing and debt collection merits investigation; borrower complaints alone do not establish unlawful interest charges.
BTK belongs within the accountability analysis because restrictions on online reporting deepen information asymmetry. Reported blocking concerning Batuhan Mumcu and his wife requires examination of judicial orders, requests and implementation. Mumcu joined BTK’s board in August 2026; his wife, Neslihan Mumcu, appears in corporate disclosures concerning Bulls Yatırım Holding. Some reported restrictions predated his appointment; attributing them to his personal intervention would require additional evidence.
Figure 6 places SPK at the center. Ibrahim Omer Gonul, son of former Defense Minister Vecdi Gonul, moved from SPK chairmanship to KGK before being removed on October 20 alongside SPK chair Mahmut Sutcu. Sutcu had submitted his resignation the previous day. Tezmen’s former MKK role and Murat Onuk’s overlapping portfolio-management and Takasbank responsibilities further complicate independent oversight. Personnel changes leave earlier decisions and the executive’s appointment powers requiring scrutiny.
Reports that two SPK officials opposed Tera Yatirim’s flotation, were subsequently replaced, and that the reconstituted board approved the IPO two months later reveal how presidential appointment power can override institutional resistance. In Erdogan’s centralized system, replacing officials changes more than personnel: it reshapes the boundaries of permissible professional judgment. The sequence illustrates a principal–agent inversion in which regulators become accountable upwards to the appointing authority rather than outwards to investors and the public. Repeated failures to investigate politically protected conduct reinforce expectations of impunity, weaken deterrence, and make compliance with political preferences less costly than resistance. Subsequent dismissals cannot resolve this institutional responsibility: accountability must reach the authority that selected supervisors, enabled contested approvals and sustained the system of protection.
An inquiry must follow beneficial ownership and funding at entry; concentration, related-party transactions and valuation during investment; and information, financing and redemption terms at exit. Early withdrawal alone proves no insider dealing, but withdrawals above realizable asset values can shift shortfalls to remaining investors. Appointment records, supervisory correspondence, access logs and transaction trails are therefore indispensable.
In terms of an ex-post solution, the October 1 SPK announcement provided interim payments of up to TRY1 million per investor per fund for funds founded by four managers. Another announcement addressed liquidation and possible reopening for the other three, while voluntary-return accounts were established for excessive gains. Relief can reduce immediate hardship; it does not demonstrate that the institutional causes have been corrected or establish final recoveries and immunity from prosecution.
On October 6, the SPK disputed the claim of 130 ignored warnings and cited 96 criminal referrals concerning fund transactions in 2026. On October 4, it rejected claims that protection of the Investor Compensation Center’s assets originated in July 2026, citing earlier provisions. Independent review must test these defenses against dated records: aggregate enforcement activity cannot answer whether particular warnings were handled adequately.
The political feedback mechanism is crucial here: economic deterioration threatens consent; legal and administrative pressure limits the conversion of grievance into organized opposition; weaker scrutiny protects the allocation system that generated the damage. Widespread arrests and dismissals, and media censorship, show that intervention under pressure narrows scrutiny precisely when it is most necessary. An inquiry controlled by the same appointment network cannot resolve this problem without independent experts, parliamentary authority and enforceable access to records.
Conclusion
Turkey’s fund crisis is an endogenous outcome of the governing order Erdogan has constructed. Discretionary economic policy creates vulnerabilities; politically dependent institutions suppress corrective scrutiny; privileged access enables selective enrichment while losses reach ordinary investors and public balance sheets. Repeated scandals reflect the cumulative consequences of institutional choices that subordinate professional judgement to presidential authority and weaken deterrence through expectations of protection. Populist appeals to sovereignty, national distinctiveness and religious obligation legitimize this discretion, while restrictions on journalism and opposition obstruct scrutiny of its consequences.
Financial repair must therefore accompany a redistribution of institutional authority. Immediate priorities include independently verified valuations, disclosure of related-party exposures, preservation of supervisory and transaction records, and recovery from those responsible. Any public support must identify its beneficiaries, legal basis and recovery strategy. Protecting vulnerable investors requires preventing further transfers of private losses to society.
Durable recovery, however, requires constraints on the executive itself. Independent courts, effective parliamentary oversight, merit-based appointments and protection for professional disagreement must replace supervision organized around political loyalty. Regulators, auditors and market infrastructure need genuinely independent cross-checks, supported by investigative journalism, academic freedom and competitive opposition. Accountability must follow appointment and decision chains wherever they lead, including into the presidency.
The fund crisis ultimately exposes how Erdogan’s governing order converts public authority into selective private advantage while shielding its beneficiaries from independent scrutiny. Gains sustain politically connected networks; losses fall on investors, wider society and future generations. Breaking this pattern requires restoring the rule of law and subjecting presidential authority to effective institutional checks. Otherwise, replacing officials and prosecuting selected actors leaves intact the structure that enables extraction, protects privilege and reproduces impunity.
Erdogan’s responses to successive crises suggest that meaningful reform from within this governing order is increasingly implausible. The recurrent protection of connected interests supports a political-economic interpretation of corruption as a means of financing and consolidating his regime-building project. As implicated networks expand, independent accountability threatens both their accumulated advantages and the political authority that sustains them, deepening resistance to reform. Expecting Erdogan to dismantle these arrangements therefore overlooks their role in his political survival. Institutional reconstruction requires a democratic reconfiguration of power that can investigate the presidency itself.
In this commentary, Dr. Oludele Mayowa Solaja uses the concept of “climate debt populism” to examine how climate vulnerability, sovereign debt, and distributive injustice are becoming politically intertwined across Africa. He argues that adaptation finance is not only a technical question of resource mobilization, but also a struggle over responsibility, legitimacy, and who ultimately bears the costs of climate survival. Drawing on examples from Senegal, Zambia, and Malawi, Dr. Solaja shows how climate shocks can intensify fiscal vulnerability, while debt servicing can restrict governments’ capacity to invest in resilience. He calls for a more just climate-finance architecture centered on grant-based adaptation, debt restructuring, accountability, participation, and recognition of Africa’s historically unequal contribution to global emissions
Africa’s climate politics is entering a more consequential phase. The debate is no longer about whether vulnerable societies need adaptation finance, but how their political and financial relationship is shaped when they receive it through debt. The resources governments already have to service debt can create a paradox when small increases in debt are added to shield citizens from climate risks: the funds required to lessen vulnerability can create more vulnerability.
This commentary proposes the concept of ‘climate debt populism’ to reflect the political reasoning that can be forged from this paradox. I do not imply, in using the term, that there is an existing pan-African political movement, but rather use it as an analytical framework to examine the potential for linking climate vulnerability, fiscal pressure, and distributive injustice with the populist statement: communities that were least responsible for past greenhouse gas emissions should not bear the burden of additional fiscal costs just to be secure. This struggle is not fundamentally about people who want to act on climate change versus people who don’t. It is a conflict over who has the authority, responsibility, and resources to determine who pays for climate survival.
Why should those who contributed least to the climate crisis pay to survive it?
The Question Behind Climate Finance
Vulnerability is the language of climate change in Africa. With warming, droughts, flooding and food insecurity, adaptation is a pressing developmental need, with increasing water stress and disruption to livelihoods. But vulnerability is not the sole determinant of the politics of adaptation. The question of who pays for protection is becoming increasingly distributive: on whose conditions and at what cost to public finances and future generations?
The answer matters because Africa is in a unique position within the global climate economy. The continent has been responsible for a relatively small share of global greenhouse gas (GHG) emissions but faces the highest climate risks. According to the African Development Bank, Africa accounts for less than 4 percent of global emissions but receives only about 3 percent of global climate finance (AfDB, 2025). At the same time, many African countries struggle with limited fiscal space and high debt-service burdens. The outcome is a political economy where the need for adaptation meets the financial limits of the states that will be expected to provide it.
The problem is more than money. It’s about the conditions and modalities of climate finance. Grant financing can increase adaptive capacity without adding a new debt burden. Loans can offer short-term flexibility, but they can also shift the burden of financing adaptation to climate change into the future. The difference between resilience and recovery financing is a political question in situations of repeated climate shocks and additional borrowing.
Climate finance is thus not apolitical. It shares responsibilities among countries, generations and social groups. When people feel they are losing out because of climate change, and that public funding is being limited or restricted, finance becomes an issue of fairness and political legitimacy.
Changing the Conversation from Climate Populism to Climate Debt Populism
Climate debt populism is analytically different from the current discourse on climate populism and extends ideas in this conversation. Political representations of climate policy typically frame the issue as a clash between a righteous or derelict population and those who represent and are responsible for the environment and environmental transition policies, such as the state, the market, or the public interest. When the policy is contentious, as it becomes when measures like carbon pricing or subsidy reform and energy transition are felt to be economically burdensome, climate politics can get messy in these accounts.
Climate debt populism changes what is contended. Its main grievance might not be climate action. Instead, it’s about the inequity of funding climate action and climate harm. The conflict arises when the price of adaptation is seen as an indicator of an international order that is separate from responsibility and burden.
The populist logic may thus be expressed in three interconnected steps. First, a material injury is apparent: crops fail to produce, houses are destroyed by floodwater, electricity networks are weakened, livelihoods are lost, and public services are economically constrained. Second, the injury is read by making a moral judgment between those suffering and those seen to have disproportionate power to control the distribution of costs. Third, this distinction becomes a political demand for recognition, redistribution and accountability.
‘The elite’ concerned is therefore far less monolithic than in traditional national populist politics. It could involve national political and economic decision makers, foreign creditors, financial institutions, rich high-emitting countries and technocratic institutions thought to set the rules for accessing funding by vulnerable societies. This doesn’t mean these actors form a unified bloc. Instead, they can be symbolically linked in a popular story of unequal responsibility.
This matters because it avoids making the concept synonymous with anti-Westernism or with opposition to the international financial system. Climate debt populism is not a movement against debt, but a struggle about the legitimacy of an unequal burden of climate responsibility. Its basic moral principle is that adaptation costs should be assigned by considering historical responsibility, current exposure, and financial resources.
Debt Amplifies Climate Change as a Political Vulnerability
Young African woman carrying water in a village near Bamako, Mali, symbolizing the human impact of drought and water scarcity. Photo: Dreamstime.
This political claim has material force through debt. According to ActionAid International’s analysis of 65 highly climate-vulnerable countries, in September 2026, these countries will have paid almost 25 times more on debt repayments than on climate action. It notes that debt servicing as a share of government revenue is estimated to consume about 65 percent in Global South countries and is about 225 times higher than the climate finance they receive via grants (ActionAid International, 2026). The statistics must be viewed with care as they are an amalgamation and do not represent a consistent African experience. Their importance, however, lies in the structural relationship they point to: obligations to repay fiscal resources can take up fiscal resources just when investment in adaptation has to increase.
The resulting mechanism is potentially self-reinforcing. High-severity climate events cause economic and physical damage. The funding of emergency relief, reconstruction and social protection in the face of the government must be made. If grants and concessional resources are insufficient, additional borrowing becomes attractive or unavoidable. This leaves less fiscal room for preventive investments because of debt-service obligations. Weak adaptation leaves communities exposed to subsequent shocks, which generate additional losses and renewed financing needs. Fiscal vulnerability can thus exacerbate climate risk, and climate risk can constrain capacity to reduce fiscal vulnerability.
This is not to say that climate change is solely responsible for debt crises in Africa. Sovereign debt is determined by domestic fiscal policies, commodity dependence, exchange-rate pressures, borrowing policies, governance, global interest rates and the structure of the international financial system. A credible argument in the name of climate justice must, therefore, withstand monocausal explanations. The more assertive position is that climate shocks exacerbate existing financial fragilities and can make an already challenging debt situation much tougher.
Senegal: When Debt Service Crowds Out Climate Ambition
Senegal is a case in point for the inseparability of politics and fiscal capacity in climate finance. According to ActionAid’s 2026 analysis, Senegal’s debt servicing is more than 96 percent of government revenue and over 600 times its planned spending on climate action. For every US$1 budgeted for climate action, US$605 is being spent on debt servicing, according to the calculation. The exact proportion should be regarded as a representation of the fiscal structure of a particular advocacy organization, and not as a yardstick for the country’s fiscal structure. Its political significance nevertheless remains striking.
Fiscal constraint is not a macroeconomic phenomenon, but a condition that affects citizens engaged in agriculture and reliant on infrastructure and functioning public services. It is felt when there is a risk, and the state is unable to protect people. A farmer confronting declining productivity does not experience sovereign debt as a balance-sheet category. The experience is mediated through access to irrigation, agricultural support, roads, electricity, social protection and the state’s capacity to respond when climate shocks occur.
This is where climate debt can acquire populist meaning. When citizens feel that public institutions can afford external debt but not internal security against environmental insecurity, the line between economic and climate injustice becomes a political debate. The question becomes less “How much finance has been mobilized?” and more “Whose obligations are being prioritized?”
Zambia: When a Climate Shock Becomes a Fiscal Shock
Zambia illustrates an aspect of the issue, where environmental shocks rapidly turn into macro-economic and political shocks. The World Bank described the country’s 2024 drought as the driest in decades; it affected approximately 9.8 million people, with 6.6 million experiencing severe food insecurity. Likewise, Zambia’s reliance on hydropower worsened a major electricity crisis, and agricultural production was also greatly affected (World Bank, 2024).
These pressures were added to a challenging debt restructuring process. The World Bank then approved US$100 million to finance development policy and provide a support facility for catastrophe events, highlighting the need for liquidity in the event of a climate shock. However, there is a deep challenge that needs to be addressed: emergency funding can mitigate and repair harm in the short term, but it will not necessarily close gaps in the longer term in the resources needed to prepare for adaptation.
Climate events remain a downside risk to Zambia’s debt-service capacity, according to the IMF’s 2026 assessment. This connection has political importance, as it links environmental insecurity to the state’s fiscal stability. A succession of shocks may then alter citizens’ perceptions of national governments and the international financial system as a whole. When the climate is made insecure, it tests institutions’ capacity to offer security without adding another generation of debt.
Malawi: The Politics of Rebuilding the Same Future
Malawi’s experience with Cyclone Freddy makes the distributional stakes equally visible. According to the World Bank (2023), material losses amounted to about US$505 million, while production losses were around US$36.4 million, equivalent to about 0.5 percent of Malawi’s 2023 GDP. These statistics concealed the destruction of homes, disruption of agriculture, damage to infrastructure and loss of livelihoods.
Reconstruction is a tough decision for a budget-constrained government—balancing the social and political costs of leaving communities exposed with the financial costs of borrowing to rebuild. Governments could continue to pay for the impacts of climate hazards without sufficiently reducing the likelihood or impact of further loss.
This is why it is as important as the amount of climate finance as it is well-designed. A dollar of grant finance and a dollar of sovereign borrowing are not politically equivalent. They distribute obligations differently across time and across social groups. The former can build the community’s public capacity without adding to the repayment burden; the latter can shift some of today’s adaptation burden onto future taxpayers. Therefore, it is not only a matter of mobilizing resources, but of their financial architecture as well, that is, a matter of climate justice.
From Climate Victims to Climate Creditors
One of the most profound political changes may be conceptual. African countries have often been portrayed internationally as weak recipients that need help. This is becoming an outdated perspective. Climate-justice claims are increasingly becoming language of responsibility, entitlement and institutional change, rather than “help us because we are vulnerable”; it is becoming “recognition of what is owed because responsibility and harm are unequally distributed.”
Warlenius (2018) proposed a shift from emissions to questions of responsibility, atmospheric space, and compensation through the concept of climate debt, which emerged within climate-justice movements. This argument considers the intersection of the moral grammar of climate debt, current sovereign debt, and the lived reality of adaptation under fiscal constraint.
This suggests a politically viable possibility of reversal. African countries cannot be read only as clients of a lender who comes to them for help. They can also speak in a way that makes them claimants in a just climate order. The language of ‘climate creditors’ can help here as a political metaphor; it emphasises the historical and distributive aspects of climate responsibility, but does not suggest that African states have traditional financial claims against specific governments.
Making this distinction is crucial. Climate-creditor politics does not absolve African governments of responsibility. Vulnerability may be exacerbated by corruption, weak institutions, unsustainable borrowing patterns and poor public spending and African governments should be held accountable at home. There is no conflict between international responsibility and national accountability. They work at various levels of the same political economy.
The New Political Antagonism
At this point, climate debt populism is analytically useful. It recognises a type of political opposition based on the unequal division of financial responsibilities, where material climate insecurity is expressed in this way. The applicable political boundary is not definitive. It could be between citizens and national elites, vulnerable states and creditors or historically high emitters and climate-sensitive societies. In practice, these boundaries can overlap.
The risk is that such a politics can go in two extremely different directions. It can create a democratic politics of climate justice, calling for transparency in finance, reorganization of debt, and reparative responsibility and greater public accountability. However, it can also be seized by the political entrepreneur who simplifies the weave of politics to an unchecked story of foreign conspiracy, domestic betrayal or perpetual victimhood. The concept should not therefore be considered – normatively – as progressive or regressive.
It is a democratic question in that it raises a public debate over who is best positioned to determine who will bear the costs of climate change. Failing to involve citizens in designing climate finance through technical negotiations and institutions far removed from the people can create a legitimacy deficit with political repercussions. On the other hand, if climate finance is transparent, locally accountable, and clearly linked to social protection and adaptation outcomes, it can reinforce democratic trust.
Preserving the Natural World within the Context of Non-Debt-Creating Adaptation (COP31)
This debate comes at an opportune moment. Adaptation, finance, and loss and damage are key themes of the climate negotiations to be discussed at COP31, to be held in Antalya from 9-20 November 2026. African governments should thus ask not just how much money is pledged, but how much they will receive in the end. What forms of finance are being provided, on which terms and at what cost to future generations?
The answer matters because a climate finance target can be achieved in several ways that produce very different politics. A significant share of adaptation resources could be financed through loans, which may provide immediate financial support to vulnerable states but create future debt obligations. This finance can be beneficial in certain instances, especially when concessionality is high, and investments have a productive return. However, borrowing does not always align with climate justice.
A more believable framework for getting climate finance to Africa would thus be based on four pillars. First, adaptation finance really needs to be far more grant-based, especially in highly vulnerable countries with limited fiscal space. Second, the support for loss and damage should be on top of, not instead of, adaptation finance. Third, countries already experiencing unsustainable debt levels should have trustworthy debt-restructuring instruments, so climate shocks are not necessarily a source of additional debt crises. Finally, African countries and affected communities should be more influential in designing, allocating and monitoring climate finance.
In particular, the fourth principle is important. Wealth redistribution is not the only issue of climate justice between North and South. It is also about redistribution within countries. External resources can fuel inequality when they fall into the hands of political elites, are concentrated in capital-heavy projects, or are not tied to the communities most vulnerable to climate risks. This is why a just climate-finance architecture should link international and domestic responsibility, transparency, participation, and accountability.
Beyond the Politics of Vulnerability
The politics of African climate change is thus shifting away from a politics of vulnerability. The danger remains very real, but it is no longer politically sufficient. More and more governments, movements, and citizens are asking what vulnerability means in a global context where the conditions of climate change and climate impacts do not align with the distribution of financial means.
One possible political result of this contradiction is climate debt populism. It emerges when climate insecurity and debt insecurity become legible as parts of the same injustice, and when citizens interpret adaptation financing as a test of who counts, who owes, and who has the authority to determine the future. The idea thus includes a political element to a policy discussion that is frequently framed as a purely technical matter of climate finance.
The broader importance of the study is to move from the question “How much climate finance is needed in Africa” to “What political order is being reproduced in the provision of climate finance?” That question is more complex, as it deals with responsibility, power, debt, legitimacy, and distribution at the same time.
Africa does not need a regime of climate finance that makes adaptation possible today and harder to sustain in the years to come. Nor does it need a politics that converts legitimate climate grievances into simplistic blame. What is needed is a system in which the three aspects of historical responsibility, financial capacity, domestic accountability, and democratic participation are seen as interlinked aspects of climate justice.
The decisive test of climate finance is not whether money reaches vulnerable countries. It is whether that money enables them to become less vulnerable without increasing their debt. This is indeed the political issue of climate adaptation. The language of vulnerability is giving way to the language of entitlement in Africa’s climate politics: from “Save us from a crisis” to “acknowledge the distribution of responsibility for a crisis.” If that shift becomes politically salient, climate finance will no longer be a technocratic subfield of international development. It will be at the heart of the battle for global justice, global sovereignty and democratic legitimacy.
Who pays to adapt—and, in the emerging politics of climate debt, who actually owes whom?
United Nations Framework Convention on Climate Change. (2026). COP31. UNFCCC.
Warlenius, R. (2018). “Decolonizing the atmosphere: The climate justice movement on climate debt.” Development and Change, 49(2), 454–478. https://doi.org/10.1111/dech.12387
Professor Ibrahim Ozturk argues that Turkey’s 2027–2029 Medium-Term Program is less a credible development strategy than a politically sequenced exercise in economic populism. While promising lower inflation, faster growth, and technological upgrading, the program simultaneously expands current transfers, procurement, interest payments, and fiscal deficits while squeezing productive capital expenditure. Professor Ozturk contends that this structure reproduces a familiar electoral cycle: benefits are front-loaded, while the costs are deferred through inflation, taxation, debt, currency depreciation, and declining real wages. He further warns that Turkey is shifting from a developmental state toward a transfer state in which politically protected rents crowd out productivity-enhancing investment. The ultimate cost, he argues, is not merely fiscal instability but the erosion of Turkey’s long-term productive capacity and competitive advantage.
The classical paradigm of macroeconomic populism, articulated by Rüdiger Dornbusch and Sebastian Edwards in The Macroeconomics of Populism in Latin America, describes a self-defeating political-economic cycle in which governments prioritize short-term growth and redistribution while discounting inflation, fiscal sustainability, productive capacity, and external constraints. These programs generally emerge in societies marked by deep socioeconomic inequality, declining trust in established institutions, and accumulated demands for redistribution. Governments respond by combining expansionary fiscal policies, rapid credit growth, substantial nominal wage increases, administered prices, subsidies, and attempts to suppress exchange-rate volatility. During the initial phase, the resulting demand shock can generate a temporary boom: capacity utilization rises, employment expands, real wages may initially improve, and politically visible consumption increases.
The apparent success of this first phase reinforces the government’s claim that conventional fiscal and monetary constraints can safely be disregarded. Yet the expansion does not necessarily increase productive capacity. When aggregate demand exceeds domestic supply, production bottlenecks intensify, imports rise, foreign-exchange requirements increase, and inflationary pressures accumulate. Attempts to suppress inflation through price controls, subsidized credit, fiscal transfers, or an overvalued exchange rate merely postpone—and often magnify—the eventual adjustment.
As foreign-exchange reserves decline and fiscal and external imbalances become increasingly difficult to finance, inflation accelerates, confidence deteriorates, capital moves abroad or into foreign currency, and the domestic currency depreciates. The government is ultimately forced to adopt stabilization measures involving tighter credit, higher interest rates, fiscal retrenchment, tax increases, and real-wage compression. The central paradox identified by Dornbusch and Edwards is therefore distributive: the social groups whom populist policies initially promise to protect frequently bear the heaviest burden of the subsequent crisis and adjustment.
A second strand of the literature explains why such policies remain politically attractive despite their recurrent economic costs. Acemoglu, Egorov, and Sonin argue that politicians may strategically adopt radical or economically costly positions to signal that they are not controlled by established elites. This signaling mechanism can make policy extremism electorally advantageous even when its longer-term economic consequences are damaging.
Dani Rodrik, in turn, emphasizes that globalization, technological disruption, regional inequalities, and distributional shocks generate genuine grievances that populist actors can mobilize. Populism therefore cannot be understood solely as manipulation from above. It also draws strength from real failures of representation, social protection, and economic inclusion. Once political leaders weaken institutional constraints and subordinate economic policy to electoral survival, however, legitimate grievances can become a mechanism for sustaining increasingly discretionary and unsustainable policies.
The conceptual distinction is crucial. Redistribution is not inherently populist, nor is every expansionary fiscal policy economically irresponsible. Redistribution becomes part of populist macroeconomic management when politically visible benefits are concentrated before an electoral deadline, their financing is concealed or deferred, productive and institutional constraints are disregarded, and the eventual adjustment is transferred to society through inflation, taxation, currency depreciation, public debt, unemployment, and declining real wages.
From the Classical Populist Cycle to Turkey’s Growth-Inflation Trap
Turkey’s recent experience does not reproduce every element of the classical Latin American model mechanically. It nevertheless displays several of its central political-economic mechanisms: the subordination of monetary policy to political objectives, credit-led demand expansion, the erosion of central bank credibility, extensive reliance on administrative interventions, the depletion of foreign-exchange buffers, and the postponement of adjustment until after politically critical moments.
Figure 1 places Turkey’s real GDP growth and officially reported year-end consumer-price inflation side by side. Between 2018 and 2025, inflation rose dramatically without a corresponding durable acceleration in real economic growth. The exceptional growth recorded in 2021 largely reflected the post-pandemic recovery, strong credit expansion via artificially subsidized negative real interest rates, and favorable base effects; it should not be interpreted as evidence that higher inflation generated structurally stronger growth.
Note: 2018–2025 growth figures are annual changes in real GDP, and inflation figures are December year-on-year CPI rates. For 2026, the figure uses Q2 year-on-year GDP growth and June year-on-year CPI inflation. The correlation is descriptive and does not imply causality. Source: Author’s compilation based on TurkStat and CBRT data.
The simple contemporaneous correlation between the two variables is positive but only moderate—approximately 0.44—and does not establish causality. More importantly, the temporal pattern reveals a widening divergence between nominal instability and real economic performance. Inflation exceeded 64 percent in 2022 and 2023, while real GDP growth remained close to 5 percent. As officially reported inflation subsequently declined, growth also weakened, reaching 2.3 percent year on year in the second quarter of 2026.
The central issue is therefore not whether inflation and growth occasionally move in the same direction, but whether inflationary expansion produces sustainable improvements in productivity, investment quality, technological capacity, employment, and household welfare. Turkey’s experience provides little evidence that it does. An inflationary growth strategy can temporarily support consumption, construction, government-directed investment, and politically connected sectors without generating comparable improvements in total factor productivity or long-term supply capacity. Measured GDP growth may consequently coexist with deteriorating income distribution, declining purchasing power, inefficient capital allocation, and eroding institutional credibility.
Turkey’s 2027–2029 Medium-Term Program (MTP) should be read through this conceptual and empirical lens. Although presented as a medium-term framework, its macroeconomic targets, expenditure composition, revenue assumptions, and sequencing of policy measures reveal a considerably shorter political horizon. The central question is whether the program constitutes a credible transition towards price stability, productive investment, institutional normalization, and distributive justice—or another attempt to defer structural adjustment while protecting Erdogan’s immediate political survival.
The Three Tests of an Economic Program
Every serious economic program must answer three elementary questions. First, how will the economy produce more and better goods and services? Second, how will scarce capital, labor, public revenue and foreign exchange be allocated to their most productive uses? Third, how will the resulting national income be distributed across households, firms, regions and generations? Growth, allocation and distribution are not separate chapters. They are a single system.
Analytical Frame: What the MTP Must Demonstrate
Judged by this triad, the MTP fails at a deeper level than forecast inconsistency. It subordinates production to demand management, efficiency to politically protected transfers, and distributional justice to a sequence in which organized beneficiaries receive secure returns while the wider public absorbs inflation, taxation and deteriorating public services.
A Program Without an Institutional Kitchen
The MTP reads less like the output of an autonomous professional planning process than a document assembled backward from a political requirement. The targets appear first; the behavioral mechanisms, policy instruments, implementation responsibilities, risk scenarios and trade-offs needed to make them mutually consistent are either missing or underdeveloped. This is what a program produced under political pressure looks like: arithmetic without architecture.
That weakness is inseparable from institutional history. The State Planning Organization (SPO), which accumulated specialized staff, sectoral memory and a culture of medium-term coordination, was abolished as a distinct organization in 2011 and transferred into the Ministry of Development. In 2018, the Presidency reorganized planning and budgeting functions under the Strategy and Budget Presidency. Formal responsibilities remained, but the center of gravity shifted from relatively autonomous technocratic coordination to a vertically controlled executive structure. The 2018 Presidential Decree establishing the Strategy and Budget Presidency documents these institutional changes. The analytical conclusion follows from the MTP itself: when autonomy, professional challenge, and collective deliberation are weakened, implausible assumptions are less likely to be questioned before publication. The issue is not the personal competence of every civil servant involved. It is the institutional environment in which competence can no longer constrain politics. Merit, teamwork and professional dissent cannot correct a program when the desired electoral conclusion is fixed in advance.
A Medium-term Program with a Short-term Political Horizon
The MTP projects faster growth, lower inflation, falling unemployment, a smaller current-account deficit and—after a temporary 2027 deterioration—a lower budget deficit. None of these outcomes is impossible in isolation. Their simultaneous delivery, however, requires a major productivity shock, stronger expectations, sustained capital inflows and unusually high policy credibility. The MTP states the destination more clearly than the transmission mechanism.
The Fiscal Fingerprint of an Early Election
The program’s political character is clearest in the 2027 budget. Expenditure rises faster than revenue; the budget deficit increases by almost 47 percent; and the already modest primary surplus is nearly halved. The MTP therefore does not begin its disinflation story with fiscal restraint. It begins with fiscal expansion.
The deficit-to-GDP ratio rises from 3.1 percent in 2026 to 3.5 percent in 2027, while the primary surplus almost disappears. In other words, the fiscal stance loosens just as the MTP claims inflation expectations will be decisively anchored.
Against the MTP’s roughly 25 percent 2027 deflator, current transfers rise by about 16 percent in real terms and purchases of goods and services by roughly 15.5 percent, while capital spending falls by about 17 percent in real terms. The contradiction is not rhetorical; it is embedded in the allocation.The MTP’s narrative promises technological upgrading; its budget finances current transfers, procurement and interest.
The 2023 Cycle Is Being Reconstructed
Turkey’s 2023 election cycle combined subsidized credit, public wage and pension increases, retirement arrangements, tax restructuring, energy support and extensive foreign-exchange and credit interventions. After the election came sharp depreciation, higher indirect taxes, tighter monetary policy and declining real purchasing power. The sequencing mattered: the benefit was immediate and politically visible; the correction was delayed and socially dispersed.
The MTP’s 2027–2029 path risks reconstructing the same political technology. The 2027 expansion supplies the distributive moment; the lower deficits and inflation promised for 2028–2029 imply the later correction. This is the classic time structure described by the economic-populism literature.
Distribution: Poverty Is Not a Footnote
The MTP discusses per-capita income and social policy, but aggregate averages conceal the depth of the subsistence crisis. Labor union TURK-IS calculated the August 2026 monthly food-only hunger threshold for a four-person household at TRY 37,388 and the broader poverty threshold at TRY 121,786; the estimated living cost of a single employee was TRY 48,305. These benchmarks show how far ordinary labor income has fallen behind the cost of basic reproduction.
The comparison permits a forceful but precise conclusion: the average household income of the poorest 40 percent is below the TURK-IS hunger threshold, while the average income of the bottom 80 percent is below its poverty threshold. This does not mean every household in those quintiles falls below the relevant line; the figures are quintile averages, and the TURK-IS thresholds refer to a four-person household. (See TURK-IS, August 2026 Hunger and Poverty Threshold. TUIK’s official relative-poverty rate—13.0 percent in 2025—uses an equivalized median-income methodology and therefore answers a different question. The two measures should not be conflated).
The methodological caution does not weaken the substantive conclusion. When the minimum wage is below a food-only threshold for a representative family, and the broader basic-needs budget is multiples of ordinary earnings, distributional stress is systemic. The MTP’s reliance on indirect taxation, inflationary erosion, and delayed adjustment means that lower- and middle-income households finance a disproportionate share of the program.
Economic populism does not correct this injustice. It temporarily compensates selected groups, then recreates poverty through inflation, currency depreciation, taxation, and compressed real wages. It distributes relief politically and distributes the bill socially.
Tax More, Privatize More, Borrow More
The revenue side does not solve the contradiction; it exposes it. In 2027, tax revenue is programmed to grow by 36.5 percent, faster than nominal GDP growth of about 30.3 percent. Tax revenue rises from 17.1 to 17.9 percent of GDP, while the total tax burden, including social-security contributions, moves from 24.3 percent in 2026 to 24.8 percent in 2027 and 25.1 percent by 2029. The MTP therefore couples visible expenditure with a rising social tax burden.
Privatization revenue jumps by roughly 70 percent in 2027, yet the MTP does not identify the assets, valuation logic or economic rationale behind that acceleration. Even if fully realized, the proceeds would finance less than 5 percent of the projected budget deficit. This is not a structural revenue strategy; it is a temporary financing device.Tax more, sell more and borrow more—then channel the proceeds into current expenditure, interest and guaranteed returns.
From a Developmental State to a Transfer State: Interest as Upward Redistribution
The MTP projects approximately TRY 13.9 trillion in cumulative interest payments during 2027–2029, against only about TRY 7.1 trillion in capital expenditure. In 2027 alone, interest is 2.15 times capital spending and close to 20 percent of tax revenue. At TRY 3.98 trillion, interest expenditure even exceeds the projected TRY 3.87 trillion budget deficit.
Interest is not merely a technical cost of debt. Under these conditions, it becomes a distributional mechanism: broad-based taxation and inflation-generated fiscal revenue are transformed into secured financial returns. Resources that could support education, research, technological upgrading, industrial capability and social resilience are transferred to holders of public debt.
Guaranteed Rent Capitalism
A second transfer channel lies outside the interest line: public–private partnership guarantees. For 2026, approximately TRY 136.1 billion was discussed for rent and service payments to 18 city hospitals, while about TRY 101.3 billion was allocated for bridge, motorway and tunnel guarantees. Together, these visible channels approach TRY 237.5 billion. Parliamentary budget proceedings on city hospitals and reporting on transport guarantees illustrate how these obligations are dispersed across rents, availability payments, services, traffic or revenue guarantees and exchange-rate adjustments. The problem is not the Public–Private Partnership (PPP) instrument in principle. It is the allocation of demand and currency risk to the state, the protection of corporate revenue over long horizons, and the limited transparency of effective returns and renegotiation terms. Profit is privatized while risk is socialized.
The MTP repeatedly invokes artificial intelligence, semiconductors, digitalization, green transformation and high-value-added exports. Yet its budget composition crowds out the very capital formation needed to make those ambitions credible. The state’s function shifts: its developmental and social capacities weaken, while its tax-collecting, interest-paying and guarantee-providing roles expand.
This changes incentives throughout the economy. Firms gain more by securing public contracts, guarantees and regulatory privilege than by building capabilities, raising productivity or competing internationally. Connections and rents displace innovation and competitive advantage.
Production: Growth Without Upgrading
The MTP treats a rising GDP growth path as evidence of development. But growth generated by public consumption, protected construction, credit expansion and imported inputs is not equivalent to a durable increase in productive capacity. The relevant question is not only how fast output grows, but what is produced, with which technology, at what import content, and with what learning effect.
The OECD Economic Survey of Türkiye 2025 concludes that future convergence must increasingly come from productivity because the demographic dividend is fading and investment is already high. Yet productivity has slowed, investment has flowed disproportionately into lower-productivity areas such as housing, and intellectual-property investment has been roughly half the European share. High-technology exports have remained around 3.5 percent of manufactured exports, far below comparable upper-middle-income economies.
This is precisely why the MTP’s expenditure composition is so damaging. A country that needs skills, research, digital diffusion and export sophistication cannot treat capital spending as the residual item after interest, transfers and procurement. The program may raise measured demand in 2027 while lowering the economy’s ability to generate non-inflationary supply thereafter.
Allocation: The Destruction of Efficiency
Resource allocation is the bridge between today’s spending and tomorrow’s productive frontier. An efficient system directs finance, land, public procurement, skills and foreign exchange toward firms and sectors capable of learning, innovating and competing. A rent-based system directs them toward political access, guarantees, sheltered markets and balance-sheet protection.
The MTP deepens the second pattern. Interest payments reward the holders of financial claims; public–private partnership guarantees protect selected corporate cash flows; current transfers and procurement grow rapidly; and capital expenditure is squeezed in real terms. The result is not merely waste in a static accounting sense. It is dynamic misallocation: productive firms face high financing costs and uncertainty while politically connected activities enjoy protected returns.
The OECD’s assessment reinforces this diagnosis: productivity is impaired by skill mismatch, barriers to business dynamism, state intervention and weak competition in network sectors. It estimates that pro-competition reforms in infrastructure-dependent sectors could materially raise firm-level productivity (See the OECD’s competitiveness and innovation chapter.) The deepest cost is not this year’s deficit. It is the competitive capability that Turkey fails to build.
Economic Populism as a Strategy of Regime Reproduction
The political logic extends beyond ordinary electoral opportunism. Erdogan needs a renewed coalition, a favorable parliamentary balance and a constitutional or electoral route to reproduce the regime. Article 116 of the Constitution provides that if parliament renews elections during the president’s second term, the incumbent may stand once more. This provision does not prove a 2027 election, but it makes the concentration of fiscal expansion in 2027 politically significant. See the official English text of the Constitution of the Republic of Turkey. The MTP’s timing fits a strategy in which benefits are immediate and attributable, while costs are postponed, fragmented, and depoliticized.
Gambling with Turkey’s Future
The central problem is not that Turkey lacks resources. The program simultaneously damages all three foundations of the economy. It produces growth without sufficient productive upgrading; it allocates capital away from its highest social return; and it distributes income and adjustment costs in favor of organized financial and politically protected interests.
The immediate casualty is distributive justice. The medium-term casualty is fiscal and macroeconomic sustainability. The longest-lasting casualty, however, is competitive advantage. Inflation can eventually be reduced, and a budget can eventually be tightened. Capabilities not built, skilled people lost, firms excluded from finance, technologies not absorbed and export markets surrendered are far harder to recover.
In that sense, the MTP is less a medium-term development program than an intertemporal political bargain drafted inside a weakened institutional order. The Erdogan regime borrows from Turkey’s future to purchase support in its present. It sacrifices not only fairness in distribution, but efficiency in resource allocation and sustainability in production. The recovery can be staged; the underlying model cannot be sustained.The election comes in 2027. The taxes, inflation, debt and lost development arrive in 2028.
Please cite as: Yang, Li; Yeh, Kuang-Ho; Raza, Hassan; Abdelbaki, Mohamed; Incani, Noemi; Koleszar, Réka; Ruttencutter, Sarah & Camoletto, Virginia. (2026). “From Tariffs to Conditional Integration: An EU Strategy for Chinese Electric-Vehicle Investment under the Industrial Accelerator Act.” Policy Papers. European Center for Populism Studies (ECPS). September 3, 2026. https://doi.org/10.55271/pop0006
Abstract
Europe does not face a simple choice between admitting inexpensive Chinese electric vehicles and closing its market to protect domestic producers. The harder question is how foreign manufacturing can support decarbonization without hollowing out the industrial and employment base that makes the transition politically sustainable. The European Commission’s proposed Industrial Accelerator Act (IAA) is an important but incomplete answer. Tariffs can buy time and origin rules can anchor production, but neither instrument alone can create software capabilities, retrain workers or strengthen regional suppliers. This paper compares defensive localization, managed openness and conditional integration, and recommends the third. Its three core proposals are a European Automotive Investment Compact, a Skills and Regional Transition Covenant, and a ring-fenced European Automotive Transition Financing Window. A software and data pillar and a structured implementation dialogue with China would support delivery. The aim is not decoupling or unconditional access, but the conversion of market-seeking investment into capabilities that Europe can retain.
Keywords: European Union; China; electric vehicles; Industrial Accelerator Act; conditional integration
By Li Yang, Kuang-Ho Yeh, Hassan Raza, Mohamed Abdelbaki, Noemi Incani, Réka Koleszar, Sarah Ruttencutter & Virginia Camoletto
Introduction
Europe’s automotive debate is often framed as a contest between climate ambition and industrial protection. The issue is broader: can the European Union decarbonize transport while retaining enough productive, technological and social capacity to sustain public support? The sector provides direct and indirect work for approximately 13.8 million Europeans and supports extensive networks in steel, chemicals, electronics, software, logistics and services (European Commission, 2026a). When a major plant or supplier reduces production, the effects concentrate in towns where alternative employment may be scarce, and industrial identity remains politically important.
The pressure is real, but its causes are mixed. European producers face high energy costs, fragmented capital markets, uneven charging infrastructure, regulatory complexity and slow progress in software-defined vehicles (Draghi, 2024; European Commission, 2025; van Wieringen, 2024). They also confront a Chinese industry built on scale, intense domestic competition, integrated battery supply chains and rapid product development. China accounted for more than 70 percent of global electric-car production in 2024, while sales of Chinese-made electric cars in Europe continued to grow in 2025 (IEA, 2025; IEA, 2026). This is not merely an import surge, but a collision between industrial systems as EU regulation creates a large market for electric mobility (Ban & Šćepanović, 2026; van Wieringen, 2024).
This collision has a political dimension. The IAA proposal notes that more than 100,000 automotive job cuts were announced in 2024 and 2025 (European Commission, 2026c). Chinese competition is not the sole cause: weak demand, delayed investment, management choices and technological change also matter. Research on Germany shows that actual job loss and fear of future decline can produce different forms of protest, with right-wing populist support particularly responsive where manufacturing remains central to local identity, but its future appears insecure (Bayerlein, Kölzer & Metten, 2026). Trade shocks also make openness easier to portray as a bargain imposed on workers rather than negotiated with them (Poletti, 2026).
The EU has already responded. Following its anti-subsidy investigation, it imposed definitive countervailing duties on battery electric vehicles imported from China, with company-specific rates ranging from 7.8 to 35.3 percent in addition to the ordinary tariff (European Commission, 2024). The duties address identified subsidization and create breathing space for European manufacturers. They do not resolve Europe’s internal weaknesses. A tariff cannot build a battery plant, train a software engineer, connect a factory to affordable electricity or help a medium-sized supplier convert from combustion-engine components to power electronics.
The European Commission’s March 2026 proposal for the Industrial Accelerator Act (IAA) moves beyond border measures. It would create lead markets for low-carbon and European-made products, simplify permitting and seek to ensure that major foreign investments generate value inside the Union. Its foreign-investment chapter would cover investments above EUR 100 million in strategic sectors when a single third country holds more than 40 percent of global manufacturing capacity. Under the Commission proposal, covered investments would have to meet at least four of six conditions concerning ownership, joint ventures, technology licensing, EU research spending, employment and local sourcing; the employment condition would be mandatory (European Commission, 2026c, 2026d).
This policy paper argues that the IAA should become the basis for a policy of conditional integration rather than defensive exclusion. Chinese investment can accelerate European electrification and add manufacturing capacity. Yet investment should not be treated as beneficial simply because a factory stands within EU borders. The relevant test is whether it strengthens capabilities that remain in Europe: skilled employment, local suppliers, research, engineering, data governance, circular production and regional resilience. The task for DG TRADE, DG GROW and the wider Commission is to make these conditions predictable, proportionate and common across the Single Market.
Europe’s Automotive Dilemma
The EU’s dependence on China runs through battery cells, processed materials, components and production equipment, not only finished vehicles. Chinese firms benefit from a dense ecosystem in which battery makers, car manufacturers, software providers and suppliers develop products quickly and at scale. European companies remain strong in engineering, premium brands, safety and research, but competition increasingly turns on vehicle software, battery management, data integration, user interfaces and rapid product cycles (IEA, 2025; IEA, 2026; van Wieringen, 2024).
This is why the present ‘China shock’ differs from a conventional import surge. European climate policy is deliberately expanding demand for electric mobility. If European firms and suppliers cannot respond quickly, the demand created by EU regulation will be met by imported vehicles and components. Decarbonization would proceed, but with fewer of the industrial learning effects, investments and jobs that policymakers expected. The dilemma is therefore not whether Europe should remain open. It is how to prevent openness from becoming a one-way transfer of market share while avoiding a protectionist turn that raises consumer prices and slows electric-vehicle adoption (IEA, 2026; van Wieringen, 2024).
Trade figures reinforce the sense of imbalance. In 2025, the EU exported EUR 199.6 billion in goods to China and imported EUR 559.4 billion, producing a deficit of EUR 359.8 billion (Eurostat, 2026). A bilateral deficit is not, by itself, evidence of unfair trade. It does, however, intensify political pressure when it coincides with plant closures and visible import growth in a strategic industry. Measures presented as technical trade defense can quickly become symbols in a wider argument about sovereignty, dependence and the distribution of globalization’s costs.
Hard protectionism would not solve the problem. Europe still needs affordable EVs, competitive batteries and private investment, as well as cooperation with China on climate, standards and trade. Closing the market would reduce competition, delay capacity expansion and invite retaliation. It could also divert Chinese exports towards Europe’s southern neighborhood, where European manufacturers already face stronger competition (Fulton, Lons & Tsang, 2026). A broader protectionist turn would also shrink a major market for Chinese firms and make EU rules less predictable (IEA, 2026; Tagliapietra, Trasi & Sebastian, 2025).
Unqualified openness is equally inadequate. Chinese car and battery manufacturers are investing in Europe or considering local production, which can create jobs and shorten supply chains. Yet local assembly does not necessarily create local capability. A plant may import high-value inputs, retain research and software functions elsewhere and generate mainly assembly jobs. Separate Member-State negotiations can therefore produce uneven benefits and a subsidy race in which the largest public budgets attract the most valuable projects (Tagliapietra, Trasi & Sebastian, 2025).
The green transition must therefore be understood as a political bargain. Consumers need affordable vehicles. Firms need predictable rules and access to finance. Workers need credible routes into new occupations. Regions need replacement investment before old capacity disappears. The EU needs resilience without autarky, and Chinese investors need access without assuming that access can remain detached from European social and industrial concerns. Conditional integrationoffers a way to connect these interests.
Why the Industrial Accelerator Act Is Only a Partial Answer
The proposed IAA is significant because it recognizes that trade policy, industrial policy and foreign investment can no longer be treated as separate fields. Its demand-side measures would use public procurement and support schemes to favor low-carbon and European-made products in selected sectors. Its permitting provisions would aim to reduce delays through digital procedures and industrial acceleration areas. Its investment chapter would seek to prevent strategic foreign projects from operating as isolated enclaves by linking approval to European participation, research, training and value-chain integration (European Commission, 2026c, 2026d).
These are useful corrections to a policy model that relied heavily on carbon regulation and market incentives while assuming that industrial capacity would follow. The proposed IAA also reflects the Draghi Report’s argument that decarbonization can support growth only when climate targets are matched by investment, innovation and coordinated industrial action (Draghi, 2024). In the automotive sector, the proposed Act could help create demand for European batteries and components and give public authorities leverage when negotiating with major investors.
The difficulty is that location is not the same as competitiveness. The proposed IAA is strongest on vertical questions: where a battery cell is produced, how much Union-origin content a supported vehicle contains, or whether an investment creates jobs. It is weaker on the horizontal systems that determine long-term performance, including software platforms, vehicle data, cybersecurity, testing environments, charging infrastructure and recycling (European Commission, 2025; van Wieringen, 2024). A factory may satisfy an origin rule while remaining dependent on technology and critical components controlled elsewhere.
The proposed foreign-investment provisions also need refinement. A four-out-of-six test gives flexibility, but investors may select the least demanding combination without producing the capabilities Europe most needs. The proposed 50 percent EU-workforce threshold cannot distinguish temporary assembly jobs from durable technical and research positions. Moreover, conditions tied directly to the purchase or use of domestic goods can create risks under the WTO Agreement on Trade-Related Investment Measures, while compulsory or uncompensated technology transfer would be politically and legally vulnerable (WTO, 1994). China’s Ministry of Commerce has criticized the proposal on precisely these grounds and warned of countermeasures (MOFCOM, 2026a, 2026b).
A further weakness is finance. The proposal warns that uncoordinated national measures can fragment the Single Market, but much industrial support still depends on national fiscal capacity. Germany or France can offer packages that smaller or more indebted Member States cannot match. Without a common EU layer, ‘Made in EU’ may in practice become ‘made in the Member States with the largest subsidy budgets.’ This would deepen regional inequalities and weaken the collective bargaining power that a common European approach is meant to create (Collin, García Bercero & McWilliams, 2026; Tagliapietra, Trasi & Sebastian, 2025).
Finally, the proposed IAA’s social logic remains too automatic. It assumes that anchoring production will anchor employment. Yet electrification changes the industry’s occupational structure, and new factories may be far from the regions losing old ones. Research on the European car industry shows that the transition can reproduce regional and social inequalities unless policy addresses who receives investment, who bears adjustment costs and who participates in decisions (Szabó & Newell, 2024). The European Trade Union Confederation (ETUC) is therefore right to call for mandatory training, worker participation and regional transition planning, not employment numbers alone (ETUC, 2026).
The proposal should not be abandoned. It should be completed. Its central insight is correct: access to the scale of the Single Market gives the EU bargaining power. That power should be used to secure outcomes rather than to build a wall. Recent assessments similarly caution that poorly calibrated origin and investment rules could delay capacity formation or distort the Single Market unless they are tied to clearer sectoral objectives (Collin, García Bercero & McWilliams, 2026).
Assessing Three Policy Options
At the present stage of the legislative debate, three policy approaches can be envisaged.
The first option is defensive localization. The EU would tighten ‘Made in EU’ rules, maintain or increase tariffs, restrict Chinese participation in public support and apply the proposed IAA’s ownership and technology conditions in their most demanding form. It offers a visible response to job losses and may create protected demand while European producers scale up.
The costs would be substantial. Strict exclusion would raise prices, reduce competitive pressure and delay capacity expansion. It would invite retaliation, while broad local-content requirements could conflict with WTO rules if they discriminated against imported goods (WTO, 1994). Protection would not guarantee innovation: firms could gain a sheltered market without closing gaps in software, batteries and production speed. Export diversion would also expose European manufacturers to stronger Chinese competition in nearby third markets (Fulton, Lons & Tsang, 2026).
This option carries a political paradox. Protection can temporarily reassure workers, but if it leads to expensive electric vehicles, weak demand and continued restructuring, populist actors will shift their argument. Brussels can then be blamed both for imposing the transition and for making it unaffordable. Evidence from manufacturing regions also cautions against assuming that one visible protective measure will settle deeper anxieties about status, employment and regional decline (Bayerlein, Kölzer & Metten, 2026; Poletti, 2026).
The second option is managed openness. The EU would retain countervailing duties and general investment-screening tools while welcoming Chinese factories case by case. Member States would remain free to negotiate investment packages, and the Commission would intervene mainly where subsidies, security risks or market distortions were evident. This approach could attract capital quickly and expand European production without the conflict generated by rigid joint-venture or technology-transfer requirements.
Managed openness is preferable to a trade war, but it is too weak for the scale of the transition. Individual Member States may compete to offer subsidies, land and tax advantages while accepting limited commitments on suppliers, research or skills. Investors could divide production across Europe in ways that maximize incentives rather than industrial coherence. A series of assembly plants would improve output statistics without necessarily strengthening European capability. The approach would also disadvantage smaller Member States and make monitoring uneven (Tagliapietra, Trasi & Sebastian, 2025).
The third option, recommended in this paper, is conditional integration. It starts from two propositions. First, Chinese investment is not inherently a threat; it can support decarbonization, competition and employment. Second, the value of an investment cannot be measured by its location alone. It should be judged by the capabilities it creates and retains in Europe.
Conditional integration would establish common EU rules for major electric-vehicle and battery projects, regardless of which Member State hosts them. Investment approval, eligibility for relevant public support and access to lead-market measures would remain available when investors make verifiable contributions to local research, skilled employment, supplier development, circularity and secure digital systems. The framework would not require firms to surrender corporate control or transfer proprietary technology. Instead, it would impose outcome-based obligations proportionate to the scale of the investment and the public support received.
This approach better balances openness and resilience. It uses the Single Market as leverage without treating investment as a zero-sum contest and aligns with proposals for a common European strategy towards Chinese EV investment (Tagliapietra, Trasi & Sebastian, 2025). Chinese firms would gain a predictable route into Europe: invest for the long term, build local capabilities and meet common standards. Europe would convert competitive pressure into learning and capacity-building rather than a sequence of trade disputes and national restrictions.
Political Feasibility on Both Sides
Conditional integration is viable only if it can be defended in domestic politics. In Europe, governments must show that openness does not mean accepting low-value assembly while research and supplier development remain elsewhere. Commitments on permanent technical jobs, paid retraining and regional supplier conversion should therefore be visible before public support is granted. This matters in industrial regions where expected decline can be as politically consequential as closures already recorded (Bayerlein, Kölzer & Metten, 2026), and it answers populist claims that trade policy protects abstract European interests while local communities absorb the costs (Poletti, 2026).
China faces a different constraint. Beijing is unlikely to accept a framework described as forced technology transfer, discriminatory localization or an anti-China ownership regime (MOFCOM, 2026a, 2026b). Chinese firms may nevertheless accept training, European R&D, supplier-development and carbon-performance commitments when these are presented as normal conditions for long-term investment and apply to all covered foreign investors. Deeper localization can then be framed as commercial adaptation rather than a political concession.
The framework should therefore privilege measurable outcomes over symbolic ownership tests. Country-neutral rules, protection of pre-existing intellectual property and a transparent route to approval make conditional integration easier to defend on both sides: Europe gains visible domestic value, while Chinese investors avoid openly punitive treatment.
Three Core Recommendations
1. Establish a European Automotive Investment Compact
The first step should be a European Automotive Investment Compact anchored in the proposed IAA framework. During the legislative negotiations, the co-legislators should strengthen Article 18 by making capability creation a mandatory element of covered EV and battery investments. In addition to the proposed employment requirement, each project should meet either the EU research-and-development condition or a strengthened supplier-development condition. The relevant legal bases are Articles 18(2)(d), 18(2)(f) and 18(3). The Commission should then use the implementing act foreseen in Article 18(5) of the proposal to establish a sector-specific verification scorecard (European Commission, 2026c).
The scorecard should test substance: technical and permanent jobs, engineering and research performed in Europe, paid training, supplier contracts and the treatment of jointly created intellectual property. An investor should not be able to meet formal ownership conditions while contributing little to learning, nor should a project be rejected merely because a joint venture is commercially inappropriate.
Technology cooperation must be handled carefully. The Compact should recognize paid licensing, joint research centers, jointly created intellectual property, testing facilities and university partnerships, while protecting pre-existing rights. Europe should seek competence rather than ownership of every foreign technology. Supplier conditions should be framed as verifiable value-chain development rather than a blanket obligation to purchase domestic goods, reducing WTO risk (WTO, 1994).
2. Attach a Skills and Regional Transition Covenant to Major Investments
The second recommendation is a Skills and Regional Transition Covenant. The Commission’s March 2026 IAA proposal would require at least half of the workforce in covered investments to be EU workers across occupational categories, accompanied by training. A qualitative plan should also identify the occupations created, qualifications required, share of permanent positions and routes for displaced automotive workers to enter them (European Commission, 2026c).
Investors should partner with vocational schools, universities and recognized training providers. Training should occur during paid working time and extend to affected supplier firms. Where projects receive significant public support, unions and worker representatives should participate in design and monitoring, preventing Europe from gaining mainly assembly jobs while high-value engineering remains elsewhere (ETUC, 2026).
The Commission should also favor projects linked to regions undergoing automotive restructuring, where infrastructure and skills conditions permit. Industrial Acceleration Areas should be tied to regional development, clean-energy access and supplier conversion rather than treated as deregulatory enclaves. A new battery plant does not automatically compensate for a distant components-factory closure; the connection must be designed and funded (Szabó & Newell, 2024).
3. Create a European Automotive Transition Financing Window
The third recommendation is a ring-fenced European Automotive Transition Financing Window under existing EU instruments, coordinated by the Commission and the European Investment Bank. The proposed IAA relies on synergies across the Innovation Fund, InvestEU, Horizon Europe, the Connecting Europe Facility and cohesion funds rather than a new spending envelope (European Commission, 2026c). The Commission should begin preparing a coordinated pilot in 2027, with implementation to follow once the IAA’s legal basis and the necessary budgetary arrangements are in place. In the longer term, the financing window could be incorporated into the European Competitiveness Fund if that instrument is established under the 2028-2034 Multiannual Financial Framework.
The window should finance shared European public goods rather than routine vehicle production: supplier conversion, battery recycling, testing facilities, worker training, grid connections and first-of-a-kind manufacturing. Cross-border value chains and shared research should receive priority over isolated plants with limited spillovers.
National aid could continue, but major packages should be listed on a common transparency platform with public contributions, expected jobs, training, supplier contracts and environmental performance. Investors would then face one European framework rather than a patchwork of national bargains, accepting consistent obligations in return for access to finance and lead markets.
Two Enabling Measures
A Software, Data and Innovation Pillar
The proposed IAA’s emphasis on manufacturing is understandable, but the competitive frontier is shifting towards software-defined vehicles, autonomous-driving systems, battery management, digital services and data. Europe could localize vehicle assembly while remaining dependent on external operating systems and data architectures. That would replace one form of dependence with another (European Commission, 2025; van Wieringen, 2024).
The Commission’s automotive action plan already points towards testing zones, connected and autonomous vehicle alliances and public-private research. These initiatives should be linked to the proposed IAA investment regime. Major projects should comply with EU cybersecurity, data-protection and competition rules; critical software updates and remote-control functions should face independent security auditing; and access to vehicle data generated in Europe should be governed by transparent legal rules (European Commission, 2025).
This pillar should remain open to Chinese firms. Exclusion from European research ecosystems would slow learning and encourage incompatible standards. Participation, however, should depend on interoperability, auditability and compliance with EU data governance. Joint testing facilities could allow European and Chinese firms to develop products for the EU market while ensuring that safety, cybersecurity and data standards are verified in Europe.
A Structured EU-China Implementation Dialogue
The second enabling measure is a structured EU-China implementation dialogue. It should not replace enforcement or offer China exemptions unavailable to others. A working group involving DG TRADE, DG GROW, relevant Chinese ministries, industry and social partners should instead reduce uncertainty during the proposed IAA’s legislative and implementation phases.
The agenda should cover Union-origin calculations, joint research and intellectual property, recognition of training expenditure, reporting and carbon accounting. It could also examine WTO-compatible alternatives to duties, including price undertakings where they address the subsidization identified by the Commission (European Commission, 2026b). Non-confidential guidance should be published for firms on both sides.
Reciprocity should remain on the agenda, but through defined sectors and measurable commitments rather than a demand that every market opens simultaneously. Progress on procurement, standards and research partnerships could be linked to greater confidence in implementation of the proposed IAA. The aim is managed bargaining, not rhetorical escalation.
Risks and Safeguards
Conditional integration will not eliminate conflict. China may challenge provisions of the proposed IAA or retaliate against European firms. The EU should prepare sector-specific contingencies, diversify critical inputs and use trade-defense instruments when evidence supports them. Rules should remain country-neutral and rest on transparent market-share, security and value-creation criteria, making them easier to defend legally (European Commission, 2026c; WTO, 1994).
Symbolic compliance is another risk. Research centers or training programmes may remain small relative to the investment. Approval decisions should therefore include measurable milestones and five-year reporting on permanent jobs, paid training, R&D, jointly developed intellectual property, supplier contracts, recycled content and carbon performance. Failure to meet commitments should trigger proportionate recovery of support or revised approval conditions.
Industrial policy can also become detached from affordability. Consumers cannot carry the full adjustment cost through higher vehicle prices. The Commission should preserve competition, expand charging infrastructure and target demand measures towards small and affordable EVs. Resilience will not be politically sustainable if electric mobility becomes a premium product (European Commission, 2025; IEA, 2026).
Finally, the proposed IAA should not be sold as a victory over China. Such language would strengthen nationalist narratives on both sides. It should be presented as a rule for all major investors: access to public support and the Single Market comes with responsibilities to workers, regions, innovation and climate goals. Visible local benefits are the strongest answer to populist claims that trade and decarbonization serve only distant institutions and large corporations (Poletti, 2026).
Conclusion
The European automotive transition cannot be secured by tariffs alone. Nor can Europe assume that any factory built within its borders will automatically deliver resilience. The decisive issue is the quality of industrial integration.
Defensive localization would protect selected producers but risk higher costs, retaliation and technological complacency. Managed openness would attract capital but leave Member States competing for investments that may create limited European spillovers. Conditional integration offers a more durable route. It welcomes Chinese electric-vehicle and battery investment when that investment creates capabilities Europe can retain skilled jobs, research, suppliers, secure digital systems, circular production and regional development.
The proposed Industrial Accelerator Act provides the beginnings of such a framework, but it needs clearer priorities, a realistic financing channel and stronger links to skills, software and regional policy. A European Automotive Investment Compact would turn broad legal conditions into predictable sectoral rules. A Skills and Regional Transition Covenantwould connect industrial location to social legitimacy. A European Automotive Transition Financing Window would limit fiscal fragmentation, while the two enabling measures would address future technological competition and reduce uncertainty without weakening enforcement.
Europe should not ask Chinese firms to become European. It should ask every major investor benefiting from the European market to make a measurable contribution to European capacity. The strategic shift is from market access to co-development, and from the location of output to the creation of capability. Implemented in that form, the proposed IAA could do more than manage a trade dispute. It could support decarbonization, democratic stability and a more balanced EU-China economic relationship.
(*) This policy paper is based on research conducted by the ECPS Summer School 2026 China Team during the case competition on the side of Summer School titled “Europe Between Oceans: The Future of EU Trade Between the Atlantic and the Indo-Pacific,” held on July 6-10, 2026.
References
Ban, C. & Šćepanović, V. (2026). ‘Das Auto and the Second China Shock: Industrial Policy and the Disruption of Technological Incumbency.’ Politics and Governance, 14. https://doi.org/10.17645/pag.11456
Bayerlein, M., Kölzer, J. & Metten, A. (2026). ‘Industrial Employment and Populism in Germany – Exploring the Effect of Actual and Looming Decline.’ Politische Vierteljahresschrift, 67, 163-194. https://doi.org/10.1007/s11615-025-00606-w
European Commission (2024). Commission Implementing Regulation (EU) 2024/2754 of 29 October 2024 Imposing a Definitive Countervailing Duty on Imports of New Battery Electric Vehicles Originating in the People’s Republic of China. Official Journal of the European Union. https://eur-lex.europa.eu/eli/reg_impl/2024/2754/oj/eng
European Commission (2026c). Proposal for a Regulation Establishing a Framework of Measures for the Acceleration of Industrial Capacity and Decarbonisation in Strategic Sectors (Industrial Accelerator Act), COM(2026) 100, 4 March 2026. https://eur-lex.europa.eu/legal-content/EN/TXT/?uri=CELEX:52026PC0100
International Energy Agency (IEA) (2026). Global EV Outlook 2026: Manufacturing and Trade. Paris: IEA. https://www.iea.org/reports/global-ev-outlook-2026/manufacturing-and-trade
Poletti, A. (2026). “’EU-US-China Trade Relations.” In: M. Riddervold, G. Rosén & J. R. Greenberg (eds), Populism and the Future of Transatlantic Relations: Challenges and Policy Options. European Center for Populism Studies. https://doi.org/10.55271/rp00127
Szabó, J. & Newell, P. (2024). “Driving towards a Just Transition? The Case of the European Car Industry.” Energy Research & Social Science, 115, 103649. https://doi.org/10.1016/j.erss.2024.103649
Professor Ibrahim Ozturk examines the deeper political economy behind The Economist’s recent critique of Nobel laureate Daron Acemoglu, arguing that the dispute reaches far beyond disagreements over institutional theory or AI productivity. He situates the controversy within a systemic crisis marked by inequality, weakened labor, technological concentration, declining governing capacity, and the erosion of liberal democracy’s social foundations. Drawing on Acemoglu alongside Polanyi, Rodrik, Stiglitz, Rawls, and Piketty, Professor Ozturk argues that technological progress is inherently political: institutions and power determine who directs innovation and captures its gains. The commentary contends that Acemoglu’s most consequential challenge is his insistence that markets cannot discipline concentrations of power they have themselves created—and asks whether the coming systemic reset will genuinely redistribute power or merely reproduce existing winners under a new institutional settlement.
The Economist’s attack on Nobel laureate in economics Daron Acemoglu is more than an academic dispute. It exposes a deeper struggle over who will govern technological change, who will bear the costs of systemic reform, and whether liberal democracy can discipline concentrated economic power. Acemoglu’s real offense is not pessimism. It is his insistence that technological progress is a political choice, that liberal democracy cannot survive without shared prosperity, and that markets cannot discipline concentrations of power that they have themselves created. The dispute is therefore larger than one economist or one disputed estimate. At stake is whether the coming systemic reset will redistribute power as well as losses—or merely reshuffle the cards while leaving ownership of the table in the same hands.
The Political Economy Behind the Acemoglu Controversy
A growing body of research shows that the contemporary crisis of liberal democracy cannot be explained solely by the personalities of populist leaders or the supposed irrationality of their supporters. Its deeper sources lie in systemic disruptions caused largely by the corporate capitalism of the neoliberal Washington consensus that came with unregulated hyper-globalization, widening inequality, weakened labor, financial instability, regional decline, technological concentration, and the diminishing capacity of elected governments to protect citizens from externally generated shocks.
This interpretation belongs to a substantial political economy tradition. Karl Polanyi argued that attempts to disembed markets from society eventually provoke a protective countermovement. But that countermovement need not always be democratic or progressive. If legitimate democratic institutions cannot provide social protection, nationalism, protectionism, and authoritarian populism may offer it.
Dani Rodrik similarly anticipated that advanced economic globalization would provoke a political backlash. Trade, capital mobility and global production networks generated aggregate gains, but the losses were geographically concentrated, socially persistent and inadequately compensated. In Rodrik’s formulation, the problem was not globalization alone but “hyper-globalization”: the subordination of domestic economic and social arrangements to the requirements of international markets.
Joseph Stiglitz has approached the same problem through the failures of neoliberalism. Deregulation, regressive taxation, weakened public services, and the political power of concentrated wealth did not produce the competitive market order that their advocates promised. They produced what Stiglitz calls a crisis of capitalism and democracy. Four decades of policies favoring capital over labor did not remove the state from the economy; they reorganized state power around particular interests.
In my recent works, I argued that unmanaged globalization creates political space for populists, who then weaken the autonomous institutions required for democratic correction. Turkey under Erdogan shows how institutional capture can insulate authoritarian populism from economic failure. Brazil under Lula, by contrast, demonstrates that a broad coalition can defeat an authoritarian-populist project, although its media, patronage and identity networks may survive electoral defeat. My comparative analysis of Lula and Erdogan therefore suggests that democracy must do more than remove populist leaders; it must rebuild the social and economic foundations of representation.
Reverse Convergence and the Crisis of the Western Model
I have placed these national cases within a broader process that I call “reverse convergence.” The post-Cold War expectation was that China’s integration into global capitalism would gradually make it more liberal, more transparent, and more institutionally similar to the democratic West. Markets would create an independent middle class; international integration would strengthen the rule of law; and economic modernization would ultimately generate political liberalization.
That prediction proved deeply misleading. China incorporated markets, global trade, multinational investment, and advanced technology without surrendering authoritarian political control. At the same time, the United States and parts of Europe began adopting practices once associated with illiberal systems: economic nationalism, strategic protectionism, industrial subsidies tied to geopolitical objectives, expanding surveillance, executive discretion, and restrictions on technological exchange.
China did not simply converge toward the West. In important respects, the West began to converge toward China. As I argued in “Capitalist Disruptions and the Democratic Retreat,” this reciprocal movement is rooted in the systemic crisis of corporate capitalism. Liberal regimes are adopting illiberal instruments, while authoritarian regimes maintain repression and selectively integrate into global markets. The institutional and normative distance between the two systems is narrowing from both sides.
This does not mean that China and Western democracies have become identical. Political pluralism, judicial independence, civil liberties, and electoral competition still create fundamental distinctions. Reverse convergence describes a direction of movement, not a completed state. Its warning is that market integration alone does not automatically liberalize authoritarian regimes, while economic insecurity and geopolitical rivalry may progressively illiberalize democratic ones.
The empirical literature on the so-called China Shock strengthens this argument. David Autor, David Dorn and Gordon Hanson showed that communities exposed to Chinese import competition experienced persistent employment and wage losses rather than the rapid adjustment predicted by standard trade models. Their subsequent research connected trade exposure with greater political polarization. These findings do not prove that globalization alone caused Trumpism. They do demonstrate that the distributional and geographical effects of trade cannot be treated as temporary deviations from an otherwise frictionless adjustment process.
Rodrik’s distinction between the demand and supply sides of populism is crucial here. Economic shocks generate insecurity and resentment, but political entrepreneurs decide how these grievances are interpreted. The anger may be directed against financial elites, multinational corporations, and inequality, or diverted towards migrants, minorities, and external enemies. Material dislocation and cultural politics are not mutually exclusive explanations; economic insecurity can be translated into identity conflict.
The transformation of Western party systems reinforces the problem. Thomas Piketty, Amory Gethin and Clara Martínez-Toledano document the emergence of a “Brahmin Left” representing highly educated voters and a “Merchant Right” representing high-income and wealth-owning groups. Sections of the working and lower-middle classes increasingly feel politically unrepresented. They face a cultural elite on one side and an economic elite on the other.
This helps explain why citizens experiencing abandonment may turn to leaders whose economic programs do not objectively serve them. Populism offers what technocratic liberalism no longer provides: a language of belonging, recognition and political conflict. Its solutions may be false and its leadership authoritarian, but its diagnosis begins with a real representational void.
The Global Policy Machine Is Running Out of Room
The world economy is now entering a phase in which national policy responses increasingly neutralize one another. Japan is caught between enormous accumulated public debt, rising financing costs, demographic contraction and a central bank whose policy space has narrowed. The United States combines structural fiscal deficits and high debt-service costs with protectionism and an increasingly explicit effort to preserve technological supremacy. Europe wants greater strategic autonomy, military capacity, green transformation and social protection, but confronts weak growth, high energy costs, fragmented capital markets and restrictive fiscal politics.
Each major economy is trying to transfer part of the adjustment burden elsewhere. The United States uses tariffs, industrial subsidies and the structural power of the dollar. China responds through production scale, export penetration and state-supported technological upgrading. Europe turns to defensive regulation and industrial policy. Emerging economies compete for investment through tax concessions, cheap labor, suppressed wages and regulatory exemptions.
What appears rational for each country separately becomes contradictory at the systemic level. Everyone wants to export more, protect strategic industries, attract capital, subsidize domestic production and prevent unemployment. Not everyone can do so simultaneously.
Monetary policy confronts similar limits. High interest rates may suppress inflation but intensify debt-service pressures, weaken investment and expose financial fragilities. Lower rates may sustain asset prices and indebted governments but revive inflation, encourage leverage and postpone restructuring. Fiscal expansion supports demand but confronts anxious bond markets. Austerity reassures creditors while weakening social legitimacy and accelerating political radicalization.
The world is approaching a point where conventional policies no longer resolve problems. They transfer them across time, borders and social classes. When these contradictions can no longer be postponed, governments will be tempted to reshuffle the cards: recognize losses, rescue selected institutions and transfer the bill to those least able to resist. Workers, taxpayers, small savers, pensioners and younger generations will be required to absorb the consequences of decisions they did not make. Without structural reform, the next major crisis will not be merely another business-cycle downturn. It may become a simultaneous crisis of distribution, political legitimacy and democratic representation.
The questions Acemoglu now addresses are therefore the real questions confronting liberal democracy: Why do governments change while economic direction remains largely fixed? Why can political systems identify their crises yet remain unable to reform the structures that reproduce them? And why does electoral alternation so often rotate the administrators of the system without altering the distribution of economic power, the direction of technological change or the mechanisms through which the costs of crisis are transferred?
United Kingdom offers a revealing example. Prime ministers and governing parties change, yet weak productivity, regional inequality, deteriorating public services, housing shortages, chronic underinvestment and the unresolved consequences of Brexit remain. Political alternation survives, but transformative capacity has weakened. Elections change the system’s managers without necessarily changing its economic direction. Acemoglu is searching, at his own analytical scale, for an explanation of this crisis of reform capacity and for a route beyond it.
This is precisely where The Economist occupies a paradoxical position. It presents itself as an unsentimental analyst of political and economic failure, yet its ideological framework often prevents the causal chain from being followed back to the underlying distribution of power. Governments fail, voters become irrational, institutions deteriorate, and populists advance; meanwhile, the ownership structures, fiscal privileges, financial interests, and technological concentrations that restrict meaningful reform remain less visible. Acemoglu’s recent work is disturbing because it begins to turn the analytical finger towards these protected centers of power.
A Critique with Two Very Different Layers
On August 17th 2026, The Economist published an unusually personal attack under the headline “The world’s most influential economist is oddly unconvincing.” The article acknowledges that Acemoglu is exceptionally productive, intellectually formidable, and generous towards younger scholars. It then devotes the rest of its space to questioning whether his reputation at the summit of the economics profession is justified.
This is a legitimate question to ask about any celebrated scholar, including a Nobel laureate. Acemoglu’s empirical research, institutional theory and estimates of AI’s productivity effects are not beyond criticism. The history of economics is full of influential theories that later proved incomplete, context-dependent or empirically fragile. Yet The Economist’s intervention does not read like a conventional scholarly assessment. Its tone, timing and structure suggest that something else is at stake. For instance, it moves from technical disagreements over colonial mortality data to dismissive judgments about Acemoglu’s political analysis, his account of technological change and his support for pro-worker AI. It does not merely claim that some of his estimates may be wrong. It seeks to diminish the intellectual authority he draws on to challenge today’s concentration of technological and economic power.
The article combines two fundamentally different kinds of criticism. The first is methodological. It revisits the famous 2001 paper by Acemoglu, Simon Johnson and James Robinson on the colonial origins of comparative development. Their argument—those different colonial environments produced different institutional arrangements whose effects persisted—became foundational to contemporary institutional economics. The Nobel Committee recognized the three economists in 2024 “for studies of how institutions are formed and affect prosperity.”
The settler-mortality data used in their original paper have genuinely been disputed. David Albouy questioned observations transferred between territories, the comparability of historical mortality figures, and the robustness of the instrumental-variable estimates. Acemoglu, Johnson and Robinson responded that Albouy’s conclusions depended on removing much of Latin America and Africa from the sample and adding a questionably coded campaign dummy. Their formal reply was published alongside Albouy’s critique.
These are substantial questions, and The Economist is justified in discussing them. Yet the limits of the research program extend beyond one dataset. Adam Przeworski questioned whether endogenous institutions can coherently be treated as the primary cause of development; Edward Glaeser and his co-authors argued that human capital and prior development may themselves generate institutional improvement; and Gareth Austin showed how the reversal-of-fortune thesis compresses African history and underweights colonial political economy and local trajectories. More broadly, the inclusive–extractive distinction risks becoming an ex-post classification if imperial power, war, class conflict, external intervention and variation within countries receive insufficient weight. These objections limit the framework’s claim to a unified explanation; they do not render institutional analysis worthless.
The paper’s influence also extends beyond its precise coefficient. It helped shift development economics away from treating markets, capital accumulation, and technological diffusion as processes operating independently of political power. Institutions determine whose property is protected, whose contracts are enforced, who receives education, who controls the state, and who can organize collectively.
The second layer of The Economist’s critique goes beyond identification strategies or historical evidence and dismisses Acemoglu’s ideas as obvious, gloomy, or insufficiently adventurous. His argument that Trump increases executive power by destroying constraining institutions is met with “Well, obviously.” The magazine’s article characterizes his idea of pro-worker AI as attractive but self-evident. It presents his concern about the social direction of technology as pessimism.
This is not technical refutation. It is rhetorical minimization. A familiar method is at work: acknowledge that an argument is correct, then declare it too obvious to matter. Yet many of the most consequential truths in political economy appear obvious only after somebody has identified their mechanisms and shown why prevailing institutions systematically violate them. If it is obvious that AI should complement workers rather than displace them, why do corporate incentives and tax systems so often favor automation? If it is obvious that executive power must be constrained, why are liberal democracies progressively normalizing emergency powers, politicized administration, and rule by decree? If shared prosperity is an obvious foundation of democratic stability, why has it been so consistently subordinated to asset-price appreciation and capital mobility?
A Magazine Contradicting Its Own Acemoglu Archive
The severity of the 2026 verdict is striking because it does not grow naturally out of The Economist’s own record. When Acemoglu and Robinson were turning a partly Western-centered institutional narrative into a global theory—precisely when its circularity, historical compression and treatment of colonial power most required sustained scrutiny—the magazine largely welcomed the framework. It insisted that “institutions matter, a lot,” reported favorably on research connecting democracy and growth, and applied the Why Nations Fail framework to rebuilding fragile states. Its archive was not uncritical, but it was serious and constructive. The latest article abruptly converts familiar disputes into a personalized verdict on whether Acemoglu deserves his standing at the apex of economics.
Archive searches are imperfect, especially across changed URLs and print editions. The conservative claim is therefore not an exact lifetime total but at least ten identifiable, substantial Economist articles between 2012 and 2026 in which Acemoglu or his co-authored work is central. Passing citations, daily briefings, and Economist events would raise the broader count.
The inconsistency is not that a magazine changed its mind; serious publications should do so when evidence changes. The new verdict neither identifies decisive new evidence nor explains the editorial reversal. Nor has The Economist stopped treating Acemoglu as authoritative: its Antitrust Summit agenda schedules him for a discussion with the magazine on October 28th, 2026. The same institution can market his authority in one venue while attempting to deflate it in another. That tension deserves acknowledgment.
Institutions: Tautology or An Analysis of Power?
Acemoglu’s institutional theory does face a genuine analytical challenge. If successful countries are said to possess “inclusive institutions” and unsuccessful countries “extractive institutions,” there is a risk of circular reasoning. Inclusive institutions produce prosperity, while prosperity becomes evidence that institutions were inclusive.
Tyler Cowen and other critics have questioned whether institutional change is sometimes explained by reference to earlier institutional change, producing an infinite regress. Critics also point to China: how can a politically authoritarian and plausibly extractive system generate decades of extraordinary growth? These objections should be taken seriously. Institutions cannot become a residual category covering laws, norms, culture, political power, state capacity, and every historical event not explained elsewhere. A theory that explains everything after the event may predict very little before it.
Yet China does not automatically disprove Acemoglu’s argument. His claim is not that extractive systems cannot grow. Such regimes can mobilize resources, import technology, suppress consumption, direct credit, and achieve rapid catch-up. The stronger claim is that innovation-driven, broadly shared prosperity becomes harder to sustain when political power remains concentrated and accountability weak. China therefore represents less a decisive refutation than an unresolved test. Its future trajectory will depend on whether centralized control can coexist with innovation, demographic transition, rising debt, entrepreneurial autonomy and the increasingly complex information requirements of an advanced economy.
More importantly, institutional analysis becomes far less tautological when institutions are understood as structured distributions of power. Institutions establish who can veto policy, organize labor, own productive assets, finance political campaigns, control information, and impose losses on others. They are not merely “good rules” producing good outcomes. They are settlements among social forces. This interpretation connects Acemoglu to an older political-economy tradition rather than separating him from it. Polanyi’s embedded markets, Rawls’s fair value of political liberty, Stiglitz’s progressive capitalism and Rodrik’s productivist agenda all ask how economic power can be made compatible with democratic citizenship.
John Rawls insisted that political liberties must possess not only formal existence but “fair value.” Citizens must have a substantively comparable opportunity to influence political outcomes. His later preference for a property-owning democracy over conventional welfare-state capitalism was based partly on the fear that wealth concentrated in a few hands would dominate politics. This is no longer an abstract philosophical concern. Martin Gilens demonstrated that policy outcomes in the United States are far more responsive to affluent citizens than to those on middle or lower incomes. When unequal economic power becomes unequal political influence, liberal democracy may retain elections while losing substantive representation.
The “Old Acemoglu” and the “New Acemoglu”
Some defenders of Acemoglu have interpreted The Economist’s article as retaliation by “the system” against an economist who has become “dangerously radical.” An ideological reaction may be at work, but this interpretation should not be exaggerated.
As a good student of institutional economics, I would argue that Acemoglu is not a socialist revolutionary. He does not advocate abolishing markets or private property. He does not romanticize Soviet planning, Maoism, or Chinese authoritarian state capitalism. His project is reformist: to rescue liberal democracy from the consequences of its political and economic degeneration. His new book, What Happened to Liberal Democracy?, makes this explicit. Acemoglu argues that liberal democracy flourished when it combined individual freedom, political participation, and shared prosperity. It lost legitimacy when post-industrial liberalism abandoned that settlement, let economic and educational elites detach from the rest of society, and failed to manage the disruptions caused by globalization and digital technology. His alternative is “working-class liberalism”: a democratic order centered on shared prosperity, empowered communities, human dignity, and a wider range of legitimate social values. The book’s central argument is the reconstruction of liberalism, not its destruction.
Acemoglu’s criticism of sections of the contemporary left is also important. He argues that progressive politics became too detached from working-class economic interests and too closely associated with highly educated metropolitan groups. That claim corresponds strikingly with Piketty’s “Brahmin Left” analysis. The cultural and educational elite may support minority rights and cosmopolitan values while remaining insufficiently attentive to labor power, regional decline, and economic insecurity. In this respect, Acemoglu is closer to Rawlsian social liberalism or renovated social democracy than to anti-capitalism. Markets should remain, but they must be embedded in democratic institutions. Technology should advance, but society must influence its direction. Capital should invest and innovate, but concentrated private power should not colonize politics, knowledge and public life.
Precisely because this is not a revolutionary program, it poses an uncomfortable challenge to defenders of the status quo. Acemoglu cannot easily be dismissed as an enemy of capitalism. He criticizes capitalism in the language of productivity, competition, opportunity, and liberal democracy itself. His message is not that liberal democracy failed because its enemies defeated it. It is that liberalism damaged its own social foundations.
This recasts the central democratic question. Are liberal democracies being destroyed from outside by populists, or hollowed out from inside by the concentration, dependency and inequality generated under economic liberalism? The alternatives are false if treated as mutually exclusive. Populist leaders are real agents of institutional destruction, but they also accelerate a prior internal decay. When markets concentrate wealth, governments lose governing capacity, work loses bargaining power, and citizens experience elections without economic agency, the constitutional shell remains while democratic substance thins. Trump, Bolsonaro and Erdogan did not invent this vulnerability; they organized and weaponized it. Lula’s return shows that electoral correction is possible, but also that removing a populist is not the same as rebuilding democracy’s social foundations.
The Reform Question Neoliberalism Avoids
For four decades, the dominant policy framework promised that trade liberalization, deregulation, financial deepening, labor-market flexibility and technological innovation would increase aggregate prosperity. Distributional losses could supposedly be handled afterward through education, worker mobility and limited fiscal compensation.
The promised compensation was frequently inadequate or never arrived. Productivity gains were distributed unevenly. Trade unions weakened. Labor lost bargaining power. Financialization expanded. Market and wealth concentration increased. Tax systems often treated capital gains, inherited wealth and multinational profits more favorably than ordinary labor income.
Stiglitz describes the necessary alternative as progressive capitalism: markets combined with strong public institutions, competition, social investment and limits on rent extraction. Rodrik’s “productivism” similarly shifts attention from redistribution after-market outcomes to the organization of production itself. Firms’ investment, employment, and innovation decisions reproduce poverty, inequality, and exclusion daily. Waiting to repair them afterward is both economically inefficient and politically destabilizing.
This is where Acemoglu’s pro-worker technology argument acquires significance. The distributional consequences of technology should be addressed when technologies are selected, designed, and deployed—not only after workers have been displaced.
Technology Does Not Choose Its Own Direction
The Economist presents Power and Progress, written by Acemoglu and Simon Johnson, as an excessively gloomy history of technological change. It responds that technological progress has made the average person vastly richer than people living before the Industrial Revolution.
That statement is true, but it does not answer Acemoglu’s argument. Acemoglu and Johnson do not claim that technology has produced no progress. Their central proposition is that the benefits of innovation are neither automatic nor naturally distributed. Technology creates possibilities; institutions, political organization, and bargaining power determine how those possibilities are deployed and who captures the gains.The MIT summary of Power and Progress states the issue clearly: technological advances can become empowering and democratizing, but not if decisive choices remain concentrated in the hands of a few technology leaders.
The Industrial Revolution eventually raised living standards, but its early decades also produced brutal factory discipline, child labor, unsafe cities, and the destruction of established livelihoods. The eventual social gains were not created by machinery alone. Labor organization, public health, education, political enfranchisement, social insurance, competition policy, and progressive taxation mediated them.
Acemoglu’s critics frequently collapse two different propositions: i) Technology can increase aggregate productivity. ii) Technology will automatically produce broadly shared prosperity.
The first can be true while the second remains false.
The same distinction appears in the economic literature on automation. Acemoglu and Pascual Restrepo distinguish between a displacement effect, through which machines take over tasks previously performed by labor, and a reinstatement effect, through which technological change creates new tasks in which human labor has a comparative advantage. Automation can raise productivity while reducing labor’s share of income if the creation of new human tasks is too weak. The question is therefore not “technology or no technology.” It is what kind of technological trajectory societies encourage.
AI, Labor and Concentrated Power
Photo: Dreamstime.
Artificial intelligence makes this problem more urgent because AI is not merely another machine. It can reorganize the production of knowledge, monitor workers, shape communication, automate administrative judgment and concentrate informational power in companies controlling data, cloud capacity, advanced chips and foundation models.
An AI system may increase corporate productivity while reducing labor’s bargaining power. It may improve prediction while enabling pervasive surveillance. It may create useful information while degrading the shared epistemic environment required for democratic deliberation. It may create new occupations in aggregate while destroying the career ladders through which younger workers acquire expertise.
The International Labor Organization (ILO) finds that transformation and augmentation are more likely than the immediate disappearance of entire occupations. This supports neither technological utopianism nor apocalyptic unemployment forecasts. It supports Acemoglu’s emphasis on institutional choices: outcomes depend on how tasks are reorganized, whether workers participate in deployment decisions, and who captures the productivity gains.
The competition problem is equally serious. An OECD assessment identifies powerful concentration pressures arising from access to computing capacity, data and specialized skills, along with first-mover advantages and vertical integration. In other words, concern about AI oligopoly is not merely an ideological suspicion Acemoglu entertains. It is now a central competition-policy problem.
This connects Acemoglu’s position with Shoshana Zuboff’s concept of surveillance capitalism. Digital business models do not simply sell services. They extract behavioral data, convert human experience into a commercial resource, and acquire capacities to predict or influence behavior. This produces not only market power but a form of private authority over information and social coordination.
The issue is therefore larger than monopoly pricing. When a handful of corporations control the infrastructures through which citizens communicate, work, acquire knowledge and participate in politics, economic concentration becomes constitutional power.
Is Acemoglu Too Pessimistic About AI Productivity?
Here, The Economist has a legitimate point. Acemoglu’s 2024 paper estimated that AI would generate only modest productivity gains over the following decade—no more than approximately 0.66% in total factor productivity under its main assumptions. The calculation was deliberately conservative. It used a task-based model, focused on tasks that could plausibly be automated or assisted, and excluded some speculative future applications. Acemoglu subsequently acknowledged that he did not fully anticipate the speed of agentic AI and may have underestimated its applications in scientific research. That is an important concession. AI may accelerate software development, experimentation, materials science, drug discovery, organizational coordination and decision-making. Agentic systems can combine reasoning, memory, planning and external tools in ways not captured by earlier estimates. If these complementary innovations scale rapidly, Acemoglu’s original productivity estimate may prove too low.
But this argues for revising the quantitative estimate, not abandoning his political economy. Indeed, faster AI progress makes his institutional concerns more important. If AI were only a marginal productivity instrument, its concentration in a few corporations would matter less. If it becomes a general-purpose infrastructure governing production, knowledge and communication, democratic oversight becomes indispensable.
There is also an asymmetry in the dominant technology debate. AI firms and their investors routinely make spectacular claims about productivity, employment and scientific transformation. These claims influence valuations, infrastructure investment, electricity policy, tax incentives and public subsidies. Yet skepticism toward commercially driven forecasts is treated as ideological pessimism, while AI executives’ optimistic claims are presented as neutral technological expertise.
The people predicting an inevitable AI revolution are often the same people raising capital, demanding regulatory exemptions and accumulating political influence from that expectation. Injecting realism into these forecasts is not hostility towards technology. It is an elementary requirement of political economy.
Who Is the “We” That Should Steer AI?
Editorial independence is not the same as institutional neutrality. The magazine’s institutional setting must be discussed with precision. The Economist Group has formal safeguards for editorial independence, including independent trustees charged with protecting the publication’s character and preventing control by any single interest. Those safeguards matter. Yet editorial independence—a prohibition on owners dictating the line—is not the same as institutional neutrality or social distance from the economic sectors under scrutiny.
The Group’s own board disclosures show an unusually dense overlap among media governance, finance, ownership and technology.
Group chair Paul Deighton also chairs Goldman Sachs International and Goldman Sachs International Bank.
Mustafa Suleyman, chief executive of Microsoft AI, has served as a non-executive director of the Group since 2019 and sits on its technology investment committee.
Suzanne Heywood is chief operating officer of Exor—the Group’s largest shareholder—and also serves on that committee.
Diego Piacentini, another committee member, previously held senior roles at Amazon and Apple.
Editor-in-chief Zanny Minton Beddoes is herself a member of the Group board.
The commercial adjacency extends to AI. The October 2025 launch announcement for Economist Insider, the premium video product, said the launch was “supported by Claude—the AI for problem solvers.” It is safer to call Anthropic/Claude the disclosed launch supporter than to infer control over editorial content. The distinction matters: sponsorship or commercial support creates a relationship readers may reasonably examine, but it does not establish that a sponsor selected an article or dictated its conclusions.
Historical board links reinforce the point about proximity, not conspiracy. Eric Schmidt, then executive chairman of Alphabet, left the Group board in 2015. The relevant inference is limited: the publication’s governance network has long overlapped with the commanding heights of technology and finance. It would be wrong to leap from that fact to a claim of editorial instruction. It would be equally naïve to treat institutional location as irrelevant to which assumptions appear normal, which reforms seem excessive and which concentrations of power receive the benefit of the doubt.
No publicly available evidence establishes that Microsoft, Goldman Sachs, Exor, Anthropic or any board member commissioned, edited or approved the August 2026 attack on Acemoglu. This essay does not allege such intervention. Its narrower claim is that the magazine’s authority should not be confused with a view from nowhere. Formal editorial autonomy can coexist with a governing and commercial ecosystem whose members share exposure to the technologies, financial structures and ownership interests Acemoglu wants democratic politics to discipline.
This institutional proximity becomes more consequential when The Economist moves from analysis to explicit policy advocacy. Only three days after attacking Acemoglu’s critique of concentrated technological power, the magazine published a leader declaring that Britain would be “bonkers to ditch Palantir,” thereby urging the government not to exercise the break clause in Palantir’s £330m NHS data-platform contract. The Palantir leader was unrelated to Anthropic’s sponsorship, and no evidence shows Palantir commissioned or influenced it. Nevertheless, it was an unmistakable editorial intervention in favor of maintaining a major public-sector relationship with a controversial American technology contractor—even after a parliamentary committee had warned of vendor lock-in and described Britain’s dependence on Palantir as an “unacceptable point of weakness.” The juxtaposition is difficult to ignore: The Economist dismisses Acemoglu’s warnings about concentrated technological power as gloomy or obvious while deploying its own institutional voice to defend precisely the kind of state–technology dependency his political economy asks democratic societies to scrutinize.
The Economist asks a fair question about Acemoglu’s demand that “we” steer AI in a pro-human direction. Who exactly constitutes this “we”? Governments can be captured. Regulators may lack technical expertise. Trade unions do not represent everyone. Expert committees can become unaccountable. National regulation may encourage investment to migrate towards more permissive jurisdictions. “Pro-worker AI” is not a self-executing program. But these difficulties do not justify leaving technological direction to the market. Markets do not remove political choice; they transfer decision-making to corporate executives, investors, platform owners and venture capital funds.
The absence of democratic governance is not neutrality. It is private governance. The real question is not whether somebody will steer AI. Somebody already does. The question is whether its direction will be determined exclusively by profitability, labor substitution, data extraction and market domination—or also by public purposes such as better employment, education, health care, scientific discovery and democratic resilience.
A credible pro-human AI agenda would therefore require more than a slogan. It would include competition policy, interoperability, public-interest access to computing infrastructure, public research funding, reform of tax incentives that favor automation, worker participation in workplace deployment, limits on algorithmic surveillance, and transparency in high-stakes automated decisions. Acemoglu’s prescriptions may be incomplete. Incompleteness invites us to develop the program, not to return decision-making to the oligopolies creating the problem.
Meanwhile, no publicly available evidence shows that The Economist’s article was commissioned by a technology company or produced as part of a coordinated campaign. Calling it a purchased attack without evidence would weaken the argument. An article does not need to be literally commissioned, however, to perform an ideological function. Its function is to narrow the boundaries of acceptable reform.
For decades, the liberal establishment was comfortable with institutional economics when it explained the poverty of developing countries through corruption, insecure property rights and authoritarian government. It becomes less comfortable when it applies the same analytical framework to Western capitalism and asks whether concentrated corporate power, weakened labor, regressive taxation, and technological oligopoly are themselves extractive institutions.
Acemoglu’s earlier work could be read as a vindication of the liberal order: inclusive Western institutions generated prosperity, whereas extraction explained stagnation elsewhere. His recent work turns the same lens inward. Formerly inclusive institutions can become extractive as wealth concentrates, labor weakens, shared prosperity recedes, and an increasingly consequential alliance forms among AI corporations, capital, and government. This resembles what I callreverse convergence: instead of drawing authoritarian systems towards Western norms, the West begins sacrificing its own restraints, competitive order and democratic commitments. The discontinuity is difficult to miss. The earlier Acemoglu was welcomed when extraction diagnosed failed states; the newer Acemoglu becomes objectionable when he asks whether the Western establishment is producing it from within.
That is the genuinely uncomfortable Acemoglu. He does not merely warn against Trump, Erdogan, Bolsonaro, or other populist-authoritarian leaders. He asks what failures of liberalism made their ascent possible. He does not excuse attacks on democracy, but he also does not let established elites present themselves as innocent guardians of a system they helped discredit.
His argument deprives the liberal establishment of its preferred moral simplicity: enlightened institutions on one side and irrational populism on the other. Between them lies the political economy of abandoned regions, insecure employment, declining mobility, concentrated wealth and citizens who experience democracy as periodic voting without meaningful influence over the forces shaping their lives.
Reform or Systemic Rupture
Acemoglu’s program may not be radical enough for the anti-capitalist left, yet it remains too interventionist for market liberals. That is precisely why it matters. It attempts to construct a reformist route between neoliberal exhaustion and authoritarian rupture.
The world does not lack warnings about populism. It lacks a political economy capable of removing the conditions from which populism draws its power. Democracy cannot survive indefinitely if its defenders offer citizens constitutional lectures while denying them economic security, social recognition and effective representation. Nor can democracy be protected merely by banning movements that attract disappointed voters. Suppressing political symptoms without addressing the economic and institutional disease risks transforming liberal democracy into rule by enlightened guardians—liberal in vocabulary but increasingly illiberal in practice.
This does not require accepting every demand articulated in the name of “the people.” Majorities can violate minority rights, attack judicial independence and empower authoritarian leaders. As Rodrik and Sharun Mukand emphasize, electoral democracy and liberal democracy are not identical. Political rights, civil rights and property rights rest on different social coalitions and may come into conflict. But defending minority rights and constitutional constraints cannot be permanently separated from material inclusion. Liberal democracy needs social and economic foundations—what Acemoglu calls shared prosperity and what Rawls approached through the fair value of political liberties.
The necessary reform must therefore go beyond ordinary regulation. It must reconsider the relationship between labor and capital, public authority and private power, national democracy and global markets. It must confront oligopoly, tax avoidance, the decline of collective bargaining, the privatization of knowledge, financial fragility and the political power accumulated by technology platforms. It must also recognize that efficiency is not the only criterion by which an economic order should be judged. Resilience, dignity, participation, social cohesion and democratic legitimacy are productive assets even when conventional models struggle to price them.
This does not make every Acemoglu proposition correct. His institutional categories can become too broad. His narratives may perform better retrospectively than predictively. His AI productivity estimate may require substantial revision. His reform agenda needs clearer instruments, stronger political coalitions, and feasible international implementation. These are reasons to debate Acemoglu seriously, not to dismiss or deny his contribution.
The Economist instead alternates between technical objections and rhetorical condescension. It asks why institutions matter if institutions emerge from earlier institutions. Yet all social explanation must begin with inherited structures, historical shocks, and political conflict. It describes pro-worker technology as obvious while economic incentives overwhelmingly favor labor substitution. It criticizes Acemoglu for underestimating technology’s benefits while neglecting his central question: who possesses the power to direct those benefits?
So, Whose Voice Is The Economist Speaking For?
Perhaps the answer is simpler than conspiracy. The Economist appears to want Acemoglu the institutional economist, but not Acemoglu the political economist of concentrated power. It was comfortable with the scholar who explained why poorer countries require better institutions; it is markedly less comfortable with the Nobel laureate who argues that the institutions of rich liberal democracies are themselves being captured and must be reconstructed. The archive therefore suggests that what changed is not simply the quality of Acemoglu’s scholarship, but the direction in which his institutional lens is now pointed.
It wants criticism of authoritarian populism without a complete investigation of the economic order that produced populist demand. It welcomes innovation but resists democratic claims over its direction. It accepts limited regulation while remaining suspicious of any project that would redistribute decision-making power from capital owners, digital platforms and credentialed elites towards workers and communities.
This does not mean that the magazine speaks under instruction from a hidden group of technology billionaires. Its voice is more structural than conspiratorial. It expresses the worldview of a liberal-capitalist establishment that recognizes the excesses of the existing order but remains reluctant to reconsider its distribution of power.
This distinction becomes decisive as the available policies and strategies approach their limits. Monetary policy is trapped between inflation and debt; fiscal policy between social demand and bond-market discipline; industrial policy between national security and retaliatory protectionism; democratic politics between electoral competition and declining governing capacity. We can already feel the breath of the next crisis. The central question is no longer whether the cards will be reshuffled, but who will be permitted to reshuffle them – and who will own the table after the reshuffle.
The defenders of the existing order may accept new leaders, a new regulatory vocabulary and even a redesigned institutional facade. What they resist is a settlement in which the groups that absorbed the old system’s losses gain real power over the new one. Their preferred reform redistributes the cards, but the old owners remain the winners: governments change, technologies change, and the language of policy changes, while command over capital, data, knowledge, and political influence remains substantially intact.
From this perspective, the attack on Acemoglu matters not simply because it targets a Nobel laureate. It attempts to weaken one of the intellectual routes leading public attention from the visible failure of governments to the deeper structures that constrain them. Acemoglu encourages us to ask not only why one government failed, but why successive governments confront the same wall; not only why populists win, but why liberal democracy no longer corrects the grievances on which they feed; and not only whether AI raises productivity, but who will control that productivity and appropriate its gains.
It favors reform, provided it does not become a transfer of power. Acemoglu’s real offense is not pessimism. It is his insistence that technological progress is a political choice, that liberal democracy cannot be separated from shared prosperity, and that markets cannot discipline concentrations of power they have themselves created.
The irony is that Acemoglu is trying to save, not destroy, the liberal order that The Economist historically defended. He warns that unless capitalism is disciplined, technology democratized, and prosperity more broadly shared, the next stage will not be a purer liberalism. It will be deeper oligarchy, more aggressive populism and an expanding authoritarian state.
The global system is running out of conventional policy space. Its monetary, fiscal, geopolitical and technological contradictions can no longer be resolved by indefinitely shifting costs onto workers, taxpayers and future generations. Either liberal democracy develops the capacity to reform the structures producing inequality, insecurity and concentrated power, or a future crisis will reform them through disorder.
One may disagree with Acemoglu’s models, historical interpretations, or remedies. But dismissing his central warnings as gloomy or obvious is not an answer. The essential question is no longer whether the existing order needs reform. It is whether reform can arrive before the next crisis—and whether reshuffling the cards will create a genuinely new settlement or merely reproduce the old winners under a new institutional name.
Why do some of the world’s wealthiest individuals openly support populist radical right and far-right movements whose central political message revolves around anti-immigrant and anti-minority mobilization? In this commentary, Dr. Bulent Kenes argues that this alliance is best understood not as an ideological convergence but as a pragmatic strategy for deflecting public attention from the structural roots of social injustice, economic inequality and wealth concentration. Drawing on John Rawls’s concept of the veil of ignorance, the article examines how immigrants—among the principal victims of contemporary economic and social inequalities—are transformed into convenient scapegoats. It further explores how the growing concentration of economic and digital power enables technology billionaires to amplify exclusionary narratives while marginalizing pluralistic voices, raising profound questions about democracy, algorithmic governance, and contemporary capitalism.
If we were to apply John Rawls’s famous veil of ignorance thought experiment, developed in A Theory of Justice, to today’s world, there is little doubt that immigrants would emerge as one of the most disadvantaged and the most vulnerable social groups. Immigrants, political refugees, in particular, as well as individuals forced to migrate for economic reasons, are compelled at some stage of their lives to leave behind their accumulated economic, social, and professional capital and begin life anew in a different country. Consequently, they typically enter their host societies from the lowest rungs of the social hierarchy. In terms of cultural, economic, and professional resources, their starting point is often below zero.
In this respect, immigrants constitute one of the most disadvantaged and vulnerable segments of society in terms of social justice and income distribution. Yet, while attempting to rebuild their lives, they are forced to contend not only with economic and social hardships but also with the prejudices generated by the rising populist radical right (PRR) and far-right parties and movements. Moreover, by being portrayed as the principal culprits behind economic inequality and social injustice, they are turned into scapegoats, a process that imposes severe socio-psychological costs on an already vulnerable population.
One point can be stated unequivocally: economically (and even culturally) driven anti-immigrant sentiment is not a phenomenon that emerges spontaneously. Social injustice and income inequality are undoubtedly real societal problems, and angry eyes are constantly searching for those responsible for them. Unfortunately, they do not always succeed in identifying the real causes. Meanwhile, for far-right actors who incite, inflame and ride the wave of resentment generated among these groups, targeting immigrants—one of the weakest, least organized, and least capable social groups in socio-political and economic terms—is both the easiest and the least politically costly strategy. Although the attempts of far-right political actors, whose humanitarian sensitivities have been considerably weakened, to exploit and simultaneously provoke this wave for political gain deserve the strongest ethical condemnation, it is nevertheless understandable why they choose this strategy within the context of political competition, which is driven less by values than by the pursuit of power. The fact that populist far right politicians such as Donald Trump, Viktor Orbán, Marine Le Pen, Nigel Farage, Geert Wilders, Robert Fico, Jarosław Kaczyński, Jimmie Åkesson, and many others have placed anti-immigrant politics at the center of political mobilization can be understood within this framework.
What is particularly striking, however, is why dollar billionaires—and even the owners of trillion-dollar companies—whose activities are largely confined to technology and the global economy, support far-right actors, PRR parties and movements, and anti-immigrant rhetoric.
In my view, the principal explanation lies in pragmatic interests. The anti-immigration discourse of the populist radical right and the far right systematically recasts those who are most severely affected by income inequality and social injustice from victims into perpetrators of these very problems. In reality, however, immigrants—alongside other disadvantaged groups—are among the greatest losers of the contemporary global economic order and the structural inequalities it generates. This is precisely where the core of the issue lies. By systematically constructing immigrants as scapegoats, far-right actors divert public attention away from the structural sources of economic inequality and social injustice. In doing so, they help obscure the role of the super-rich, who are not only the principal beneficiaries of the existing distribution of wealth but also key beneficiaries of the economic structures that reproduce and deepen these inequalities.
It is precisely at this point that the logic behind the support given by figures such as Elon Musk, Mark Zuckerberg, and Jeff Bezos—the greatest beneficiaries of the existing global economic order—to populist radical right parties and far-right actors becomes apparent. Historically, just as the East India Company and the West India Company represented the corporate actors that benefited most from the global colonial order of their time, today’s technology giants occupy a comparable position as the greatest beneficiaries of contemporary global hi-tech capitalism. The strengthening of political discourse centered on anti-immigrant sentiment diverts public attention away from these structural causes of economic inequality and wealth concentration.
Regrettably, I must note that approaches which, in recent years, have argued that anti-immigrant sentiment is fundamentally the product not of economic grievances but of a cultural backlash, even if unintentionally, contribute to strengthening this political strategy. The influence of cultural factors and identity politics cannot, of course, be denied. However, explaining anti-immigrant sentiment primarily through cultural dynamics diminishes the visibility of structural causes such as economic inequality and social injustice, while simultaneously providing the far right with an indirect—albeit problematic—source of legitimacy. The issue, therefore, is not merely one of cultural reaction; it should also be understood as a political mechanism of distraction that conceals underlying economic power relations and discourages scrutiny of the existing distribution of wealth.
If the support that the super-rich extend to the far right were merely an expression of their individual political preferences, it might not warrant such sustained attention. The issue, however, extends far beyond that. These billionaires, who have effectively acquired monopolistic positions in the technology sector, not only deploy their immense economic resources in support of far-right political movements but also possess the capacity to shape the boundaries of public discourse through the digital platforms they control, including X, Facebook, YouTube, and others. Through complex algorithmic mechanisms, these platforms are increasingly transformed into the principal channels for the circulation of far-right narratives, while alternative viewpoints, critical voices, and pluralistic perspectives experience a substantial loss of visibility.
In this process, observations suggesting that the digital visibility of actors defending liberal democratic values, pluralism, the rule of law, and humanitarian principles is being systematically weakened, while polarizing, provocative, and extremist content is algorithmically rewarded, are increasingly supported by empirical research. As a consequence, democratic actors using these platforms face not only declining public influence but also invisible, though perceptible, algorithmic barriers that make it increasingly difficult even to reach their own natural audiences.
This picture reveals the combined impact of the economic and digital power of technology barons who stand among both the principal creators and the greatest beneficiaries of the global income divide. Despite being among the primary causes and beneficiaries of wealth concentration, economic inequality, and social injustice, Elon Musk and similar actors openly support extremist, far-right political movements that systematically portray immigrants and other vulnerable socio-cultural minorities as those responsible for these problems and as convenient scapegoats. Elon Musk’s most recent extensive interview with The Economist, in which he reiterated positions supportive of the far right, together with his backing of Marine Le Pen, Alternative for Germany (AfD) and various other far-right parties and actors, is open to interpretation within this framework. The political positions, public rhetoric, and algorithmic maneuvers of Musk and other technology-baron billionaires function as a deliberate mechanism of distraction, obscuring the true sources of wealth concentration and structural economic inequality.
Perhaps the greatest contradiction that deserves attention, and the most fundamental question that requires an answer, is the following: Why do broad segments of society that are themselves victims of structural economic inequality and social injustice follow far-right political actors supported by the greatest beneficiaries of wealth concentration, rather than questioning the structural causes of these inequalities? More importantly, why are they tend to view immigrants and socio-cultural minorities—groups that share similar structural vulnerabilities—as the principal causes of these problems? This paradox points not only to the discursive success of the populist radical right and far right but also to a fundamental research problem requiring us to understand how public perceptions are reshaped through the influence of economic and administrative power over digital communication infrastructures.
Are you interested in global trade politics and the future of Europe in a shifting world order? Do you want to understand how populism, great-power rivalry, and geopolitical tensions are reshaping EU trade between the Atlantic and the Indo-Pacific? The ECPS Academy Summer School 2026 offers a unique five-day program where leading scholars and policymakers explore the EU’s role in an era of economic uncertainty and strategic competition. Participants will engage in interactive lectures, small-group discussions, and a dynamic simulation game on EU trade strategy, gaining hands-on experience in policy analysis and recommendation drafting. Join an international, multidisciplinary environment, exchange ideas with peers worldwide, earn ECTS credits, and become part of a global network studying populism, political economy, and international relations.
Overview
In today’s rapidly shifting global order, the European Union can no longer afford to think in one direction. For decades, the transatlantic relationship has been the backbone of global trade, built on shared institutions, economic interdependence, and liberal values. Yet this foundation is no longer stable. As highlighted in the ECPS report Populism and the Future of Transatlantic Relations, domestic political polarization and the rise of populism on both sides of the Atlantic are reshaping trade policy, weakening trust, and challenging the very principles of open markets and multilateralism. The EU now faces a critical question: how to remain a global trade power when its closest partner is becoming less predictable.
At the same time, the center of gravity of global trade is shifting toward the Indo-Pacific. This region has become the epicenter of economic dynamism and geopolitical competition, where the future of global trade rules is increasingly being contested. The growing rivalry between the United States and China is not only a security issue but also a trade and technological struggle shaping supply chains, investment flows, and regulatory standards. As the US adopts more unilateral and strategic approaches to trade, moving away from traditional multilateralism, the EU must navigate a complex environment where cooperation, competition, and coercion coexist. Ignoring the transpacific dimension would mean missing where the future of global trade is being written.
For the European Union, the challenge and opportunity lie in managing both arenas simultaneously. The transatlantic relationship remains indispensable for economic scale, regulatory cooperation, and political alignment, while the transpacific region is crucial for diversification, resilience, and strategic autonomy. As scholars increasingly argue, the EU is no longer just a “junior partner” but an actor that must define its own role within a triangular system shaped by US–China competition. To lead in international trade today means mastering this dual engagement: stabilizing relations with the United States while actively shaping the Indo-Pacific order. This requires not only policy innovation but also a new generation of thinkers who understand trade through a geopolitical lens.
Against this backdrop, ECPS Academy Summer School-2026 brings together leading scholars and policymakers to examine how populism and great-power competition are reshaping EU trade policy across both transatlantic and transpacific arenas.
It offers a unique opportunity to explore:
The future of EU–US trade relations in an era of populism
The strategic importance of the Indo-Pacific and the US–China trade rivalry for the EU
How global trade is being reshaped by geopolitics, security, and ideology
The populist discourse around trade, policy, and power, and its implications for the EU’s trade relations
It also allows participating in an enjoyable and dynamic simulation game on the EU’s trade relations, trying to bring policy suggestions.
You will learn and actively engage in discussions, develop your own policy ideas, take part in simulation games, have the opportunity to publish on ECPS venues, and become part of an international network working at the intersection of political economy, international relations, and populism studies.
Tentative Program
Day 1 – Monday, July 6, 2026
Theme: The EU in the Global Trade Order: From Liberalism to Geoeconomics
This opening day sets the conceptual stage. It introduces how EU trade policy evolved from embedded liberalism to strategic autonomy, and how trade is now intertwined with security and geopolitics. It also establishes the role of populism and domestic politics in reshaping trade preferences and legitimacy crises in Europe and beyond.
Lecture One: (15:00-16:30) –Evolution of EU Trade Policy and Global Trade Order
Lecturer:Arlo Poletti (Professor of International Relations at the Department of Sociology and Social Research of the University of Trento).
Moderator:Sonali Chowdhry (Ph.D., Research Associate, DIW Berlin, Fellow, Kiel Institute for the World Economy).
Lecture Two: (17:30-19:00) –Populism, Legitimacy, and the Politicization of Trade
Lecturer:Kent Jones (Professor Emeritus of Economics, Babson College).
Moderator: Dr. Neo Sithole (Non-resident Research Fellow at ECPS Foreign Policy Research Group).
Day 2 – Tuesday, July 7, 2026
Theme: EU–US Trade Relations under Pressure: Cooperation, Conflict, and Populism
Focuses on the transatlantic pillar, still central but increasingly unstable. It examines tariff disputes, regulatory divergence, and how populist and protectionist politics in the US and Europe challenge long-standing cooperation and WTO-based norms.
Lecture Three: (15:00-16:30) – Political Economy of EU–US Trade Relations
Lecturer: Erik Jones (Professor of European Studies and International Political Economy, Director of the Robert Schuman Centre for Advanced Studies at the European University Institute and Non-resident Scholar at Carnegie Europe).
Moderator:Elaine Fahey (Professor of EU Law, City Law School, City St. Georges, University of London).
Lecturer: Alasdair Young (Professor and Neal Family Chair in the Sam Nunn School of International Affairs, Georgia Tech).
Moderator: Jessica Lawrence (Senior Lecturer at the University of Essex School of Law).
Day 3 – Wednesday, July 8, 2026
Theme: The EU Between the US and China: Trade, Power, and Strategic Autonomy
This session introduces the triangular dynamic (EU–US–China) and how the EU navigates between partnership and rivalry. It highlights de-risking, economic security, supply chains, and competing models of globalization.
Lecture Five: (14:00-15:30) – Strategic Autonomy, De-risking, and EU Economic Security Tools
Lecturer:Reuben Wong (Associate Professor, Department of Political Science, National University of Singapore).
Moderator: TBC.
Lecture Six: (16:00-17:30) – The EU’s Policy Towards Asia Amidst Changing US–China Security and Trade Dynamics
Lecturer:Giulio Pugliese (Director of the EU-Asia Project, European University Institute + Associate Fellow Istituto Affari Internazionali, and King’s College London).
Moderator:Anita Tusor (Researcher in International Relations, Charles University, Prague).
Day 4 – Thursday, July 9, 2026
Theme: The Indo-Pacific Turn: EU Trade Strategy in a Shifting Global Centre
This session shifts focus to the transpacific dimension, emphasizing that the future of trade is increasingly shaped in the Indo-Pacific. It explores how US strategies toward China and the region reshape global trade, and how the EU responds through diversification and partnerships.
Lecture Seven: (15:00-16:30) –US Indo-Pacific Strategy and Its Trade Implications
Lecturer:Kristi Govella (Associate Professor of Japanese Politics and International Relations in the Nissan Institute of Japanese Studies and the Oxford School of Global and Area Studies at the University of Oxford).
Moderator:Andrea Carteny (Professor of History of International Relations, Sapienza University of Rome).
Lecture Eight: (17:30-19:00) – EU-Japan Relations and Populism
Lecturer:Axel Berkofsky (Associate Professor at the University of Pavia and Co-Head of the Asia Centre at ISPI).
Moderator:Sebastien Goulard (Ph.D., Manager of Cooperans, Consultant in EU-Asia connectivity projects).
Day 5 – Friday, July 10, 2026
Theme: The Future of EU Trade Power: Between Fragmentation and Leadership
This session will ask whether the EU can become a global trade power amid fragmentation, populism, and great-power rivalry. It also allows for normative and policy-oriented discussions.
Lecture Nine: (15:00-16:30) Can the EU lead? Policy Tools, Regulatory Power, and Global Influence
Lecturer:Markus Kotzur (Professor of European and International Law, Vice Dean for International Relations and Chair for Public Law, European and International Public Law, Hamburg University).
Moderator:Camille Nessel (Ph.D., Lecturer in Political Science Université libre de Bruxelles (ULB)-CEVIPOL).
Methodology
The program will take place on Zoom, consisting of two sessions each day and will last five days. The lectures are complemented by small group discussions and Q&A sessions moderated by experts in the field. Participants will have the opportunity to engage with leading scholars in the field as well as with activists and policymakers working at the forefront of these issues.
The final program with the list of speakers will be announced soon.
Furthermore, this summer school aims to equip attendees with the skills necessary to craft policy suggestions. To this end, a simulation game will be organized on a pressing theme within the broader topic to identify solutions to issues related to the future of the EU trade relations.
Who should apply?
This course is open to master’s and PhD level students and graduates, early career researchers and post-docs from any discipline. The deadline for application submissions has been extended to June 26, 2026. As we can only accept a limited number of applicants, it is advisable to submit applications as early as possible rather than waiting for the deadline.
The applicants should send their CVs to the email address ecps@populismstudies.org with the subject line: ECPS Summer School Application.
We value the high level of diversity in our courses, welcoming applications from people of all backgrounds.
Evaluation Criteria and Certificate of Attendance
Meeting the assessment criteria is required from all participants aiming to complete the program and receive a certificate of attendance. The evaluation criteria include full attendance and active participation in lectures.
Certificates of attendance will be awarded to participants who attend at least 80% of the sessions. Certificates are sent to students only by email.
Credit
This course is worth 5 ECTS in the European system. If you intend to transfer credit to your home institution, please check the requirements with them before you apply. We will be happy to assist you; however, please be aware that the decision to transfer credit rests with your home institution.
Brief Biographies and Abstracts
Day One: Monday, July 6, 2026
Theme: The EU in the Global Trade Order: From Liberalism to Geoeconomics
Evolution of EU Trade Policy and Global Trade Order
Arlo Poletti is a Professor of International Relations at the Department of Sociology and Social Research of the University of Trento. He obtained a PhD from the University of Bologna, was a post‐doctoral researcher at the University of Antwerp (2009-2013), and held positions as an Assistant professor at the LUISS Guido Carli (2013-2016) and the University of Bologna (2016). His research interests are in the area of International Political Economy, with particular emphasis on the politics of trade and investments, transnational advocacy at the global and EU-levels, and international regulatory cooperation. Recently, he expanded his research agenda to include analyses of how globalization-induced economic distress affects individual- level preferences and political behavior. He is the author of five monographs and his research has been published in journals such as International Organization, Regulation & Governance, JCMS: Journal of Common Market Studies, the Journal of European Public Policy, Review of International Studies, the European Political Science Review and Review of International Organizations.
Reading List
Bauerle Danzman, S., and Meunier, S. (2024), ‘The EU’s Geoeconomic Turn: From Policy Laggard to Institutional Innovator’, Journal of Common Market Studies, 62: 1097–1115
De Bièvre D. and Poletti A. (2014), ‘The EU in trade policy: From regime shaper to status quo power’, in Falkner, G. and Müller, P. (eds.), EU Policies in a Global Perspective: Shaping or taking international regimes? London and New York: Routledge
Dür A., Eckhardt J. and Poletti A. (2020), ‘Global Value Chains, the Anti-Globalization Backlash and EU Trade Policy: A Research Agenda’, Journal of European Public Policy, 27(6): 944-956.
Poletti A. (2025), ‘Trade‘, in Lucarelli S. and Sperling J. (eds.), Handbook of European Union Governance, Cheltenham: Edward Elgar.
Dr. Sonali Chowdhryis a trade economist and Research Associate (tenure-track) based at the Firms and Markets Department, DIW Berlin. Her research investigates global supply chains, firm heterogeneity and the distributional implications of trade policy shocks. To study these issues, she analyses detailed transactions-level customs databases using modern econometric methods.
She also teaches international trade at the Hertie School in Berlin as a Guest Lecturer. In 2025, she was a Visiting Research Fellow at the Harvard Growth Lab and has been affiliated with the Trade Policy Research Centre at the Kiel Institute for the World Economy since 2019. Over 2022-2023, she was awarded the Max Weber Postdoctoral Fellowship by the European University Institute to analyse the effect of sanctions on global trade networks.
She completed her PhD in Economics (with distinction) from LMU Munich in 2022, funded by the EU’s Marie Skłodowska-Curie Actions programme. Prior to this, she worked as a Junior Economist with the Ifo Institute’s Center for International Economics and pursued the MPhil in Economics from University of Oxford as a Rhodes Scholar from India.
Populism, Legitimacy, and the Politicization of Trade
Kent Jones, Dr. es sci. pol. (international economics), Graduate Institute of International Studies/University of Geneva, is Professor Emeritus of Economics at Babson College, where he taught from 1982 until his retirement in 2023. He continues his academic interests in trade policy and trade institutions, having published several books and articles on these topics, including Populism and Trade (2021). His teaching also included visiting appointments at Brandeis University, the Fletcher School at Tufts University, and the University of Innsbruck, Austria. In addition, he served as a visiting senior economist at the U.S. Department of State.
Abstract: The GATT-WTO trading system emerged during the post-World War 2 period as a multilateral institution led by the United States that supported mutually recognized rules of trade policy, negotiations for trade liberalization, day-to-day contact among trade diplomats and dispute settlement among participants through third-party adjudication. These functions generated positive externalities in trade relations based on coordination, cooperation, reciprocity, and a mutual recognition of the goals and benefits of trade liberalization. The system fostered eight successful rounds of trade negotiations from 1947 to 1994. Yet the increasing diversity of its participants, along with globalization-driven adjustment crises in many countries, rapidly advancing technology and geopolitical conflict, began to erode the legitimacy of GATT-WTO rules. Compounding these challenges, the trade policy of populist US President Donald Trump precipitated a major crisis as he abrogated numerous GATT-WTO system rules and norms, weakening its legitimacy. Unilateral nationalist protectionism replaced multilateral cooperation as the US abandoned the core principle of non-discrimination in trade relations and abandoned previously negotiated tariff levels with its trade partners. The shock was all the more devastating as the US had been the erstwhile leader and champion of the GATT-WTO system. As President Trump approaches the mid-term elections of his second and final term in office, supporters of a rules-driven trading system are contemplating the possibilities and challenges of restoring the WTO’s legitimacy through reforms and initiatives, new leadership and increased flexibility in liberalizing trade in a diverse and divided world economy.
Reading List
Kent Jones (2023), Populism, Globalization, and the Prospects for Restoring the WTO, Politics and Governance, vol. 11 (1): 181-192).
Judith Goldstein and Alan Sykes (2025). The Perils of Institutional Rigidity, or How the WTO Helped to Sow the Seeds of Trump. World Trade Review, vol. 24: 481-489.
Patrick Low and George Riddell (2025). Trump’s Trade Policy and the World Trade Organization. World Trade Review, vol. 24: 489-497.
Bernard Hoekman (2025). Plurilateral cooperation in response to aggressive unilateralism? Asia and the Global Economy, vol. 5 (2).
Dr. Neo Sithole is a non-resident research fellow at ECPS Foreign Policy Research Group. His Ph.D. at the University of Szeged, Hungary, examines the history and trends of populism and political communication in sub-Saharan Africa. Sithole has contributed to publications on democracy, the influence of populism on Western liberal democracies, democratic legitimation and populism possibilities for alternative kinds of democratic imaginings. His academic interests span African and European populism, Afro-European diplomacy, foreign policy, regional and global security, and promoting international solidarity. Sithole also serves as an ambassador for the Doktoranduszok Országos Szövetsége (DOSZ), the Hungarian Association of Doctoral Students, working to foster an inclusive and integrated scientific community.
Day 2 – Tuesday, July 7, 2026
Theme: EU–US Trade Relations under Pressure: Cooperation, Conflict, and Populism
Political Economy of EU–US Trade Relations
Erik Jones is Director of the Robert Schuman Centre for Advanced Studies at the European University Instituteand Non-resident Scholar at Carnegie Europe. Professor Jones is author of The Politics of Economic and Monetary Union (2002), Economic Adjustment and Political Transformation in Small States (2008), Weary Policeman: American Power in an Age of Austerity (2012 — with Dana H. Allin), The Year the European Crisis Ended (2014), and From Club to Commons: Enlargement, Reform, and Sustainability in European Integration (2025 — with Veronica Anghel). He is editor or co-editor of more than thirty books and special issues of journals on topics related to European politics and political economy, including reference works like The Oxford Handbook of the European Union (2012) and The Oxford Handbook of Italian Politics (2015). Professor Jones is also co-editor of Government and Opposition.
Elaine Fahey is Professor of EU Law at the City Law School, City St. Georges, University of London and Deputy Head of Department (academic programmes). She is co-convener of the Institute for the Study of European Law (ISEL), City Law School. She has been a Senior Land Steiermark Fellow of Law and Innovation at the University of Graz, Austria, a visiting Professor at Washington College of Law, American University, Washington DC, Emile Noël Fellow at New York University (NYU) Law School and a visiting professor at Keio University Law School, Tokyo, Japan as well as other visiting positions. She has worked as a Senior Postdoctoral Researcher at Amsterdam Centre for European Law & Governance (ACELG), University of Amsterdam, as a Max Weber Fellow, European University Institute (EUI), Florence and Assistant Lecturer and Lecturer in Law in Ireland (Dublin Institute of Technology; Trinity College Dublin). She has practised as a Barrister and was Chairperson of the Irish Society for European Law. She has been a stagiaire at the CJEU, Luxembourg, a Judicial Research Assistant, Four Courts, Dublin and a Judicial Extern, Los Angeles Federal District Court (9th Circuit). Her research interests span the relationship between the EU as a global digital actor, EU external relations, EU law and global governance, trade, transatlantic relations, cybersecurity and the EU’s AFSJ.
Alasdair Young is Professor and Neal Family Chair in the Sam Nunn School of International Affairs at the Georgia Institute of Technology. He is Director of the School’s Center for Research on International Strategy and Policy and is Interim Associate Dean for Faculty Development for Georgia Tech’s Ivan Allen College of Liberal Arts. He was Co-editor of JCMS: Journal of Common Market Studies (2017– 2022) and was Chair of the European Union Studies Association (USA) (2015– 2017). Before joining Georgia Tech in 2011 he taught at the University of Glasgow for 10 years. Prior to that he held research posts at the European University Institute and the University of Sussex. He has written extensively on EU trade policy and transatlantic economic relations and performed consultancy work for the United States and United Kingdom governments and for the European Commission.
Abstract: Since the end of the Second World War the United States and Europe have pursued trade liberalization, initially through multilateral negotiations and subsequently through less successful bilateral cooperation. As a result, the transatlantic economy is very valuable and deeply interpenetrated. The transatlantic economic relationship has periodically been characterized by tensions and disputes, but these were of limited duration or narrowly contained. During President Trump’s second term the US has reversed the process of closer economic integration and coerced the European Union into a lopsided trade agreement. Trump ran in part on a populist anti-trade message and his policy ostensibly pursues that agenda, but the populist message on trade has been complicated by the perceived adverse impact of higher tariffs on consumers. This lecture will situate recent US transatlantic trade policy in historical perspective, making clear what a departure from past practice it has been in both substance and form. It will also explain why the EU accepted a lopsided agreement and assess whether the policy has realized US objectives. It will also consider where transatlantic economic relations might go from here.
Reading List
Baldwin, R. (2026), World War Trade: Conflict, Containment, and the Emergent World Trading Order, Rapid Response Economics 7, CEPR Press, pp. 7-14
Mutz, D.C. (2021), “How Americans Think About Trade: Winners, Losers, and the Psychology of Globalization,” Foreign Affairs, 30 July.
Young, A.R. (2025), “From Trade Skirmishes to Trade War? Transatlantic Trade Relations During Trump 2” in M. Riddervold, G. Rosen, & J.R. Greenberg, (2026). Populism and the Future of Transatlantic Relations: Challenges and Policy Options. European Center for Populism Studies (ECPS). January 20, 2026, 128-141.
Moderator: Prof Jessica Lawrence, Senior Lecturer at the University of Essex School of Law
Jessica Lawrence is a Senior Lecturer at the University of Essex School of Law. Dr Lawrence’s research focuses on issues relating to international economic integration, including at the WTO, in regional and bilateral trade and investment agreements, and within the EU internal market. She has a particular interest in the interaction between economic and non-economic public policy goals, and in the ways in which trade and investment agreements take into account their impacts on human rights, labour, sustainable development, environmental protection, and gender. Her work often takes a critical perspective, applying tools drawn from constructivist international relations theory, post-Foucauldian governmentality studies, and other strands of post-positivist thought to examine the impact of discourses and framing devices on politics and law. Prior to joining the University of Essex, Dr Lawrence was Associate Professor at Central European University in Budapest, Hungary. She holds a PhD in Transnational Legal Studies from the Vrije Universiteit Amsterdam, the Netherlands, and a JD in Law from the University of Georgia in the United States. In addition to her academic work, Dr Lawrence has held various positions at NGOs, think tanks, and universities in the US, EU, India, New Zealand, and Costa Rica, and continues to provide research and training for governmental and non-governmental organizations on issues related to trade and investment agreements and their impact on social policy goals.
Day 3 – Wednesday, July 8, 2026
Theme: The EU Between the US and China: Trade, Power, and Strategic Autonomy
Strategic Autonomy, De-risking, and EU Economic Security Tools
Reuben Wong is Deputy Head of the Political Science Department at the National University of Singapore. Reuben held the first Jean Monnet Chair in Singapore (2013–2016) and was NUS’ Associate Vice-President, Global Relations (2021– 2023). His publications have focused on EU foreign policy. They include The Europeanization of French Foreign Policy: France and the EU in East Asia (Palgrave Macmillan, 2006), National and European Foreign Policies (co-edited with Christopher Hill, Routledge, 2011), and journal articles in the Cambridge Review of International Affairs, Politique Européenne, the Asia Europe Journal, The Hague Journal of Diplomacy, and the EU External Affairs Review. He has held visiting positions at Cambridge University, the LSE European Institute, the Stimson Center (Washington, D.C.), the East Asian Institute (Singapore), and Humboldt University. He consults and teaches summer school in Paris and Beijing. Reuben raises four children to help arrest Singapore’s declining total fertility rate.
Abstract: I will trace the EU’s search for strategic autonomy and how it has been challenged by both the U.S. and China. I will also suggest how Europe could be more strategic in its dealings with the U.S. and China, and work on better understanding its own identity/interests and those of its interlocutors.
The EU’s Policy Towards Asia Amidst Changing US–China Security and Trade Dynamics
Dr. Giulio Pugliese is Lecturer in Strategic Communications at King’s College London and the Director of the EU-Asia Project at the European University Institute. He specialises in the international politics of the Asia-Pacific with a focus on Japan, China and the United States. He has presented and published on academic, policy-oriented and commercial themes, including in International Affairs, The Australian Journal of International Affairs, The Asia-Pacific Journal, East Asian Policy, Pacific Affairs, The Pacific Review, Defence Strategic Communications. He is a regular contributor to Asia Maior, Italy’s leading journal on contemporary Asian affairs, and author of Sino-Japanese Power Politics: Might, Money and Minds (Palgrave MacMillan, 2017, also available in Korean).
Dr Pugliese earned a Laurea (B.A.) in Political Science and East Asian Studies at the University of Naples, “L’Orientale” (cum laude), an M.A. in International Economics and International Relations (concentrating on East Asian Studies) at the Paul H. Nitze School of Advanced International Studies (SAIS), Johns Hopkins University, graduating with Honors and passing the final exam with Distinction. He completed his Ph.D. at the University of Cambridge. He was a Wissenschaftlicher Mitarbeiter at the Department of Chinese Studies in Heidelberg University, a Lecturer in War Studies at King’s College London, a Lecturer in Japanese Politics at the University of Oxford, and a recipient of a British Academy post-doctoral fellowship. He has held visiting scholar positions at GRIPS, Johns Hopkins University SAIS, and George Washington University. In 2023, he was awarded the Nakasone Incentive Award for his research on Japanese diplomacy.
Abstract: How best to explain the EU and member states’ quiet security and economic recalibration of relations vis-à-vis China and Asia? Reactiveness to Chinese assertiveness, the need to achieve economic security, as well as the emergence of interlinkages between the East Asian and European security theatres following Russia’s full-scale invasion of Ukraine is accompanied by economic interests in what is the region that is fast becoming the locomotive of the world economy, including in its procurement market. US demand signals and the emulation of practice from local players, such as Japan, have also driven the process. As the Transatlantic alliance faces a rupture under the second Trump administration, this lecture also probes the tenability of alternative routes to salvage Transatlantic and Indo-Pacific cooperation and engagement towards the so-called “Indo-Pacific”, suggesting potential solutions and ways to manage policy expectations.
Reading List
Angela Pennisi di Floristella and Giulio Pugliese. “The Historical Evolution of Relations between the European Union and Asia”, in Thomas Christiansen, Evi Fitriani, Emil Kirchner, and Youngah Guahk [eds.], The Palgrave Handbook of EU-Asia Relations (2nd Edition), Cham, Switzerland: Palgrave Macmillan, 2026, Chapter 1.
Giulio Pugliese and Aurelio Insisa, “How to use the maximum of potential for the EU-Taiwan cooperation – what can the EU learn from the US and other actors?”, in-depth policy study requested by the European Parliament’s Committee on Foreign Affairs (AFET), 26 November 2025: https://www.europarl.europa.eu/thinktank/en/document/EXPO_IDA(2025)754482
Giulio Pugliese, “The European Union and an ‘Indo-Pacific’ Alignment”, Asia-Pacific Review, Vol. 31 (4), 2024, pp. 17-44.
Giulio Pugliese. “Japan’s China Grand Strategy: A Blueprint for Transatlantic Players?” in Rogier E. Creemers, Silvia Menegazzi, Neysun A. Mahboubi [eds.] Transatlantic Perspectives on China, London and New York: Routledge, 2026, Chapter 6.
Giulio Pugliese short interview – March 2026, Japan and Europe in the Face of US-China Geopolitical Rivalry https://cgpbalancingact.substack.com/p/japan-and-europe-in-the-face-of-us
Anita Tusor is a PhD Student in International Relations at Charles University, Prague, specializing in security and strategic studies. She holds a Double Master’s Degree in Asian and European Affairs from King’s College London and Renmin University of China, as well as an MA in Applied Linguistics and a BA in Hungarian and Chinese Studies. Her professional experience includes research and policy work with NATO Allied Command Transformation, the Institute of International Relations in Prague, the European Center for Populism Studies, and the European Values Center for Security Policy. Her research interests focus on Chinese cognitive warfare, foreign malign influence operations, populist constitutionalism, and Asia-Pacific security.
Day 4 – Thursday, July 9, 2026
Theme: The Indo-Pacific Turn: EU Trade Strategy in a Shifting Global Centre
US Indo-Pacific Strategy and Its Trade Implications
Kristi Govella is Associate Professor of Japanese Politics and International Relations at the University of Oxford and Senior Adviser and Japan Chair at the Center for Strategic and International Studies. Dr. Govella specializes in the intersection of economics, security, and governance, with a focus on the Indo-Pacific region and Japan. Her research has examined topics such as economic statecraft, government-business relations, regional institutional architecture, military alliances, non-traditional security, and the governance of the global commons. Prior to joining the University of Oxford, Dr. Govella held positions at the University of Hawai‘i at Mānoa, the German Marshall Fund of the United States, Harvard University, and the Daniel K. Inouye Asia-Pacific Center for Security Studies. She holds a Ph.D. in Political Science from the University of California, Berkeley.
Abstract:Over the past two decades, the United States has intensified its focus on Asia due to the region’s strategic importance for both economics and security. In 2011, the “pivot to Asia” was announced, and during the course of the Obama, Trump 1.0, and Biden administrations, the U.S. gradually redefined the region as the “Indo-Pacific” and attempted to enhance its engagement. However, the role of trade in U.S. Indo-Pacific strategy has become increasingly complex, as “America first” concerns about trade deficits, reshoring, and industrial revitalization have gradually weakened the economic pillar of U.S. regional policy. This lecture will examine the evolution of U.S. Indo-Pacific strategy with particular attention to the changing role of economic engagement and implications for regional and global trade.
Reading List
U.S. Department of State, “A Free and Open Indo-Pacific: Advancing a Shared Vision” (November 2019). Available at https://www.state.gov/wp-content/uploads/2019/11/Free-and-Open-Indo-Pacific-4Nov2019.pdf
The White House, “Indo-Pacific Strategy of the United States” (February 2022). Available at https://bidenwhitehouse.archives.gov/wp-content/uploads/2022/02/U.S.-Indo-Pacific-Strategy.pdf
The White House, “National Security Strategy of the United States of America” (November 2025). Available at https://www.whitehouse.gov/wp-content/uploads/2025/12/2025-National-Security-Strategy.pdf
Andrea Carteny is a Professor at Sapienza University of Rome, Italy, where he teaches International Relations History, Nationalisms and Minorities at the SARAS (History Anthropology Religions Arts Spectacle) Department. He is a Fullbright Alumni and Director of the Hungarian Studies Review (RSU) and he focused his research on national minorities, nationalities and nationalisms in Eastern Europe and the Mediterranean area during the 19th- 20th Centuries. He is a member of the Italian Society of International History (SISI) and a participant in the main conventions and conferences on nation studies, national minorities and nationalisms history. He is author of many articles and books in this field, among them the editions Il Mar Nero. Identità nazionali e dinamiche di sicurezza (with G. Natalizia, 2023), Il Pan-nazionalismo in Eurasia e il mito del Turan (with P. Pizzolo, 2023), A New Continent Called Europe (2005), and the monographs La questione transilvana nel periodo interbellico (2020) and Dal micro-nazionalismo all’Europa (2011).
EU-Japan Relations and Populism
Axel Berkofsky is Associate Professor at the University of Pavia, Italy and Senior Fellow/Senior Advisory at the Asia Centre at the Milan-based Istituto per gli Studi di Politica Internazionale (ISPI). Axel Berkofsky is also Chairman of the Selection Committee and Vice-Chairman Executive Committee of the Canon Foundation Europe, Executive Committee Board Member at the Stockholm-based European Japan Advanced Research Network (EJARN) and Research Affiliate at the European Institute of Japanese Studies at the Stockholm School of Economics. Previously, Dr. Berkofsky was Senior Policy Analyst, Associate Policy Analyst at the Brussels-based European Policy Centre (EPC) and Research Fellow at the Brussels-based European Institute for Asian Studies (EIAS). At the EPC in Brussels, Axel Berkofsky has – in his capacity as the Director of the EPC’s former EU-Asia programme – worked and interacted on a de facto daily basis with EU officials, policymakers and diplomats. Furthermore, Dr. Berkofsky has in the recent years been involved – as scholar, researcher and moderator – in numerous panels, workshops and seminars on EU-Japan relations, EU-China relations and EU-Asia relations. In his capacity as Board Member of the Stockholm-based Europen Japan Advanced Research Network (EJARN), Dr. Berkofsky has since 2008 co-organized numerous conferences, seminars and workshops on EU-Japan relations at numerous think tanks and universities in Europe and Japan. Dr. Berkofsky is a fluent Japanese speaker and has altogether lived three years in Japan. Furthermore, Dr. Berkofsky has taught and lectured at numerous universities and think tanks in Japan, Mainland China, Taiwan, Vietnam, South Korea, The Philippines, Singapore etc. In addition, Axel Berkofsky has for several years worked as freelance journalist at the Hong Kong-based Asia Times. Axel Berkofsky has published and edited numerous books and has authored and published more than 250 journal articles, newspaper articles, essays, policy papers and policy briefings. Prof. Berkofsky is a regular consultant, speaker and presenter at conferences, seminars and workshops organized and sponsored by the European Union (EU).
Dr. Sebastien Goulard is the manager of Cooperans, a public affairs and project management consultancy specialized in EU-Asia connectivity projects. Sebastien Goulard is also the editor of the Global Connectivities platform which aims to analyse the development of corridors around the world. During his doctoral studies at EHESS (School for Advanced Studies in the Social Sciences), Paris Sebastien Goulard participated in several European research programs dealing with sustainable urbanization in China. Sebastien Goulard holds a BA (hons) degree in international politics (ESE, Nottingham Trent University), a MA degree in international relations (IRIS, France) and a MA degree in social sciences (EHESS).
Day 5 – Friday, July 10, 2026
Theme: The Future of EU Trade Power: Between Fragmentation and Leadership
Can the EU lead? Policy Tools, Regulatory Power, and Global Influence
Prof. Dr. Markus Kotzur, LL.M. (Duke Univ.) studied law in Freiburg and Bayreuth. In 1993, he passed the First State Examination and subsequently obtained the title “Legum Magister” (LL.M.) at Duke University (North Carolina). In 2002, after completing his legal traineeship, he received his doctorate from the University of Bayreuth. This was followed in 2002 by his habilitation with a thesis on “Cross-Border Cooperation in Europe”. In 2005, he was appointed Professor of European and International Law and Public Law at the University of Leipzig. Since 2011, he has been head of the Master’s programme “European and European Legal Studies” and since 2018 president at the Europa-Kolleg Hamburg. Since 2012, he has held the professorship for Public Law, European and International Law at the University of Hamburg and is Deputy Director of the Institute for International Affairs. From October 2015 to March 2020 he was vice Dean for Studies and Teaching and since April 2020 Vice Dean for International relations of the Faculty.
Abstract:This lecture ties in with the current debate surrounding the so-called ‘strategic autonomy’ of the European Union. It aims to critically examine, on the one hand, whether the EU possesses the political capacity to act autonomously in strategic matters and, on the other hand, whether the constitutional framework of primary Union law provides the necessary normative foundations for this. In particular, the question will be raised as to whether the Union’s self-description as a ‘normative power’ is tenable and is underpinned by appropriate policy tools. Finally, a possible transformation from ‘normative power’ to ‘military power’ will be examined from a legal perspective.
Camille Nessel holds a Ph.D. in political science and is currently a lecturer at the Université libre de Bruxelles (ULB), teaching within the Centre d’étude de la vie politique (Cevipol). Her research focuses on EU perceptions in trade, particularly regarding the EU’s relations with Indonesia and Vietnam, as well as on the “China threat” construction in EU economic security strategy. Camille was awarded a doctoral fellowship from FNRS and is now preparing a postdoctoral project on the construction of the “China threat” in EU economic policies. Having gained research experience in Southeast Asia while living in both Indonesia and Vietnam, she has acquired valuable expertise in the region. She has also worked for the European Commission, served as a political advisor for the Chair of the International Trade Committee in the European Parliament, and gained experience in the NGO sector, combining theory and practice in her teaching and research.